핀테크 모바일 결제 서비스의 수용The Adoption of Mobile Payment Services for “Fintech”
원문 제목: The Adoption of Mobile Payment Services for “Fintech”
번역 제목은 이 사이트의 편집 번역입니다. 서지와 인용에는 원문 제목을 사용합니다.Translated titles are editorial translations for this site. Bibliographic records and citations retain the original title.
International Journal of Applied Engineering Research, 11(2), 1058–1061색인: Indexed in: SCOPUS
요약Summary
정교화가능성모형과 기술수용 관련 변수를 결합해 모바일 결제 서비스 수용의도를 분석했다. 유용성·사용 용이성·신뢰성이 수용의도와 연결됐고, 개인정보 우려와 자기효능감의 역할도 함께 검토했다.
The paper combines the elaboration-likelihood model with technology-acceptance variables to examine mobile-payment intention. Usefulness, ease of use, and credibility are associated with intention, alongside roles for privacy concern and self-efficacy.
한눈에 보기At a glance
- 방법Methods
- Survey Research
- Path Analysis
- Elaboration Likelihood Model
- 키워드Keywords
- Fintech
- Mobile Payment
- Technology Adoption
- TAM
- Digital Finance
- Trust
- Security
원문을 바탕으로 연구의 논리와 결과를 풀어쓴 해설입니다. 수치는 표시한 표와 쪽을 기준으로 읽습니다. 아래 표는 핵심 항목을 웹에서 읽도록 재구성했고, 원문 표·그림이 있는 페이지를 함께 제공합니다.This reading guide explains the paper’s reasoning and findings in new wording. Tables below re-present selected source results for web reading, alongside images of the relevant original pages.
간편결제 수용은 어떤 판단에서 나오는가What judgments support mobile-payment adoption?
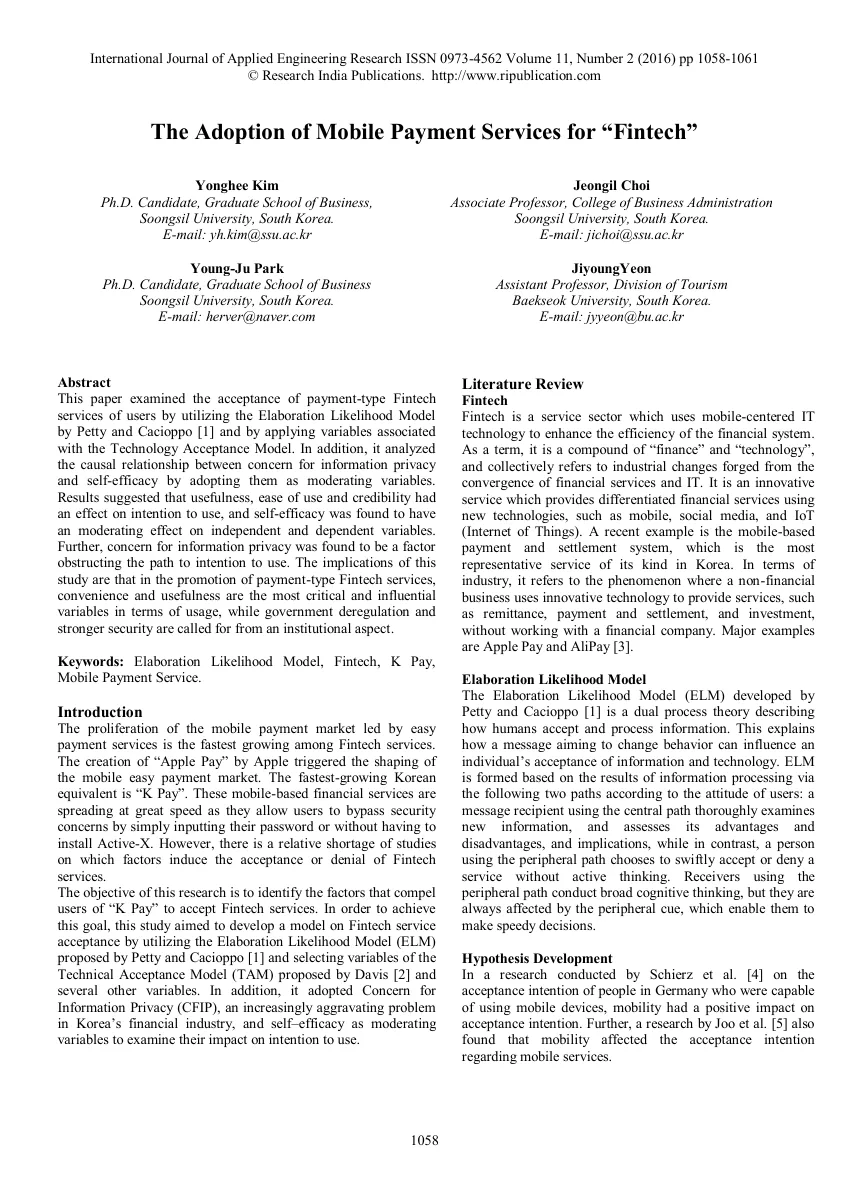
메신저에 결제를 붙이고 이동성을 높이면 이용자는 자연스럽게 받아들일까요? 이 논문은 K Pay라는 모바일 결제 맥락에서 유용성·사용 용이성·신뢰성과 이동성·사회적 영향의 관계를 비교합니다. 개인정보 우려와 스스로 기술을 사용할 수 있다는 자신감도 수용의도를 설명하는 요소로 넣었습니다.
The paper asks whether mobility and platform reach are enough to secure mobile-payment adoption. In a K Pay setting it compares usefulness, ease of use and credibility with mobility and social influence. Privacy concern and confidence in one’s own ability to use technology are also considered.
PDF 파일 1, 2쪽PDF pages 1, 2
수도권 중심 설문과 보고 범위A capital-area survey with limited reporting detail
원문은 서울·수도권과 특정 연령대에 치우친 설문이라는 한계를 밝힙니다. 다만 제공된 4쪽 논문에서 명확한 최종 표본 수와 상세 조사 시기를 확인할 수 없어 이를 새로 채워 넣지 않았습니다. 기술수용 문항에 관한 결과표가 있다고 해서 표본 대표성까지 확보된 것은 아닙니다.
The article acknowledges a survey concentrated in Seoul, the capital area and particular age groups. A clear final sample size and detailed fieldwork date are not identifiable in the four-page paper, so neither is supplied here. The presence of a path table does not establish representative sampling.
종속변수는 결제 서비스 이용의도입니다. 개인정보 우려 CFIP와 자기효능감은 직접 경로뿐 아니라 다른 수용 요인과의 상호작용에도 사용됩니다. 실제 결제금액·빈도·사기 피해·장기 유지율을 측정한 연구로 소개하지 않습니다.
The outcome is intention to use payment services. Concern for information privacy and self-efficacy enter both direct and interaction paths. The study should not be presented as measuring transaction spending, payment frequency, fraud losses or long-term retention; those outcomes are not reported in this analysis.
PDF 파일 1, 3쪽PDF pages 1, 3
설득 경로와 기술수용 변수를 연결Connect persuasion routes and acceptance constructs
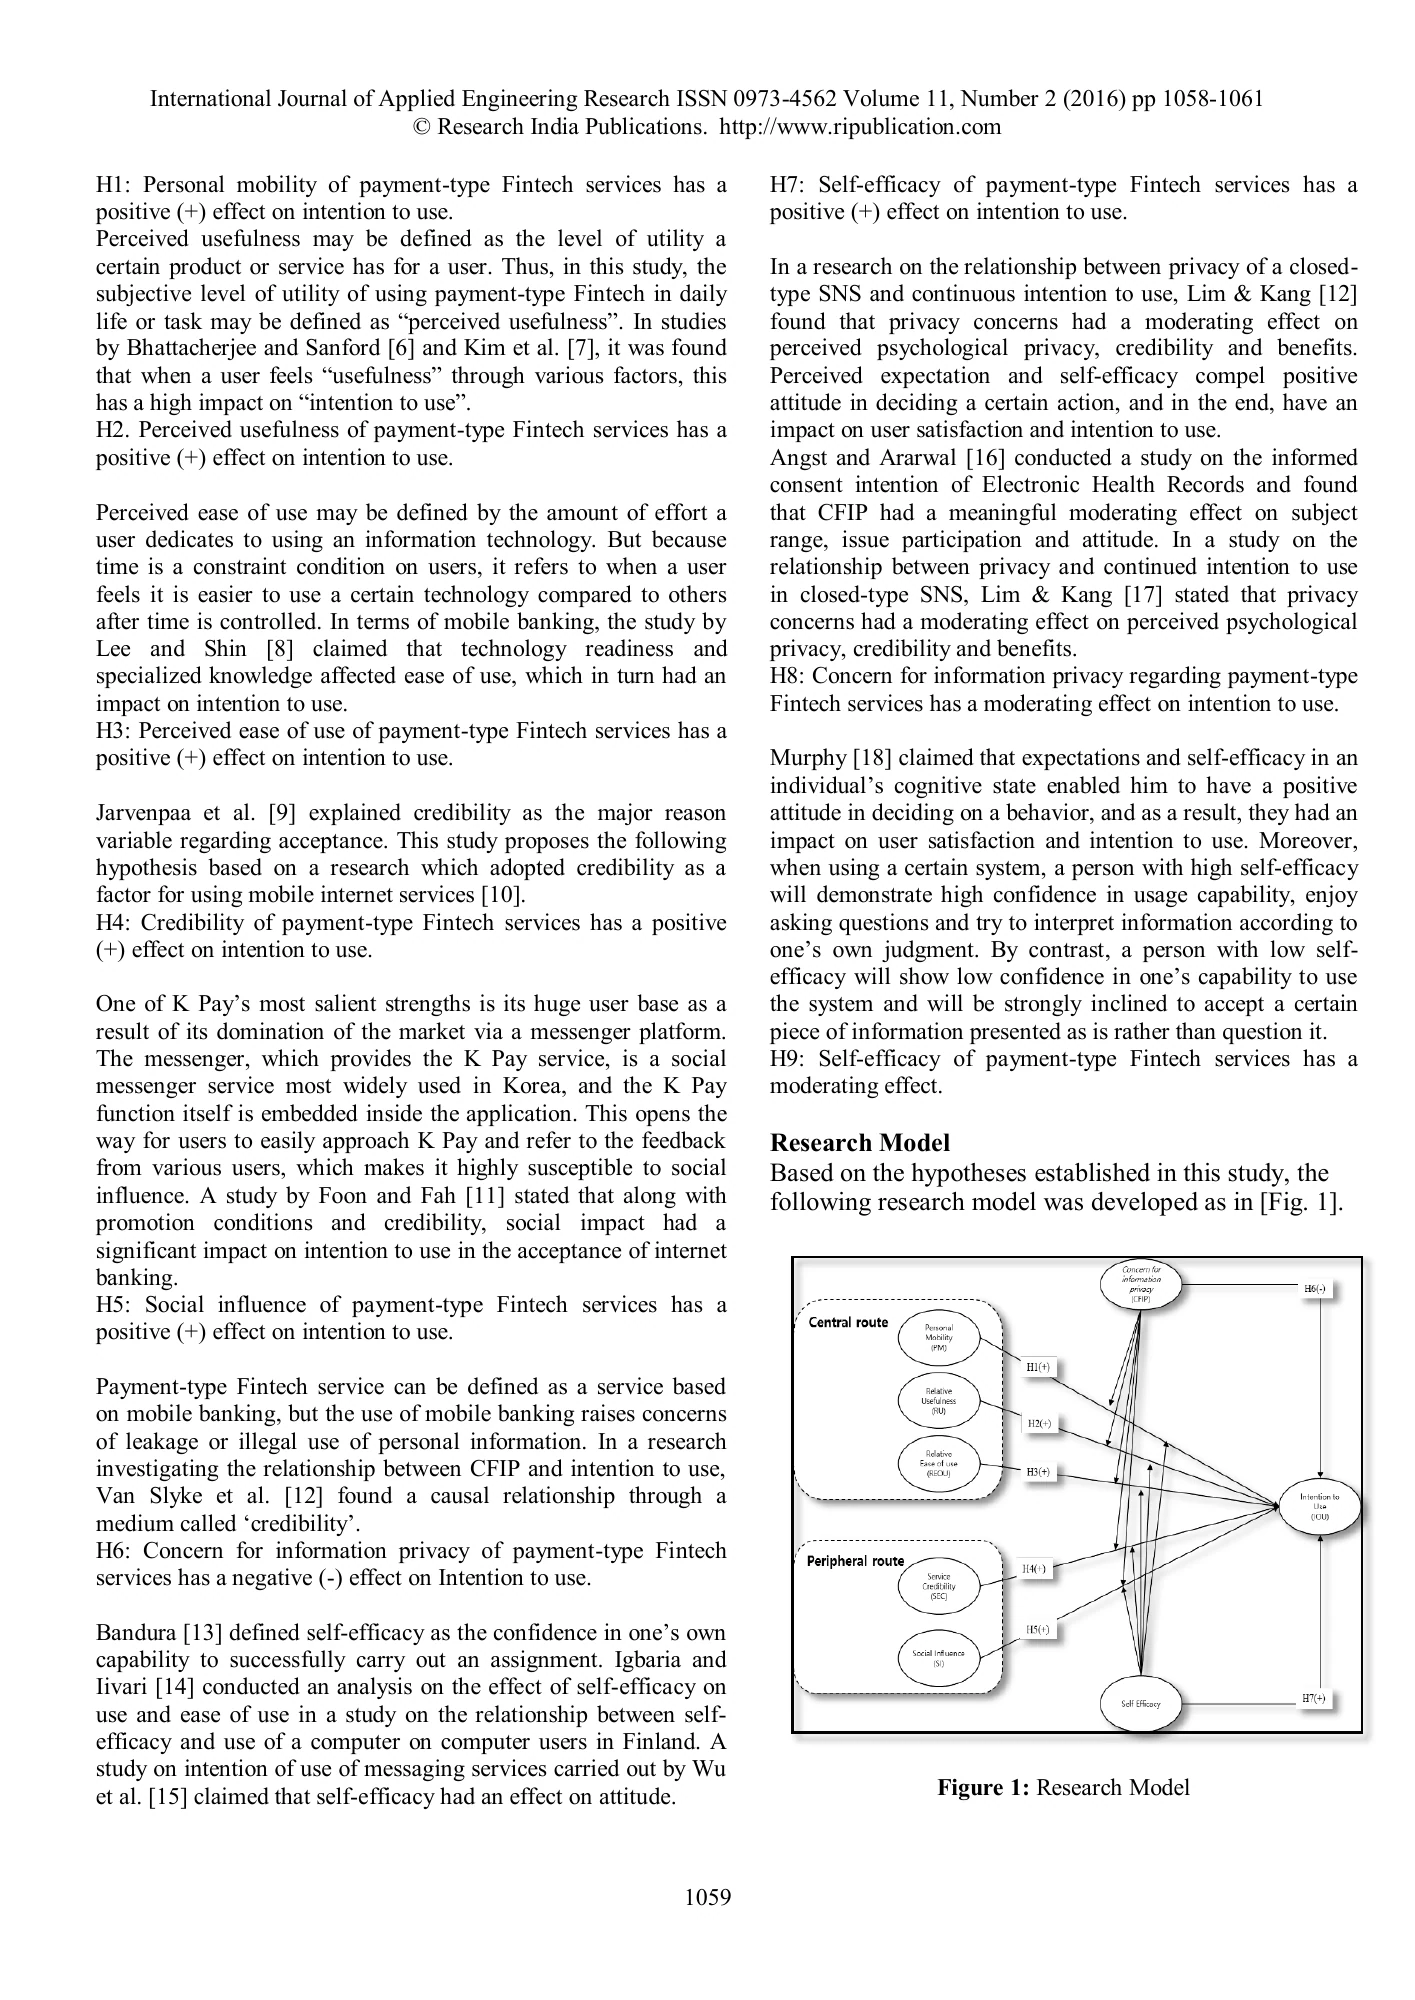
정교화가능성모형은 내용을 따져 보는 중심 경로와 주변 단서에 의존하는 경로를 구분합니다. 논문은 이를 기술수용 변수와 연결해 경로분석 모형을 만들었습니다. 상호작용 항은 개인정보 우려나 자기효능감 수준에 따라 각 요인과 의도의 관계가 달라지는지 살피는 장치입니다.
The elaboration-likelihood model distinguishes substantive processing from reliance on peripheral cues. The paper connects that framework to technology-acceptance variables in a path model. Interaction terms examine whether privacy concern or self-efficacy changes relationships between the acceptance factors and intention.
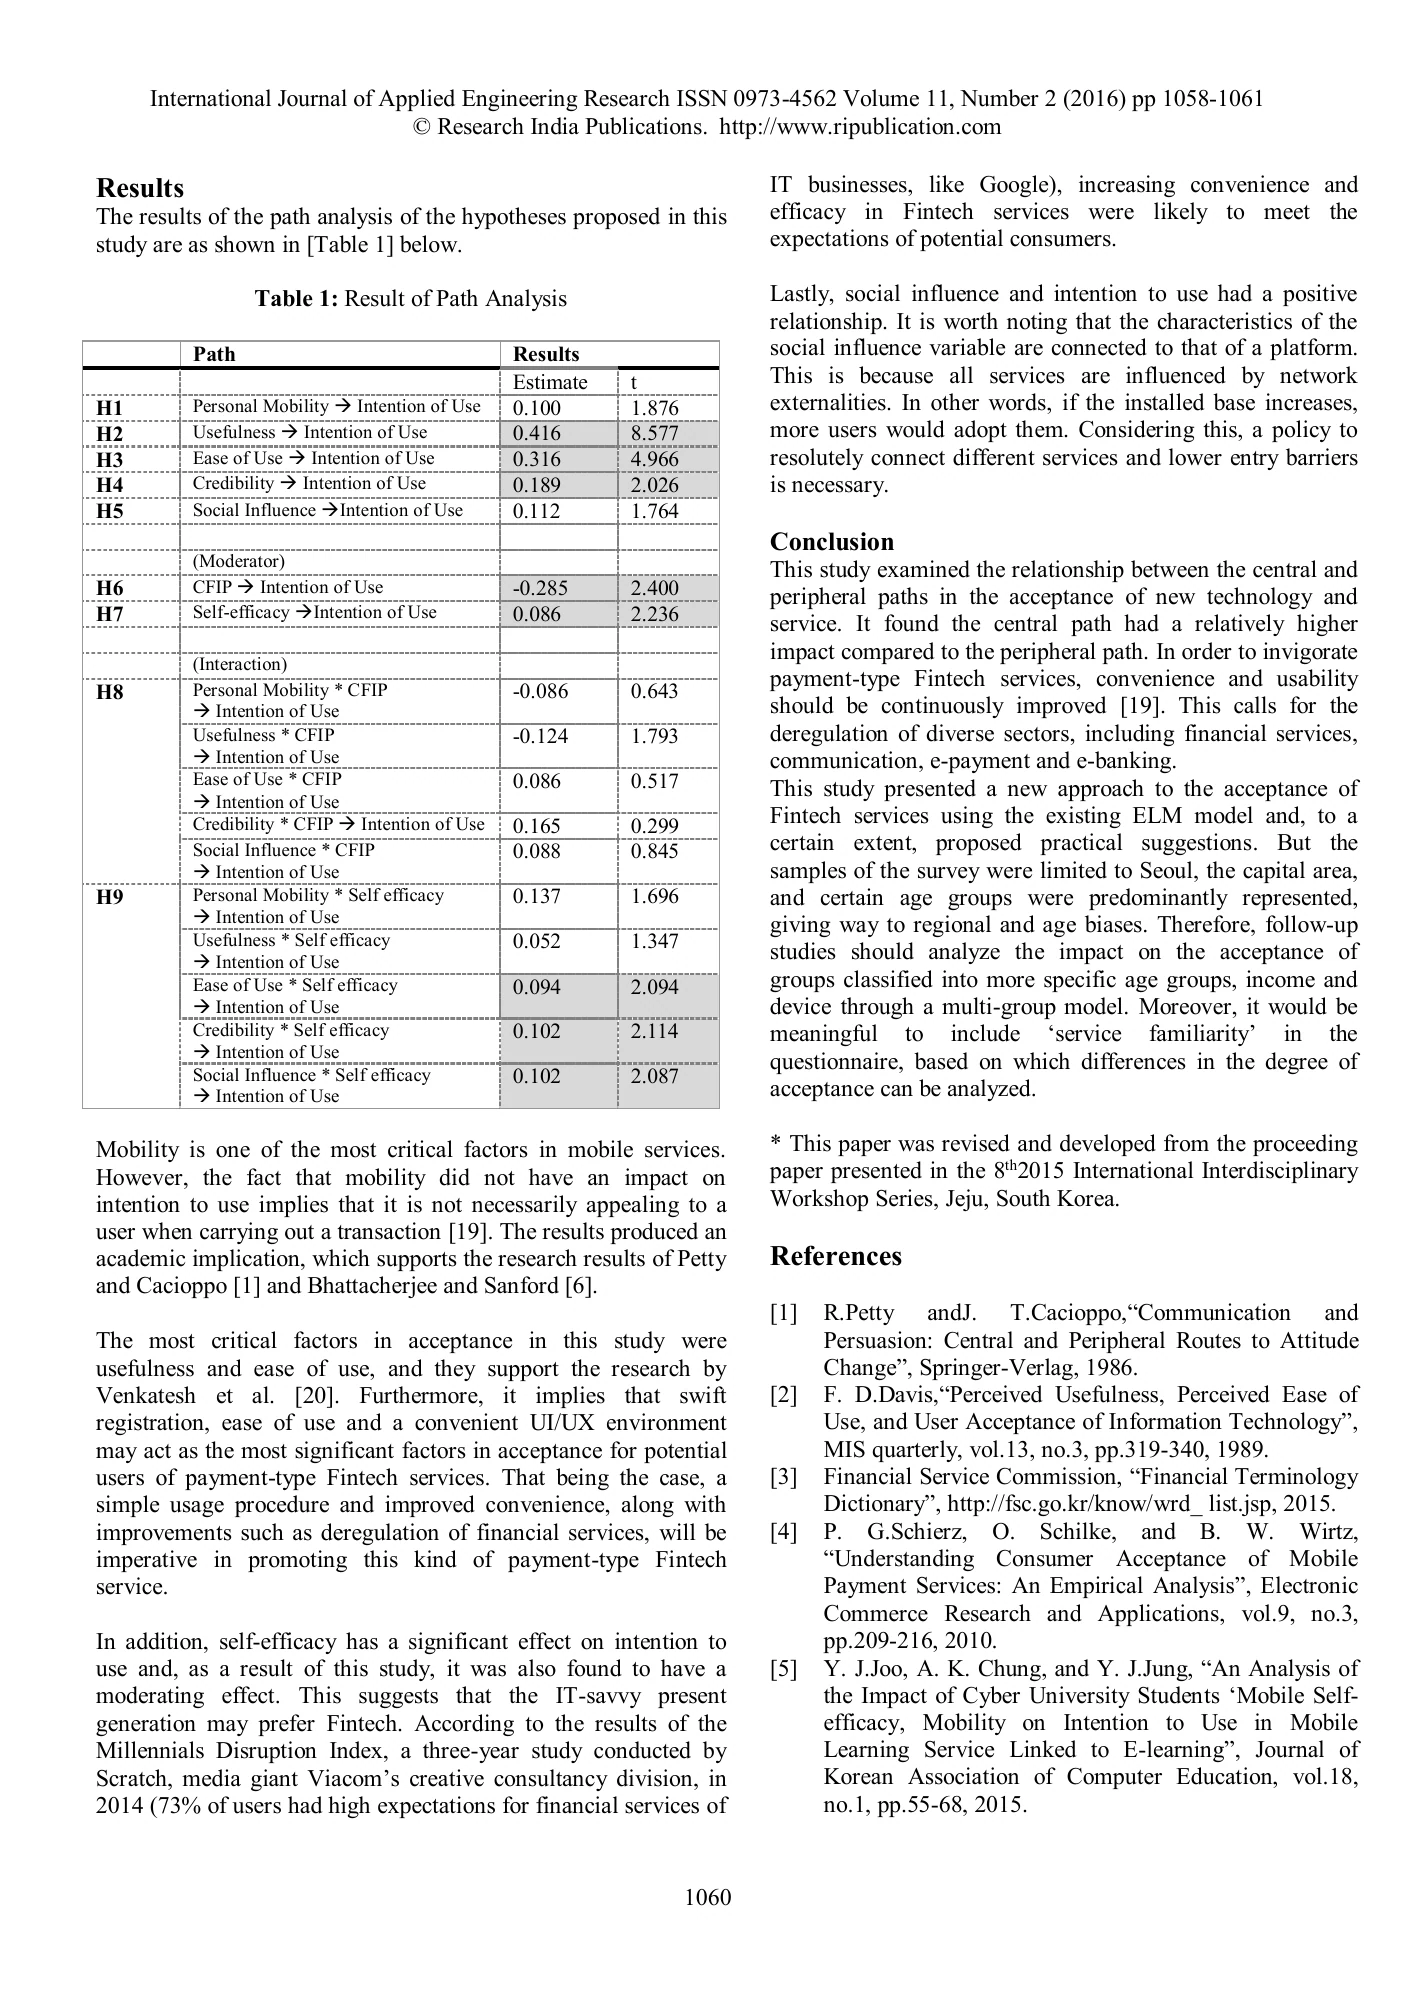
표 1은 계수와 t값을 제시하지만 모든 경로의 p값·신뢰구간을 제공하지는 않습니다. 따라서 홈페이지 표는 보고된 수치를 그대로 구분해 보여주고 근거 없는 정밀한 유의확률을 추가하지 않습니다. 작은 t값의 경로와 저자의 실무 해석도 동일한 확실성으로 묶지 않습니다.
Table 1 provides estimates and t statistics but not p-values or confidence intervals for every path. The comparison therefore retains reported statistics without inventing precise significance probabilities. Weak numerical paths and broader managerial discussion are not assigned the same evidential strength.
PDF 파일 1, 2, 3쪽PDF pages 1, 2, 3
유용성과 쉬운 사용의 계수가 상대적으로 큼Usefulness and ease show larger reported coefficients
이용의도에 대한 유용성 계수는 0.416(t=8.577), 용이성은 0.316(t=4.966), 신뢰성은 0.189(t=2.026)입니다. 이동성은 0.100(t=1.876), 사회적 영향은 0.112(t=1.764)로 보고되어 모든 양의 계수를 같은 강도의 지지로 읽지 않습니다.
Reported coefficients to intention are 0.416 for usefulness (t=8.577), 0.316 for ease of use (t=4.966), and 0.189 for credibility (t=2.026). Mobility is 0.100 (t=1.876) and social influence 0.112 (t=1.764). Positive signs alone do not give all these paths equally strong support.
개인정보 우려의 직접 계수는 −0.285(t=2.400), 자기효능감은 0.086(t=2.236)입니다. 자기효능감과 용이성·신뢰성·사회적 영향의 상호작용 t값은 약 2 이상으로 제시됩니다. 이는 기술 자신감의 조건부 역할을 논의할 근거이지만 실제 금융 피해 감소나 결제 성공을 증명하지 않습니다.
The privacy-concern coefficient is −0.285 (t=2.400), while self-efficacy is 0.086 (t=2.236). Reported interactions involving self-efficacy with ease, credibility and social influence have t statistics around or above two. These inform a conditional acceptance interpretation, not evidence of reduced financial harm or successful real transactions.
PDF 파일 3쪽PDF page 3
핵심 결과를 표로 읽기Read the key results in tables
| 설명변수Predictor | 계수Estimate | t |
|---|---|---|
| 유용성Usefulness | 0.416 | 8.577 |
| 사용 용이성Ease of use | 0.316 | 4.966 |
| 신뢰성Credibility | 0.189 | 2.026 |
| 개인정보 우려Privacy concern | −0.285 | 2.400 |
| 자기효능감Self-efficacy | 0.086 | 2.236 |
표 1의 선택 직접 경로. 원문에서 확인되지 않은 N·p값은 추가하지 않았습니다. 상호작용과 분리한 표입니다.Selected direct paths from Table 1. No unreported N or p-values are added. Interaction estimates are separate from these direct paths.
원문 표 1 발췌Selected direct paths from original Table 1 · PDF 파일 3쪽PDF page 3
원문의 핵심 표·그래프Key tables & figures in the source
표·그림이 수록된 원문 페이지입니다. 이미지를 누르면 확대할 수 있습니다.Original pages containing the selected tables or figures. Select an image to enlarge it.
간편결제 수용 연구모형Mobile-payment acceptance model
직접 경로와 상호작용 결과Direct and interaction estimates
복잡한 기능보다 편의와 신뢰를 점검Examine convenience and credibility alongside features
저자는 빠른 가입과 단순한 이용 절차, 편리한 UI·UX, 보안과 제도 환경을 강조합니다. 연구의 범위에서 보면 서비스가 유용하고 쉽게 느껴지는지와 개인정보 우려를 함께 점검하는 설계 방향입니다. 특정 규제 완화의 효과나 특정 결제 플랫폼의 우월성을 검증한 결과로 바꾸어 소개하지 않습니다.
The discussion emphasizes straightforward registration, simple procedures, convenient interfaces, security and the institutional environment. Within the evidence, this suggests examining perceived usefulness and ease together with privacy concern. It does not demonstrate a particular deregulation’s effect or establish the superiority of one payment platform.
PDF 파일 3쪽PDF page 3
짧은 논문의 불완전한 보고와 일반화 한계Short-paper reporting and generalization limits
저자가 밝힌 지역·연령 편향 외에도 표본 수·상세 측정 및 분석 보고가 제한적입니다. 당시 간편결제의 서비스 친숙도와 현재 상황도 다릅니다. 후속 연구에서 연령·소득·기기·친숙도를 나눠 검증할 필요가 있으며, 이 자료만으로 전국 이용자의 현재 수용률이나 인과효과를 추정하지 않습니다.
Beyond the acknowledged regional and age biases, sample and measurement reporting is limited. Historical familiarity with payment services also differs from today. Further work should compare age, income, device and familiarity groups. The article cannot estimate current national adoption rates or establish causal effects from this information alone.
PDF 파일 3쪽PDF page 3
근거 쪽: Evidence pages: 1, 2, 3, 4 · PDF 파일 기준, 인쇄 쪽수와 다를 수 있습니다. · PDF file pagination may differ from printed page numbers.
원문 이미지 보기 · 1장View original document images · 1
서지 정보Bibliographic information
- 학술지Journal
- International Journal of Applied Engineering Research
- 권(호)Volume (issue)
- 11(2)
- 쪽Pages
- 1058–1061
- 게재Published
- 2016
- 색인Indexing
-
- SCOPUS (저자 실적 기록 기준)(per the author's records)
- 인용Citations
- Google Scholar 인용 416Cited by 416 (Google Scholar) (새 창) (opens in a new tab) (2026-09-27 기준)(as of 2026-09-27)
인용하기Cite APA · BibTeX
APA
Kim, Y., Park, Y.-J., Choi, J., & Yeon, J. (2016). The Adoption of Mobile Payment Services for “Fintech”. International Journal of Applied Engineering Research, 11(2), 1058–1061.
BibTeX
@article{kim2016-fintech,
  author = {Kim, Yonghee and Park, Young-Ju and Choi, Jeongil and Yeon, Jiyoung},
  title = {The Adoption of Mobile Payment Services for “Fintech”},
  journal = {International Journal of Applied Engineering Research},
  year = {2016},
  volume = {11},
  number = {2},
  pages = {1058--1061}
}