비대칭적 시장 진화 속 플랫폼 권력: 한국 홈쇼핑 시장의 실증 근거Platform Power Under Asymmetric Market Evolution: Evidence from Korean Home Shopping
원문 제목: Platform Power Under Asymmetric Market Evolution: Evidence from Korean Home Shopping
번역 제목은 이 사이트의 편집 번역입니다. 서지와 인용에는 원문 제목을 사용합니다.Translated titles are editorial translations for this site. Bibliographic records and citations retain the original title.
저자 표시: Author notes: 굵은 글씨: 김용희Bold: Yonghee Kim 교신저자Corresponding author
Sustainability, 17(14), 논문 번호 6248Article 6248색인: Indexed in: SSCI
요약Summary
2015~2023년 한국 홈쇼핑 기업의 104개 기업·연도 관측치로 플랫폼 집중과 콘텐츠 공급자 분산이 송출수수료 및 수익성과 맺는 관계를 분석했다. 문턱 회귀와 도구변수 분석은 수수료 구간별로 관계가 달라지고 단순 회귀가 선택 편의를 가질 수 있음을 보여준다.
Using 104 firm-year observations from Korean home-shopping firms over 2015–2023, the paper examines platform concentration, supplier fragmentation, transmission fees, and profitability. Threshold and instrumental-variable analyses indicate regime-dependent relationships and selection bias in simple regressions.
한눈에 보기At a glance
- 자료 기간Data period
- 2015 – 2023
- 표본 크기Sample size
- N = 104
- 방법Methods
- Panel Fixed-Effects Regression
- Hansen Threshold Regression
- Instrumental Variables
- 키워드Keywords
- Platform Power
- Home Shopping
- Market Asymmetry
- TV Commerce
- Sustainability
- Network Effects
- Korea
원문을 바탕으로 연구의 논리와 결과를 풀어쓴 해설입니다. 수치는 표시한 표와 쪽을 기준으로 읽습니다. 아래 표는 핵심 항목을 웹에서 읽도록 재구성했고, 원문 표·그림이 있는 페이지를 함께 제공합니다.This reading guide explains the paper’s reasoning and findings in new wording. Tables below re-present selected source results for web reading, alongside images of the relevant original pages.
플랫폼 집중과 공급자 분산이 동시에 진행되면When platforms consolidate while suppliers fragment
플랫폼은 집중되는데 콘텐츠 공급자는 더 잘게 나뉜다면 협상 관계는 어떻게 바뀔까요? 이 논문은 한국 홈쇼핑의 송출수수료를 통해 두 시장의 비대칭적 변화를 살핍니다. 높은 수수료를 내는 기업의 수익성이 높게 보이는 현상을 곧바로 '수수료가 수익을 높인다'고 읽지 않고, 기업의 선택과 적응을 검토합니다.
The paper studies asymmetric evolution: distribution platforms consolidate while content suppliers fragment. Korean home-shopping transmission fees provide the setting. It asks how this bargaining environment relates to fees and profitability, including why high-fee firms can appear more profitable without implying that higher fees mechanically improve profits.
PDF 파일 1, 8, 9쪽PDF pages 1, 8, 9
2015~2023년 기업·연도 관측치 104개One hundred four firm-year observations
허가 홈쇼핑 채널의 2015~2023년 자료를 바탕으로 107개 초기 관측치에서 극단치 3개를 제외해 104개를 분석했습니다. 기업 수와 관측연도가 완전히 같은 균형 패널은 아닙니다. 수수료율은 홈쇼핑 매출 대비 송출수수료, 수익률은 해당 매출 대비 영업이익으로 정의합니다.
The analysis starts with 107 observations for licensed home-shopping channels in 2015–2023 and removes three extreme outliers, leaving 104 firm-years. The panel is unbalanced. Transmission-fee rate is fees divided by home-shopping revenue, while profitability is operating profit relative to that revenue.
플랫폼 및 홈쇼핑 시장의 HHI, 대기업 계열 여부, 시청률, 매출 규모, 코로나 이후 기간도 사용합니다. 평균 송출수수료율은 52.41%, 표준편차는 15.39%이며 관측 범위가 넓어 기업 간 차이와 시간 변화를 구분해야 합니다.
The data include platform and home-shopping concentration, major-conglomerate affiliation, audience ratings, revenue and the post-COVID period. Mean fee rate is 52.41%, with standard deviation 15.39 percentage points. Wide variation makes it important to distinguish cross-firm differences from changes within individual firms.
PDF 파일 10, 11, 12, 13쪽PDF pages 10, 11, 12, 13
단순 회귀·고정효과·도구변수의 결론을 비교Compare pooled, within-firm and instrumental-variable estimates
문턱 분석은 수수료율 구간에 따라 수익성의 관계가 달라지는지를 살핍니다. 기업 고정효과는 같은 기업 안에서 수수료가 달라질 때의 관계를 추정하고, 도구변수는 시차 플랫폼 집중도를 이용해 수수료의 내생성을 점검합니다. 이 세 접근은 서로 다른 질문과 식별 가정을 가집니다.
Threshold analysis looks for fee regimes with different profitability patterns. Firm fixed effects focus on within-firm variation, while an instrumental-variable model uses lagged platform concentration to address fee endogeneity. These approaches answer different questions and rely on different assumptions, rather than being interchangeable versions of one estimate.
특히 도구변수의 1단계가 강하다는 진단만으로 배제제약까지 성립하는 것은 아닙니다. 높은 수수료를 감당한 기업이 남는 선택 효과라는 저자의 해석과, 그 해석을 확정하기 위해 필요한 기업 퇴출·계약 변화 자료는 구분해서 읽을 필요가 있습니다.
A strong first stage does not by itself validate the instrument’s exclusion restriction. The authors interpret the estimates partly through selection among firms able to tolerate high fees. That interpretation should be distinguished from directly observing every exit, contract change or strategic adjustment needed to establish the mechanism conclusively.
PDF 파일 14, 17, 18, 20쪽PDF pages 14, 17, 18, 20
기업 내 변화는 불확실하고 IV 결과는 더 큼Within-firm estimates are uncertain; IV estimates are larger
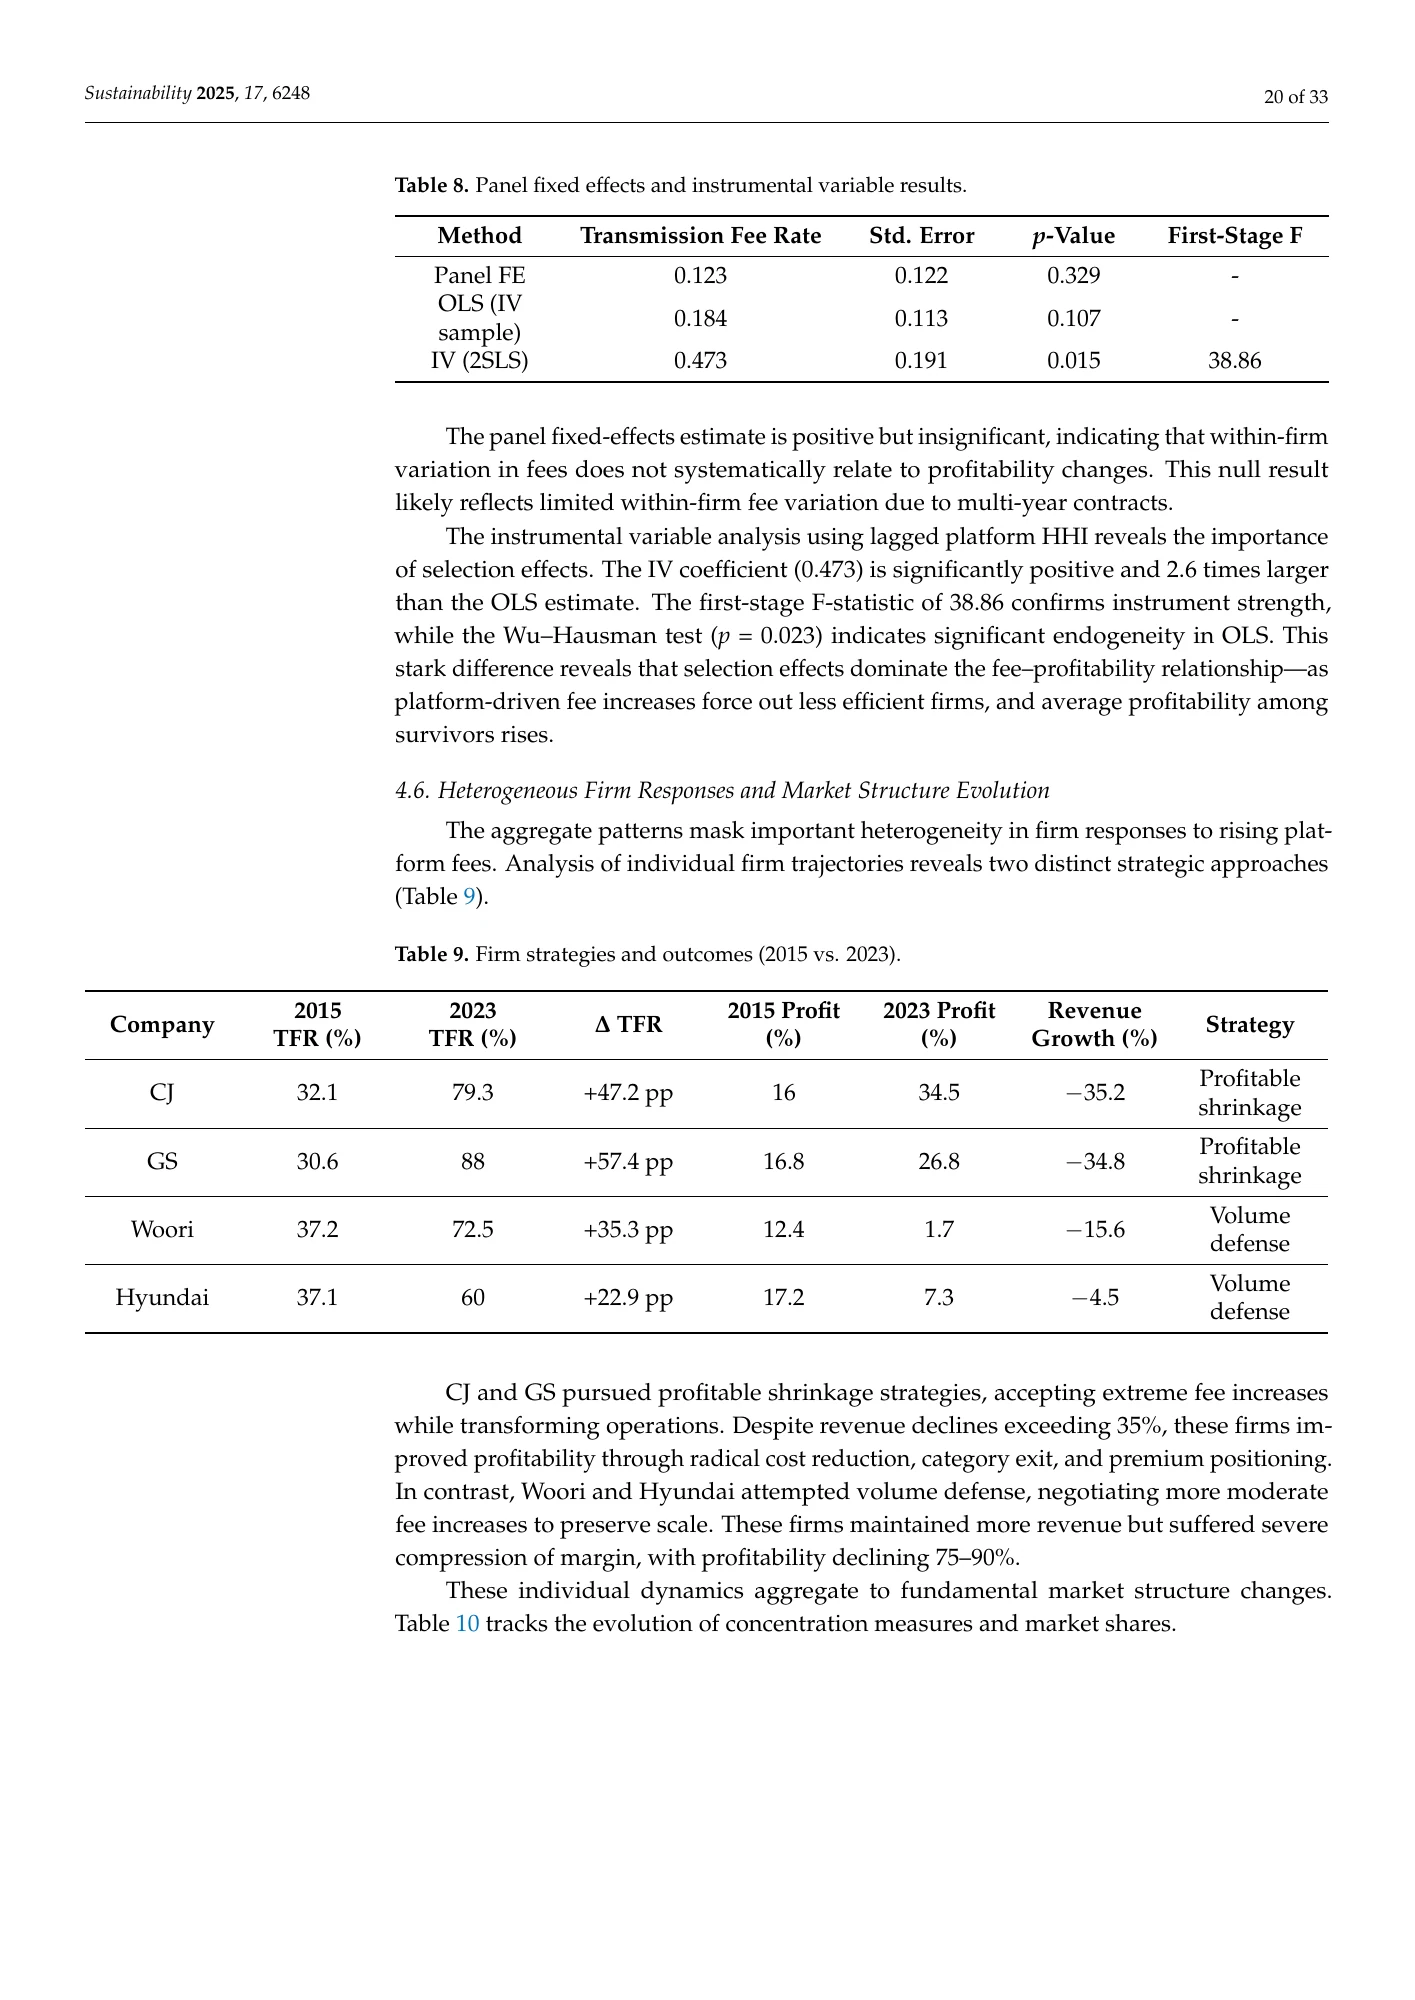
표 8에서 고정효과 계수는 0.123(p=0.329), 도구변수와 같은 표본의 OLS는 0.184(p=0.107)로 유의하지 않습니다. 2SLS 계수는 0.473(p=0.015), 1단계 F는 38.86입니다. 방법에 따른 차이는 단순 상관관계를 보편적인 비용 효과로 해석하기 어렵다는 점을 보여줍니다.
Table 8 reports an insignificant fixed-effects estimate of 0.123 (p=0.329) and same-sample OLS estimate of 0.184 (p=0.107). The 2SLS coefficient is 0.473 (p=0.015), with first-stage F=38.86. Estimator differences caution against interpreting a simple correlation as a universal fee effect.
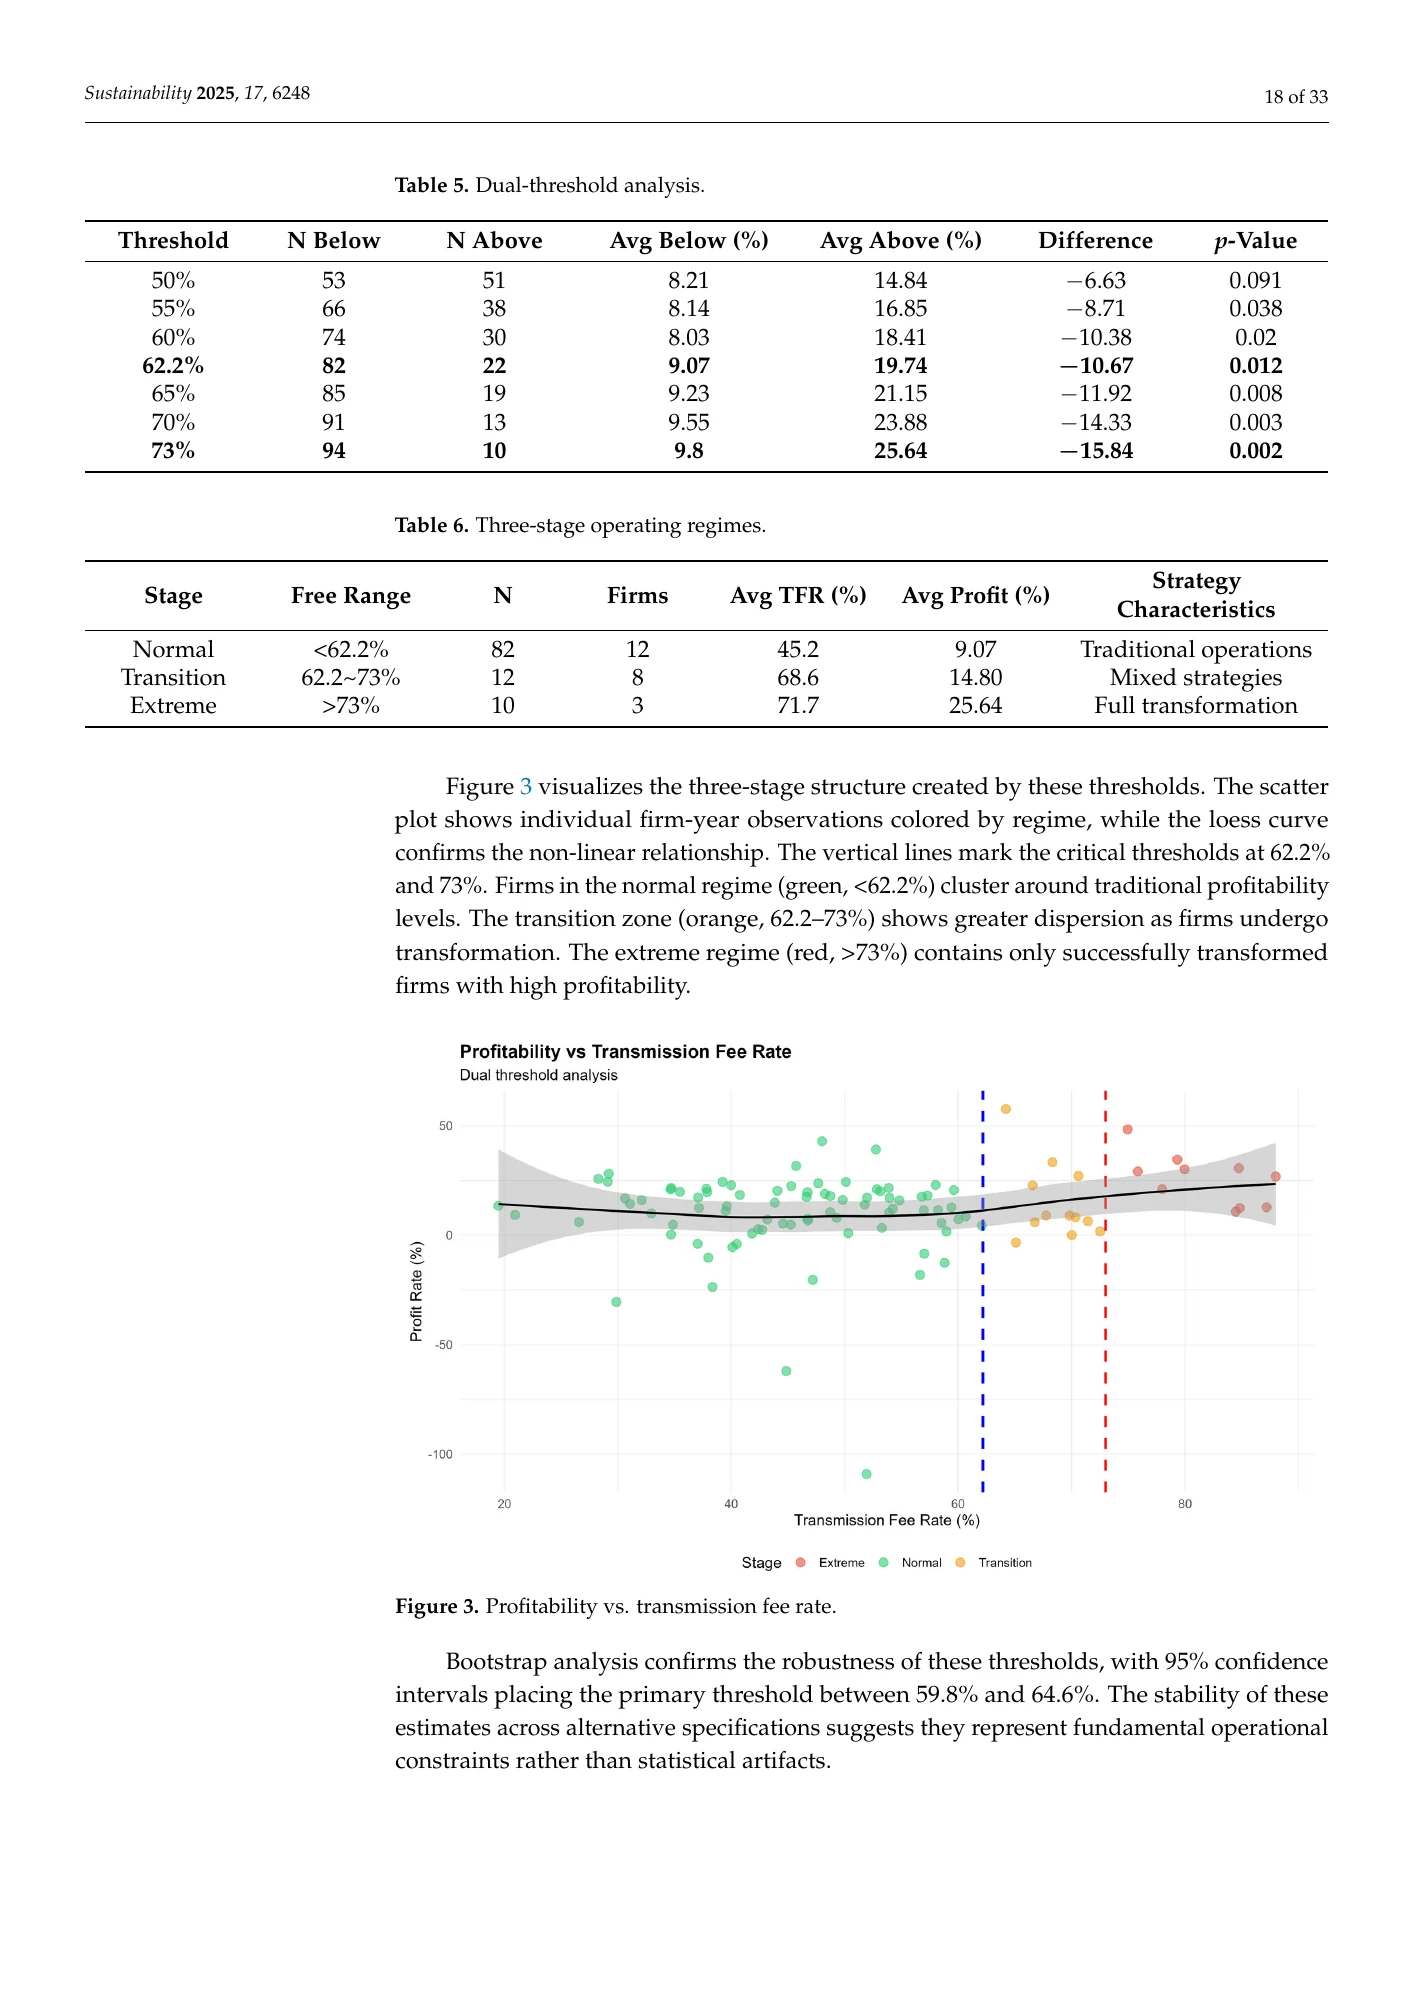
문턱 분석은 62.2% 및 73% 부근의 구간을 논의하지만, 원문의 일부 구간 요약 수치에는 내부 정합성 확인이 필요합니다. 따라서 이 해설은 수수료 상한의 확정 정답을 제시하지 않으며, 검증 가능한 표 8의 계수와 모형별 차이를 핵심 결과로 삼습니다.
The threshold discussion focuses on values around 62.2% and 73%, but some printed regime summaries require internal consistency checks. This explanation therefore does not present a definitive optimal fee cap. It emphasizes the verifiable Table 8 estimates and the differences among empirical specifications.
PDF 파일 13, 18, 20쪽PDF pages 13, 18, 20
핵심 결과를 표로 읽기Read the key results in tables
| 방법Method | 계수Coefficient | 표준오차Standard error | p |
|---|---|---|---|
| Panel FE | 0.123 | 0.122 | 0.329 |
| OLS (IV sample) | 0.184 | 0.113 | 0.107 |
| IV (2SLS) | 0.473 | 0.191 | 0.015 |
원문 표 8. IV 1단계 F=38.86. 서로 다른 추정·식별 가정의 계수이며 수수료 인상이 모든 기업의 수익을 높인다는 결론은 아닙니다.Original Table 8. IV first-stage F=38.86. Estimates rely on different identification assumptions and do not establish that raising fees benefits every firm.
원문 표 8 발췌Selected values from original Table 8 · PDF 파일 20쪽PDF page 20
원문의 핵심 표·그래프Key tables & figures in the source
표·그림이 수록된 원문 페이지입니다. 이미지를 누르면 확대할 수 있습니다.Original pages containing the selected tables or figures. Select an image to enlarge it.
고정효과와 도구변수 비교Fixed effects and instrumental variables
수수료–수익성 산점도Fee–profitability scatterplot
규모만이 아니라 거래 양측의 구조를 보기Examine both sides of the bargaining structure
플랫폼 규제 논의에서 한쪽 시장의 크기나 집중도만 보지 않고 공급자 쪽의 분산과 협상 대안을 함께 볼 필요가 있다는 제안입니다. 공동협상·중재·거래조건 감시와 같은 대안은 연구의 정책 논의이며, 시행된 효과를 측정한 결과와 구분합니다. 모의실험에서의 후생 수치도 실제 정책 성과가 아닙니다.
The discussion recommends examining supplier fragmentation and bargaining alternatives alongside platform concentration. Collective negotiation, arbitration and monitoring are proposed policy options, not measured implementation outcomes. Welfare values from simulations likewise represent model-based scenarios rather than observed benefits from a real policy change.
PDF 파일 24, 25, 26쪽PDF pages 24, 25, 26
표본·도구변수 가정과 원문 수치 충돌Sample, identification and printed inconsistencies
104개 관측치와 특정 산업에 기반한 결과이며 극단치 제외, 기업 간 생존·사업모델 차이, 도구변수 가정에 민감합니다. 표 6은 '>73%' 구간의 평균 수수료율을 71.7%로 적고 있어 구간 정의와 충돌합니다. 표 3 전후의 증가폭 설명도 표의 양끝 값과 맞지 않아 해당 증가율과 구간 평균은 재사용하지 않았습니다.
The sample is small and industry-specific, with sensitivity to outlier treatment, survival, business-model differences and IV assumptions. Table 6 reports a 71.7% average for the '>73%' regime, conflicting with its label. Nearby growth descriptions also conflict with Table 3 endpoints, so those growth and regime-average figures are not reused.
PDF 파일 13, 18, 20, 27, 28쪽PDF pages 13, 18, 20, 27, 28
근거 쪽: Evidence pages: 1, 8, 9, 10, 11, 12, 13, 14, 17, 18, 19, 20, 24, 25, 26, 27, 28 · PDF 파일 기준, 인쇄 쪽수와 다를 수 있습니다. · PDF file pagination may differ from printed page numbers. 원문 출처 ↗Source ↗
원문 이미지 보기 · 1장View original document images · 1
서지 정보Bibliographic information
- 학술지Journal
- Sustainability
- 권(호)Volume (issue)
- 17(14)
- 논문 번호Article number
- 6248
- 게재Published
- 2025-07-08
- 색인Indexing
-
- SSCI (저자 실적 기록 기준)(per the author's records)
- 인용Citations
- Google Scholar 인용 1Cited by 1 (Google Scholar) (새 창) (opens in a new tab) (2026-09-27 기준)(as of 2026-09-27)
인용하기Cite APA · BibTeX
APA
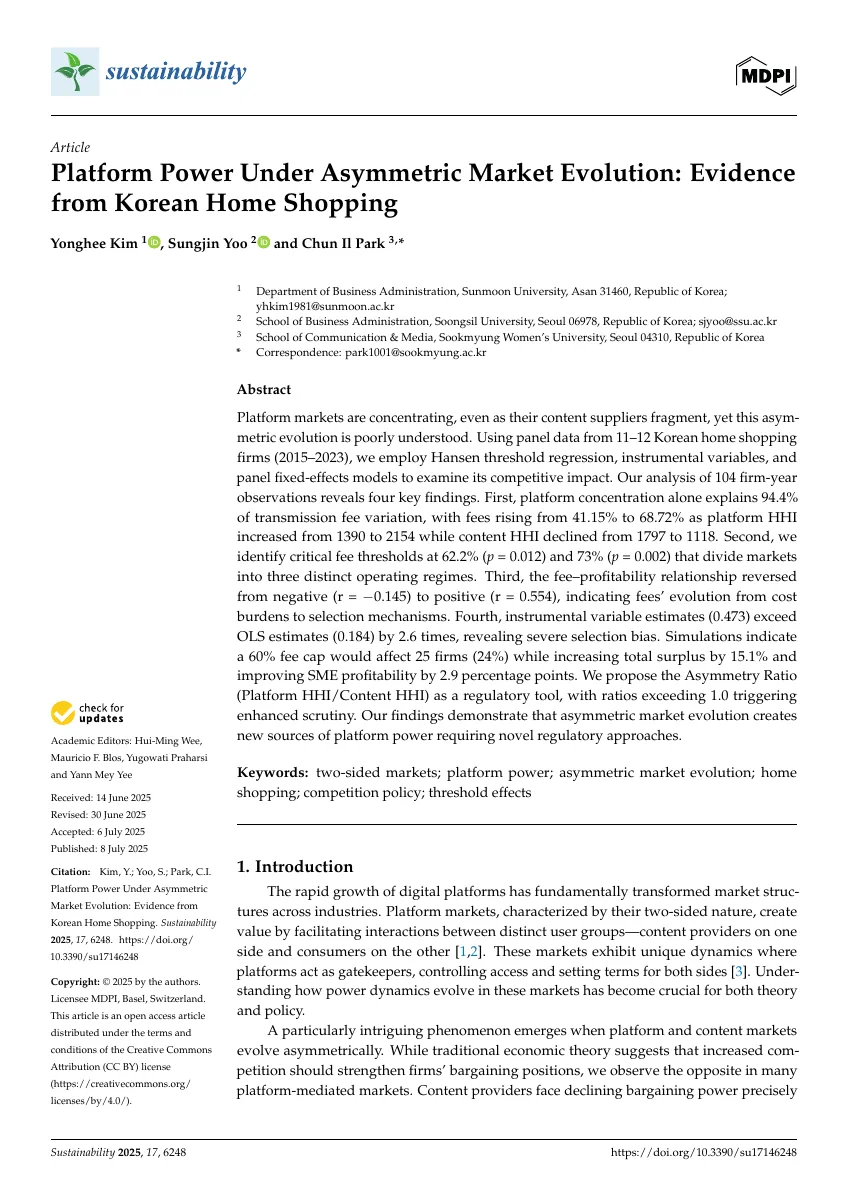
Kim, Y., Yoo, S., & Park, C. I. (2025). Platform Power Under Asymmetric Market Evolution: Evidence from Korean Home Shopping. Sustainability, 17(14), Article 6248. https://doi.org/10.3390/su17146248
BibTeX
@article{kim2025-platform,
  author = {Kim, Yonghee and Yoo, Sungjin and Park, Chun Il},
  title = {Platform Power Under Asymmetric Market Evolution: Evidence from Korean Home Shopping},
  journal = {Sustainability},
  year = {2025},
  volume = {17},
  number = {14},
  eid = {6248},
  doi = {10.3390/su17146248}
}