규제 샌드위치 효과: 플랫폼 규제 논의에 대한 기업 규모별 시장 반응The Regulatory Sandwich Effect: Firm-Size Differences in Market Responses to Platform Regulation Debates
Original title: 규제 샌드위치 효과: 플랫폼 규제 논의에 대한 기업 규모별 시장 반응
번역 제목은 이 사이트의 편집 번역입니다. 서지와 인용에는 원문 제목을 사용합니다.Translated titles are editorial translations for this site. Bibliographic records and citations retain the original title.
저자 표시: Author notes: 굵은 글씨: 김용희Bold: Yonghee Kim 교신저자Corresponding author
대한경영학회지, 39(2), 401–421색인: Indexed in: KCI
요약Summary
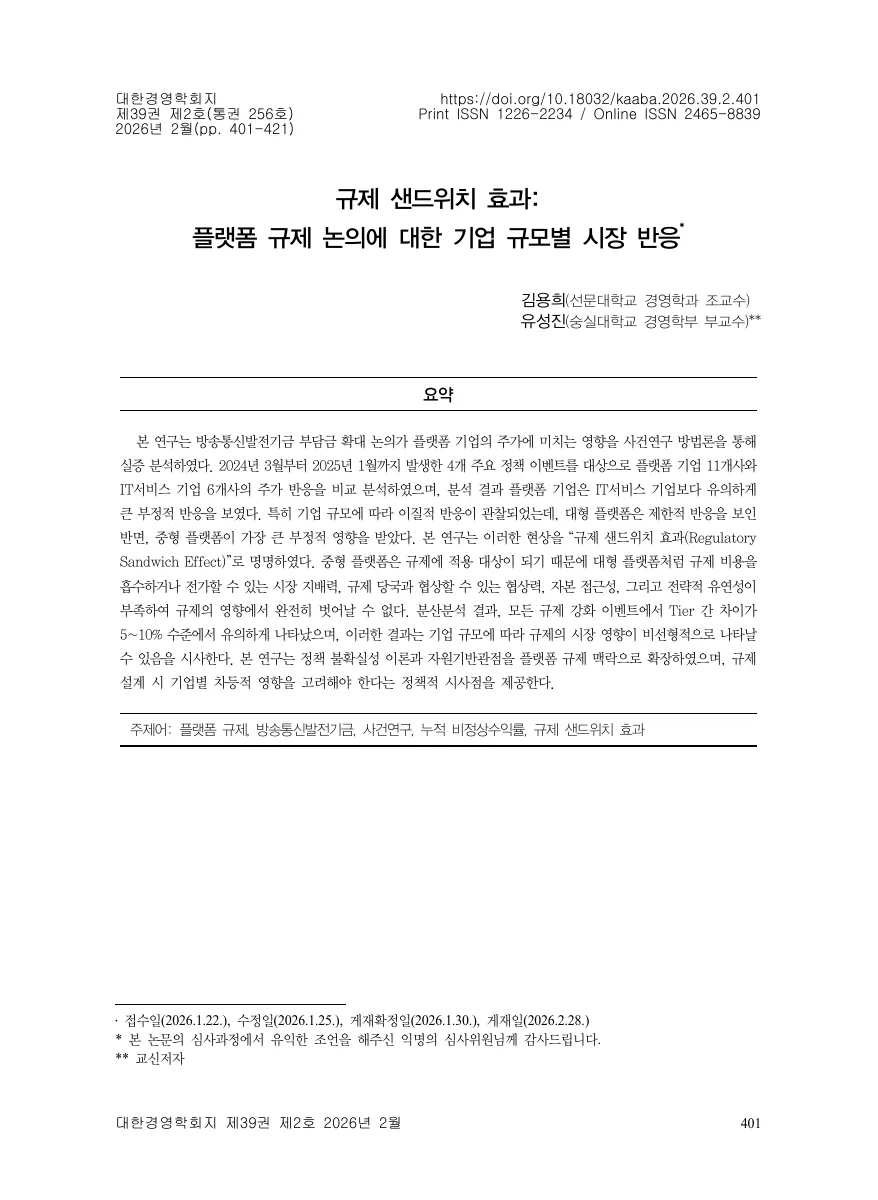
2024년 3월~2025년 1월의 4개 정책 이벤트에 대해 플랫폼 11개사와 IT서비스 6개사의 주가 반응을 비교했다. 플랫폼 기업의 부정적 반응이 더 컸고 특히 중형 플랫폼에서 가장 큰 반응이 관찰돼 이를 규제 샌드위치 효과로 설명했다.
An event study compares 11 platform firms and 6 IT-service firms across four policy events from March 2024 to January 2025. Platform firms show more negative reactions, especially medium-sized platforms, a pattern termed the regulatory sandwich effect.
한눈에 보기At a glance
- 자료 기간Data period
- 2023-01-02 – 2025-10-30
- 방법Methods
- Event Study
- Cumulative Abnormal Returns
- Analysis of Variance
원문을 바탕으로 연구의 논리와 결과를 풀어쓴 해설입니다. 수치는 표시한 표와 쪽을 기준으로 읽습니다. 아래 표는 핵심 항목을 웹에서 읽도록 재구성했고, 원문 표·그림이 있는 페이지를 함께 제공합니다.This reading guide explains the paper’s reasoning and findings in new wording. Tables below re-present selected source results for web reading, alongside images of the relevant original pages.
규제 논의에 누가 가장 민감하게 반응하는가Who reacts most strongly to regulatory debate?
이 논문은 방송통신발전기금 부담금의 플랫폼 확대 논의가 실제 시행 이전부터 기업가치에 반영되는지, 그 반응이 기업 규모에 따라 달라지는지를 묻는다. 저자들은 규제 노출과 대응 역량을 함께 보아야 한다고 주장한다. 규모가 작아 적용 대상에서 벗어날 가능성이 있는 기업과 비용 흡수 역량을 가진 대기업 사이에서 중형 기업이 더 취약할 수 있다는 설명이 ‘규제 샌드위치 효과’다.
The paper asks whether debate over extending broadcasting and communications fund levies to platforms is reflected in share prices before implementation, and whether responses differ by firm size. Its proposed regulatory sandwich combines exposure with response capacity: medium-sized firms may face obligations without the financial and organizational resources available to larger platforms.
PDF 파일 1, 8, 14, 15쪽PDF pages 1, 8, 14, 15
17개 상장사의 주가와 네 개 정책 이벤트Seventeen listed firms and four policy events
플랫폼 11개사와 IT서비스 6개사를 비교한다. 플랫폼은 최초 이벤트 직전인 2024년 3월 14일 시가총액으로 대형 3개사, 중형 4개사, 소형 4개사로 분류했다. 주가 자료는 2023년 1월 2일~2025년 10월 30일의 11,713개 기업·일 관측치다. 논문이 정책 이벤트로 식별한 시점은 2024년 3월 15일·6월 20일·9월 10일과 2025년 1월 8일이다. 세 시점은 규제 강화, 한 시점은 완화 신호로 구분했다.
The sample contains eleven platforms and six IT-service firms. Platforms are divided into three large, four medium, and four small firms using market capitalization on 14 March 2024. The reported price dataset has 11,713 firm-day observations from January 2023 to October 2025. The authors classify three of four selected policy events as tightening signals and one as easing.
PDF 파일 9, 10, 11쪽PDF pages 9, 10, 11
시장 전체 움직임을 뺀 사건연구An event study net of market movements
먼저 이벤트 이전 110거래일(-120~-11일)에 개별 주가수익률과 KOSPI 수익률의 관계를 추정한다. 이를 이용한 정상수익률을 실제 수익률에서 빼 비정상수익률을 구하고, 이벤트 전후 3일·5일·11일 동안 더한다. 기업집단 평균인 CAAR을 통해 공통 시장 변동을 넘어선 반응을 비교한다. 집단 간 t검정, 규모별 분산분석과 부호검정을 사용하며, 장기 매출이나 실제 납부 부담을 직접 추정한 연구와는 구분된다.
A market model is estimated over 110 pre-event trading days, from day −120 to −11. Abnormal returns are actual returns minus model-predicted returns; these are accumulated across event windows and averaged within groups. The study uses t-tests, tier comparisons, and sign tests. This measures short-run valuation responses rather than realized levy payments or long-run operating losses.
PDF 파일 10, 11, 13쪽PDF pages 10, 11, 13
중형 플랫폼에서 더 큰 음의 반응Larger negative responses among medium platforms
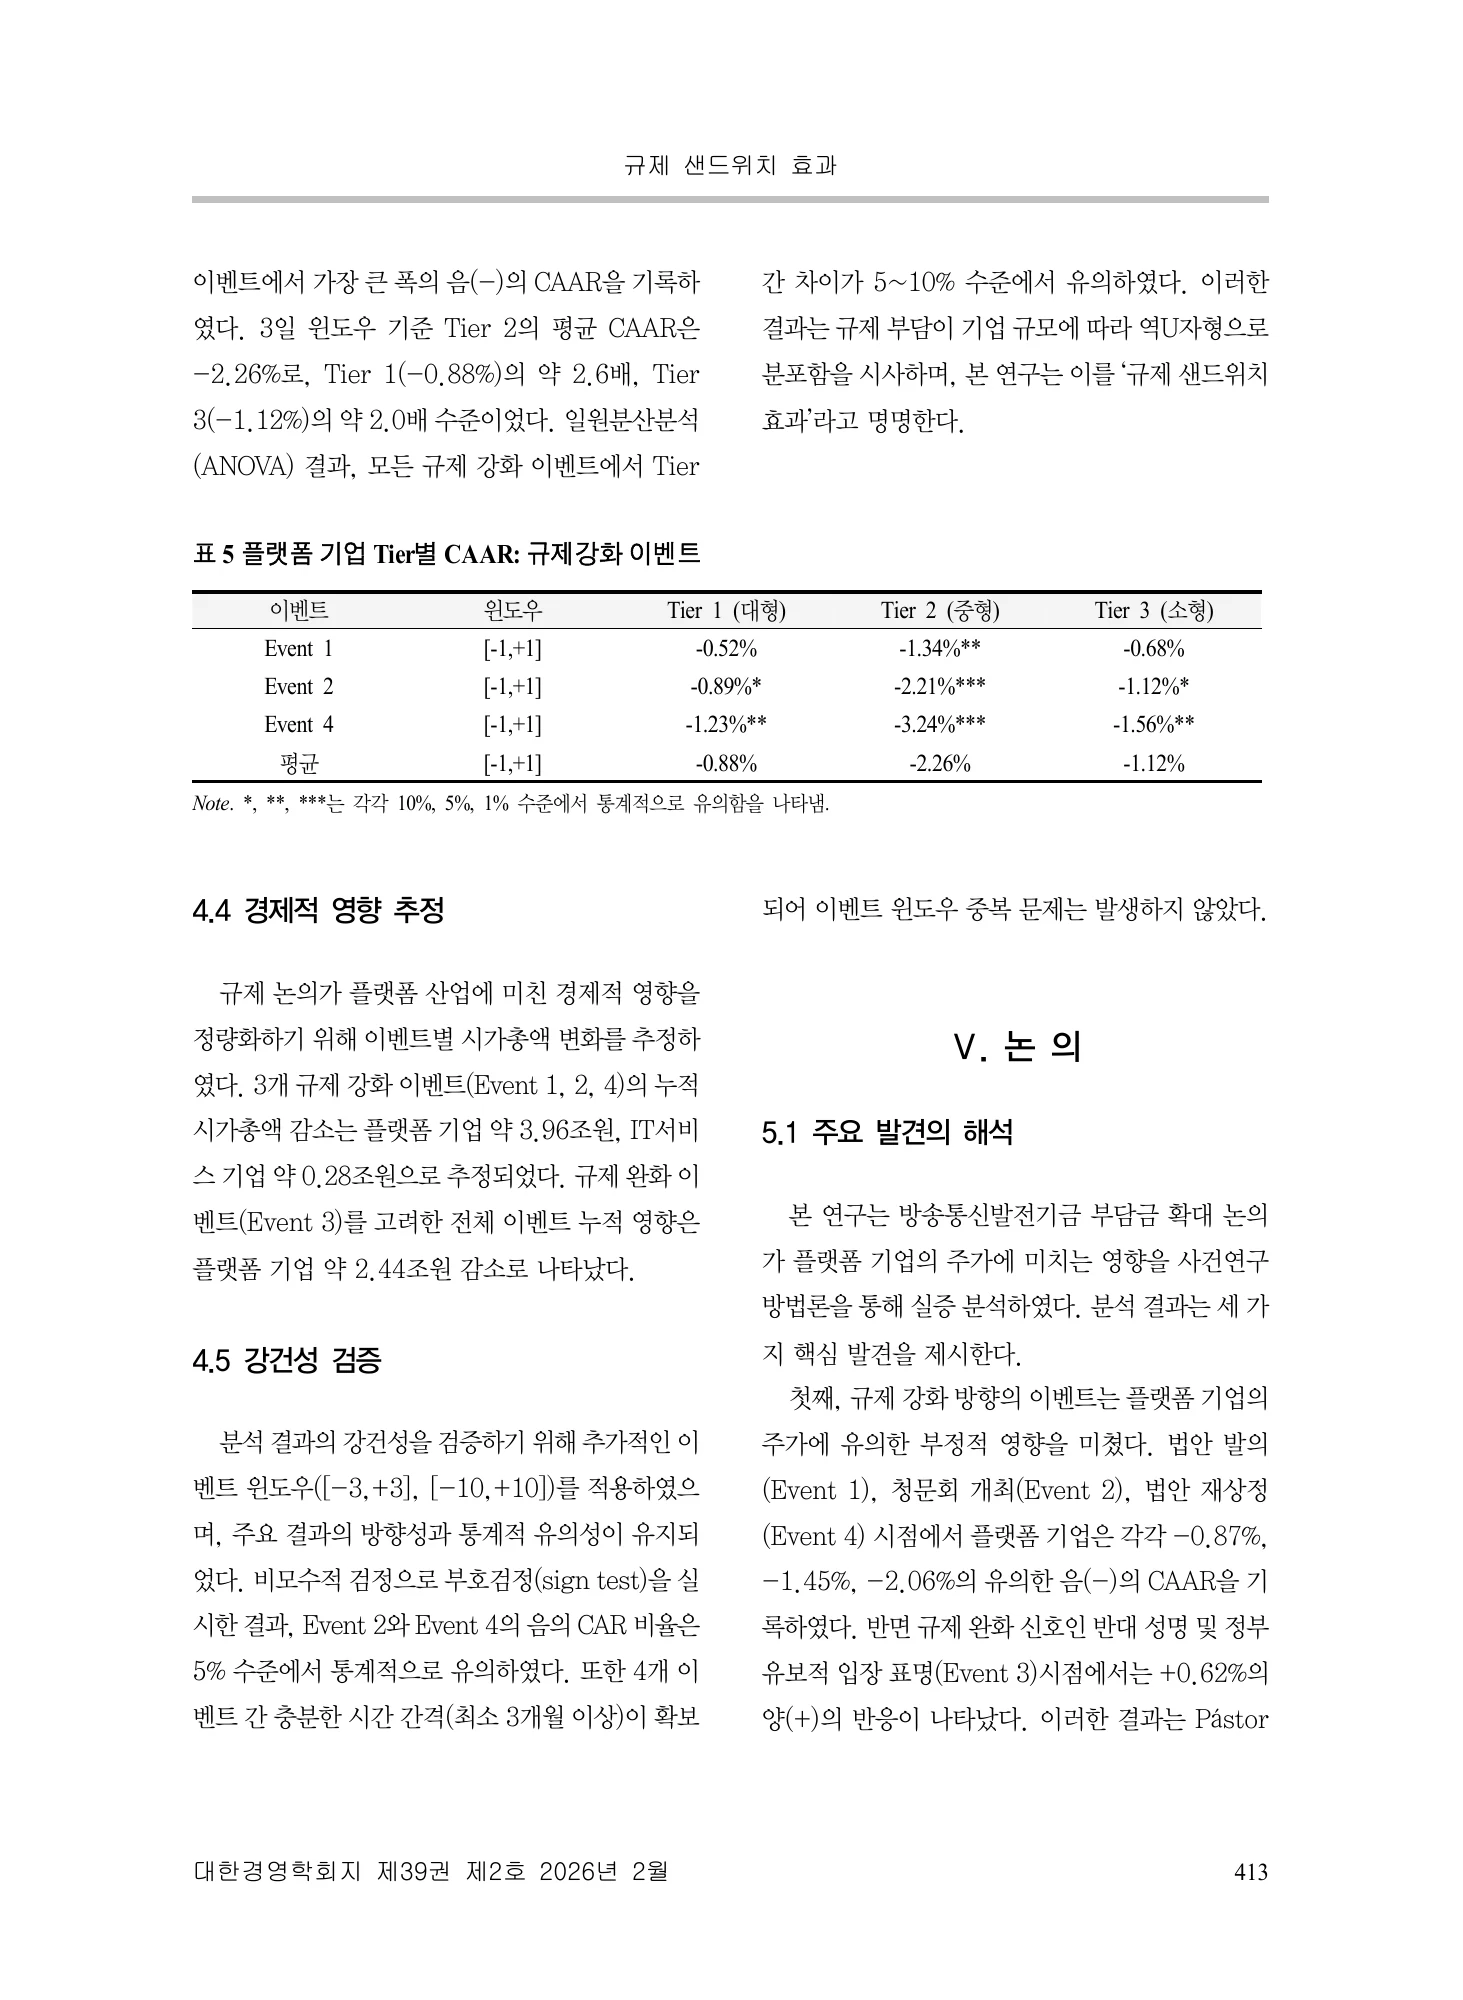
표 4의 3일 CAAR은 규제 강화 이벤트에서 플랫폼이 각각 -0.87%, -1.45%, -2.06%이며, IT서비스와의 차이는 -1.10, -0.93, -1.22%포인트다. 완화 신호에는 플랫폼이 +0.62%를 보였다. 표 5에서는 중형의 강화 이벤트 평균이 -2.26%로 대형 -0.88%, 소형 -1.12%보다 음의 폭이 크다. 이 패턴이 논문의 핵심 실증 결과다. 비용 흡수력이나 협상력 부족이라는 메커니즘 자체를 이 수치가 직접 검증하는 것은 아니다.
Table 4 reports three-day platform CAARs of −0.87%, −1.45%, and −2.06% for tightening events, versus +0.62% for the easing signal. Corresponding tightening-event gaps against IT services are −1.10, −0.93, and −1.22 percentage points. Table 5 gives an average of −2.26% for medium platforms, compared with −0.88% for large and −1.12% for small platforms. These are the reported patterns supporting the sandwich interpretation.
PDF 파일 12, 13쪽PDF pages 12, 13
핵심 결과를 표로 읽기Read the key results in tables
| 이벤트Event | 대형Large | 중형Medium | 소형Small |
|---|---|---|---|
| Event 1 | -0.52% | -1.34%** | -0.68% |
| Event 2 | -0.89%* | -2.21%*** | -1.12%* |
| Event 4 | -1.23%** | -3.24%*** | -1.56%** |
| 평균Mean | -0.88% | -2.26% | -1.12% |
원문 표 5 재구성. 윈도우 [-1,+1]. *, **, ***는 각각 10%, 5%, 1% 유의수준이다. 평균의 별표는 원문에 없다. 실제 납부액이나 사회적 손실을 나타내는 표가 아니다.Adapted from Table 5, window [−1,+1]. *, **, *** denote 10%, 5%, and 1% significance. The source gives no stars for the mean. These are valuation responses, not levy payments or social losses.
원문 표 5Original Table 5 · PDF 파일 13쪽PDF page 13
원문의 핵심 표·그래프Key tables & figures in the source
표·그림이 수록된 원문 페이지입니다. 이미지를 누르면 확대할 수 있습니다.Original pages containing the selected tables or figures. Select an image to enlarge it.
표 4: 이벤트별 누적평균비정상수익률Table 4: Event-level CAAR
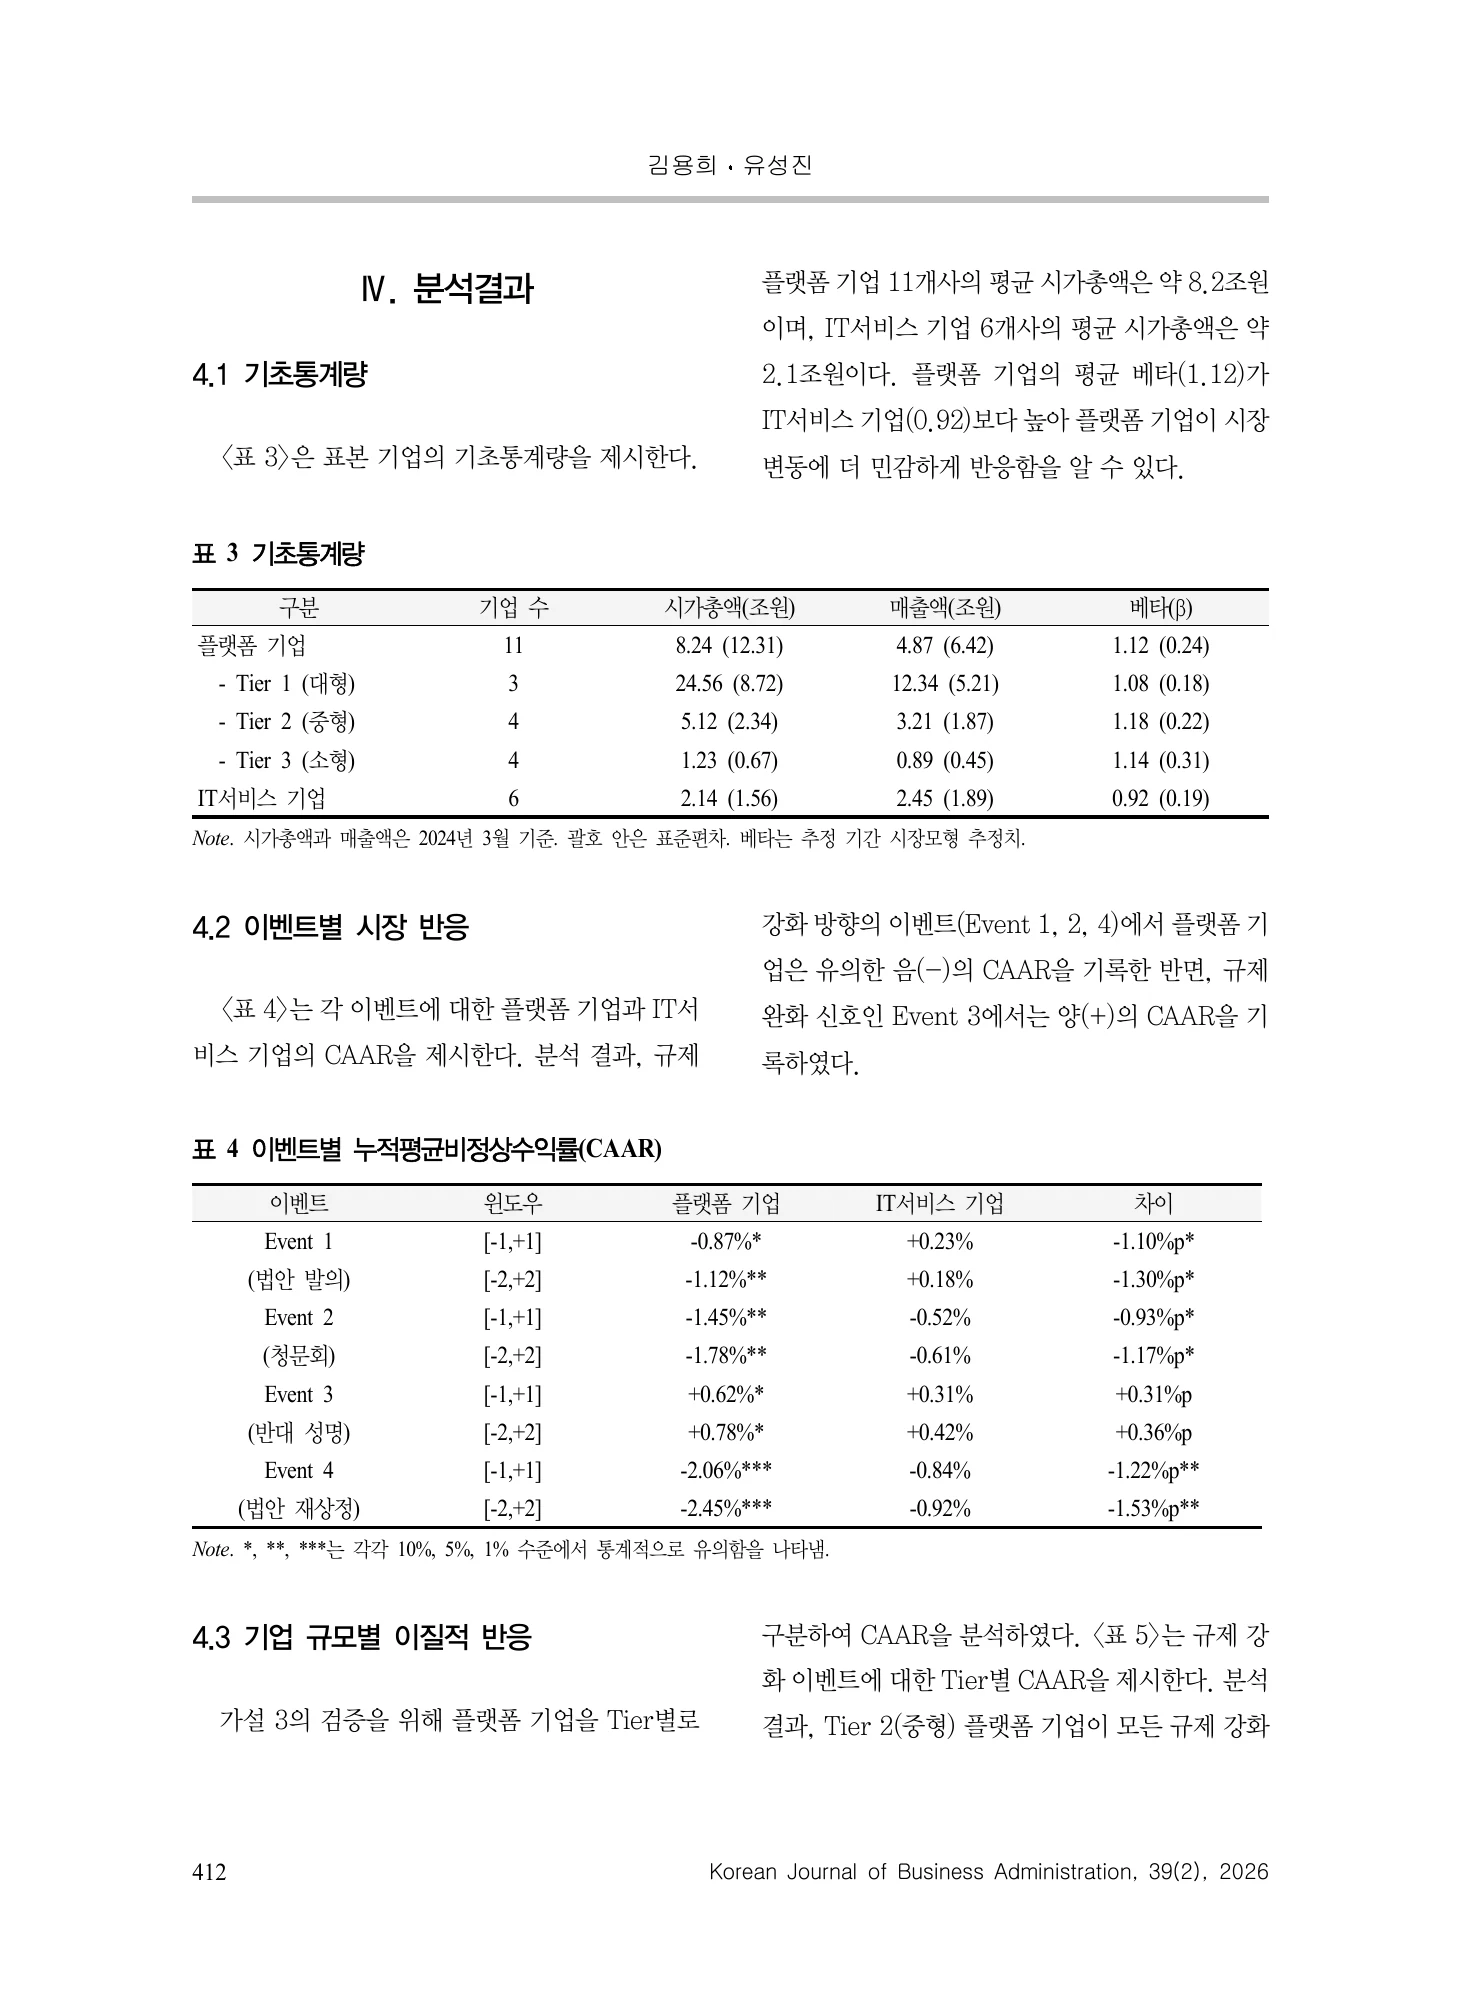
표 5: 플랫폼 규모별 CAARTable 5: CAAR by platform tier
규제 대상 여부와 대응 능력을 함께 고려Consider exposure and capacity together
저자들은 획일적인 규모 기준보다 차등적 부담, 전환기간, 예측 가능한 정책 소통을 검토해야 한다고 제안한다. 기업에는 초기 논의 참여와 규제 대응 역량 확충을 권한다. 이는 추정된 시장 반응에서 도출한 정책적 해석이며, 규제의 공익적 편익과 사회적 비용을 모두 계산해 특정 정책의 순편익을 판정한 결과는 아니다. 주가 하락을 소비자 후생 감소나 실제 현금 손실과 동일시해서는 안 된다.
The authors recommend predictable communication, transitional arrangements, and attention to heterogeneous compliance capacity. For managers, they emphasize early participation and response capabilities. These are policy implications drawn from valuation patterns. The analysis does not calculate the full social benefits and costs of regulation, so stock-price declines should not be equated with consumer-welfare losses or realized cash losses.
PDF 파일 15, 16쪽PDF pages 15, 16
작은 표본과 원문 내부 표기의 유의점Small sample and source inconsistencies
저자들은 17개 국내 상장사라는 표본 범위, 단기 주가 중심의 분석, 메커니즘 미검증과 다른 규제로의 일반화 한계를 인정한다. 다른 동시기 뉴스의 영향을 완전히 배제한 실험도 아니다. 원문에서는 소형을 시가총액 1조원 미만으로 정의하지만 표 3의 소형 평균은 1.23조원으로 표기돼 원자료 대조가 필요하다. 또한 서지 머리는 401~421쪽이나 제공 PDF는 401~420쪽의 20페이지다. 아래 인용 쪽수는 인쇄 쪽수가 아닌 실제 PDF 페이지를 따른다.
The authors acknowledge the small listed-firm sample, short horizon, untested mechanisms, and limited generalizability. Contemporaneous firm news remains a concern. A source inconsistency also warrants checking: small firms are defined as below KRW1 trillion, but Table 3 reports their mean as KRW1.23 trillion. The supplied PDF has twenty pages numbered 401–420, although the bibliographic header states 401–421. References here use physical PDF pages.
PDF 파일 10, 12, 16, 20쪽PDF pages 10, 12, 16, 20
근거 쪽: Evidence pages: 1, 6, 7, 8, 9, 10, 11, 12, 13, 14, 15, 16, 19, 20 · PDF 파일 기준, 인쇄 쪽수와 다를 수 있습니다. · PDF file pagination may differ from printed page numbers. 원문 출처 ↗Source ↗
원문 이미지 보기 · 1장View original document images · 1
서지 정보Bibliographic information
- 학술지Journal
- 대한경영학회지
- 권(호)Volume (issue)
- 39(2)
- 쪽Pages
- 401–421
- 게재Published
- 2026-02-28
- 색인Indexing
-
- KCI (저자 실적 기록 기준)(per the author's records)
인용하기Cite APA · BibTeX
APA
김용희, 유성진 (2026). 규제 샌드위치 효과: 플랫폼 규제 논의에 대한 기업 규모별 시장 반응. 대한경영학회지, 39(2), 401–421. https://doi.org/10.18032/kaaba.2026.39.2.401
BibTeX
@article{kci-2026-regulatory-sandwich,
  author = {김용희 and 유성진},
  title = {규제 샌드위치 효과: 플랫폼 규제 논의에 대한 기업 규모별 시장 반응},
  journal = {대한경영학회지},
  year = {2026},
  volume = {39},
  number = {2},
  pages = {401--421},
  doi = {10.18032/kaaba.2026.39.2.401}
}