정책·산업 자료 · 원문 해설Policy & industry material · Source-based guide
미디어환경 변화에 따른 방송통신발전기금 분담금 산정 및 부과체계 개선방안에 관한 연구Reforming Broadcasting and Telecommunications Fund Assessment and Levies
김용희의 원문 역할: 총괄책임자Yonghee Kim’s documented role: Principal investigator
연구 내용Overview
미디어 환경 변화에 따른 방송통신발전기금 재원과 사업자별 분담 구조를 검토하고, 해외의 투자·부담금·조세 체계를 비교하여 산정 및 부과체계의 개선 방향을 논의한 정책연구다. 2023년의 제도와 자료를 검토한 기록이다.
A policy study of fund revenues and contributions across media businesses, comparing overseas investment, levy and tax frameworks to consider assessment reform. It records the policy and evidence context of 2023.
원보고서의 문제의식·분석·제안을 정리한 해설입니다. 수치는 표시한 표와 쪽을 기준으로 읽습니다. 아래 표는 핵심 항목을 웹에서 읽도록 재구성했고, 원문 표·그림이 있는 페이지를 함께 제공합니다.This reading guide explains the report’s questions, analyses, and proposals in new wording. Tables below re-present selected source results for web reading, alongside images of the relevant original pages.
핵심부터 읽기Start with the main findings
- 이 연구는 재원을 얼마나 더 걷을지와 누가 어떤 기준으로 부담할지를 구분한다. 광고 매출 중심 기준이 방송사업 매출 다변화를 놓치는 문제, 허가·승인·등록별 책무의 차이, 신규 편입 사업자의 부담 능력을 하나의 틀 안에서 검토한 연구다.The study distinguishes revenue volume from who should pay and on which base. It connects advertising-based assessment, diversified broadcasting income, different public duties and the capacity of newly included businesses.PDF 파일 37, 121, 126, 130, 136쪽PDF pages 37, 121, 126, 130, 136
- 2022년 기금 총수입 14,167억원 중 방송사 분담금은 1,926억원이다. 주파수 수입 감소를 정부 내부수입과 여유자금 회수 증가가 일부 메운 구조여서 총계만으로 방송사업자의 부담 증가·감소를 설명할 수 없다.Broadcaster contributions account for KRW192.6 billion of 2022 total receipts of KRW1,416.7 billion. Falling spectrum receipts coexist with greater internal transfers and recovered surplus; the aggregate alone does not describe broadcaster burdens.PDF 파일 37쪽PDF page 37
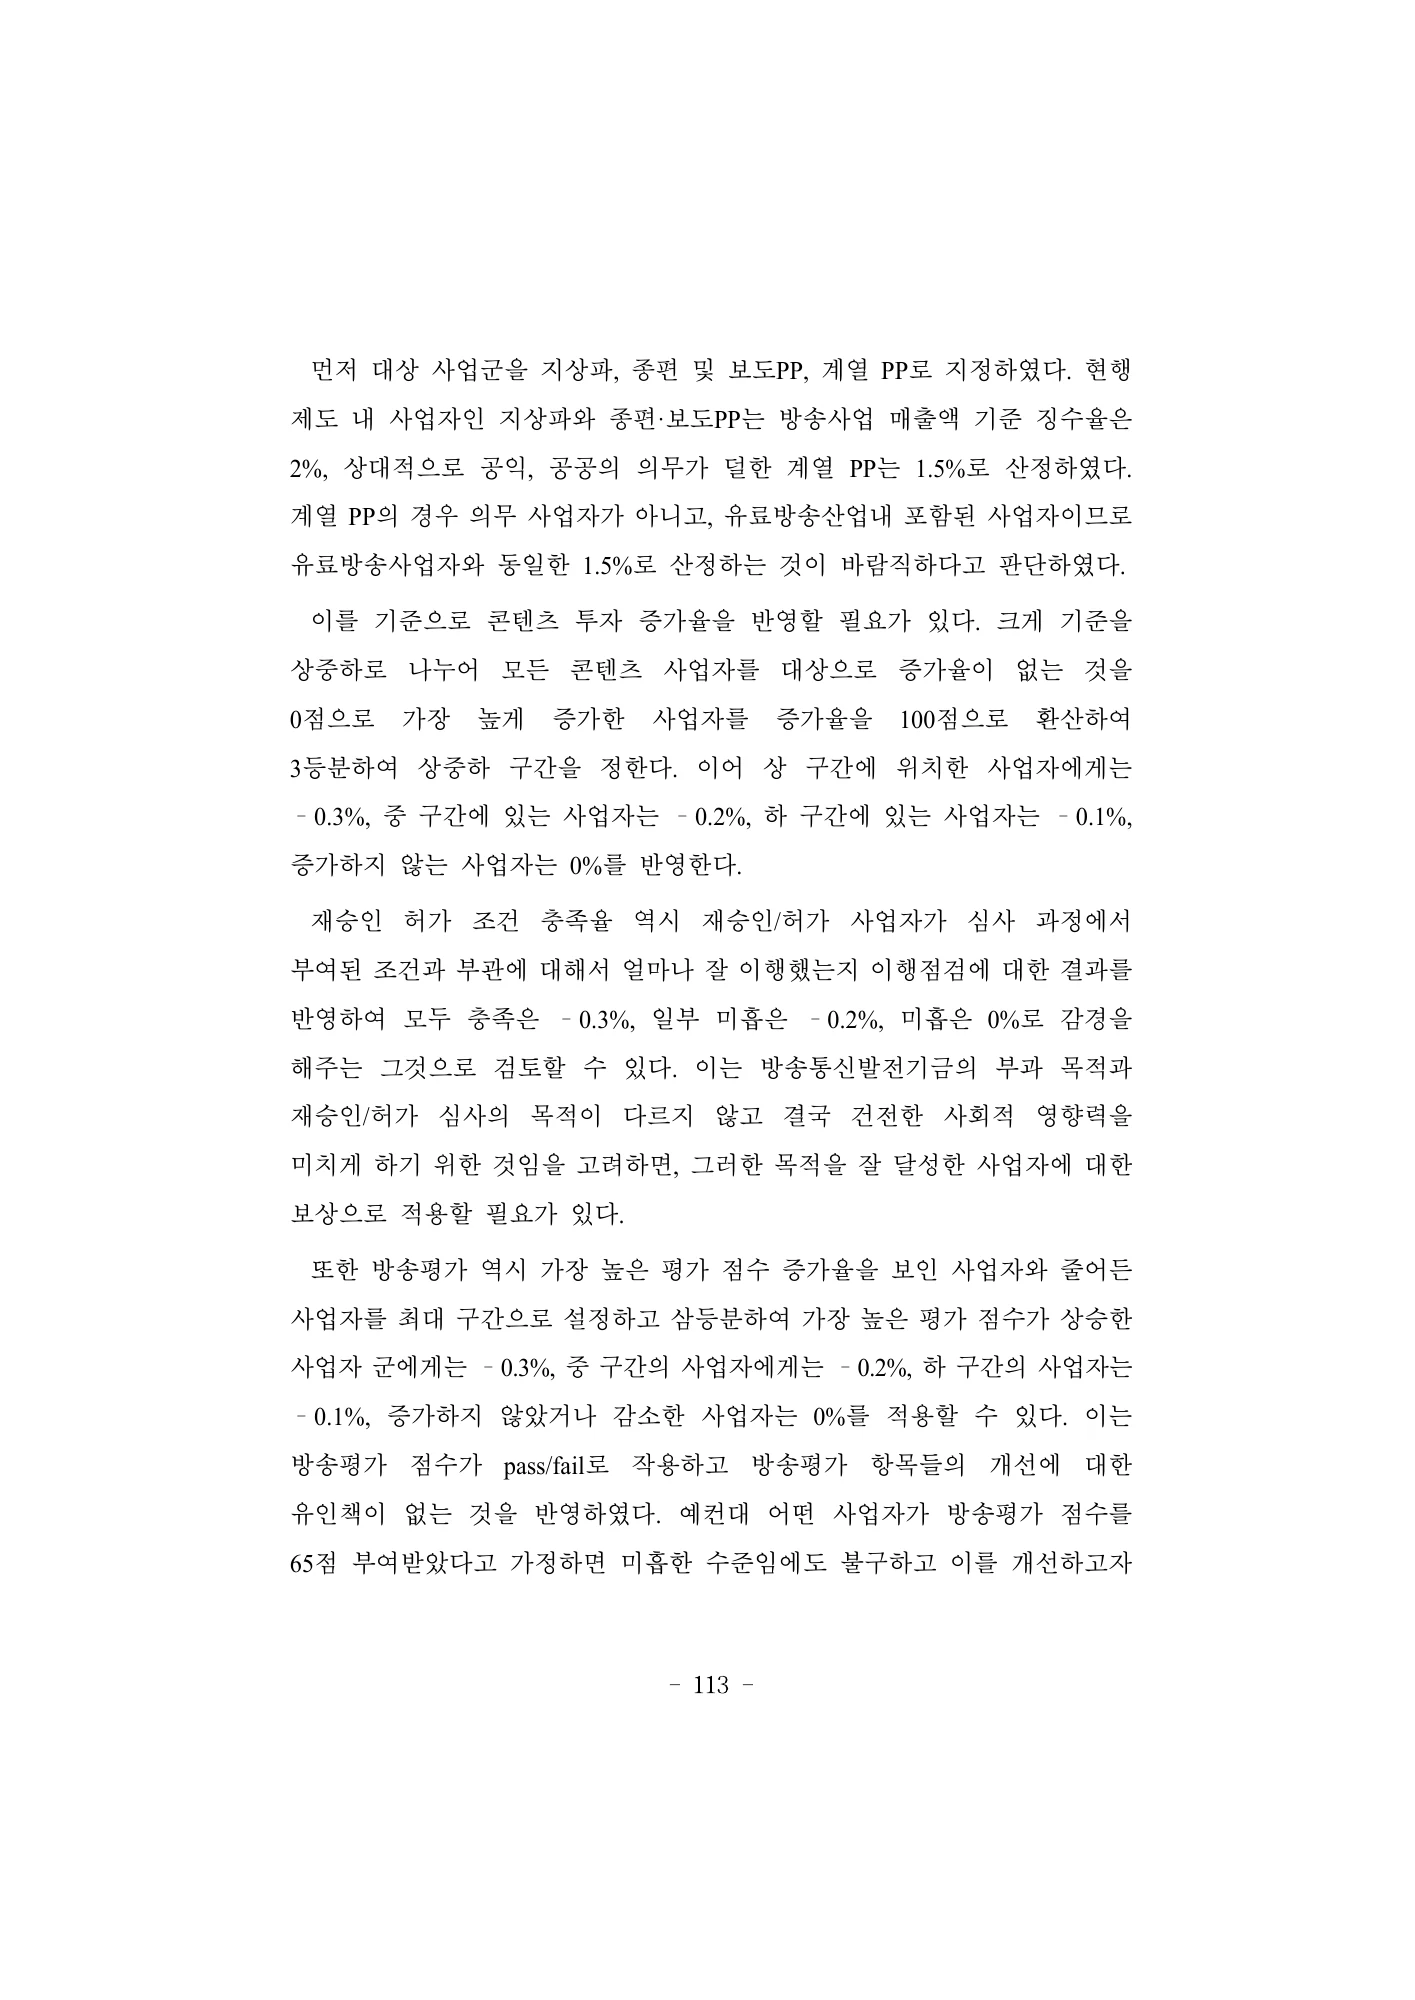
- 방송사업 매출을 바탕으로 기본율을 정하고 콘텐츠 투자·공적 책무 이행에 따라 조정하자는 안은 기존 경영성과 중심 감경과 다른 유인 구조다. 신규 사업자 초기율 0.5%라는 별도 단계안과 2%·1.5% 기본율 예시를 섞어 하나의 확정 부과표로 제시해서는 안 된다.The proposal links broadcasting-revenue bases to adjustments for investment and public responsibilities. This differs from financial-condition relief. The separate 0.5% phased-entry option must not be merged with the illustrative 2%/1.5% base-rate design as if one adopted schedule.PDF 파일 130, 136, 137, 138쪽PDF pages 130, 136, 137, 138
미디어 경쟁 변화에 맞는 부과 원칙Contribution principles for a changing media market
2023년 12월 제출된 연구는 방송통신발전기금의 납부 대상·기준·징수율이 OTT와 경쟁하는 시장에 적합한지 검토한다. 김용희가 총괄책임자로 명시되며 보고서는 연구자 견해이고 위원회의 공식 입장과 다를 수 있다고 밝힌다. 기존 사업자 부담 경감과 신규 사업자 편입, 공적 재원 확보와 헌법·통상상 정당성은 서로 긴장할 수 있다. 연구는 현황·시장 변화·이해관계자 의견·해외 비교·개정 예시를 연결하여 선택지와 선행 조건을 제시한다.
Submitted in December 2023, the study examines contribution liability, assessment bases, and rates as broadcasting competes with OTT. Yonghee Kim is named principal investigator; the report disclaims official commission endorsement. Existing burdens, new contributors, financing needs, and legal justification can conflict. The study connects financial records, market change, stakeholder views, overseas comparisons, and draft reforms.
PDF 파일 2, 3, 4, 5, 6, 18, 19쪽PDF pages 2, 3, 4, 5, 6, 18, 19
기금 전체 수입과 방송사 분담금을 구별Separate total fund revenue from broadcaster contributions
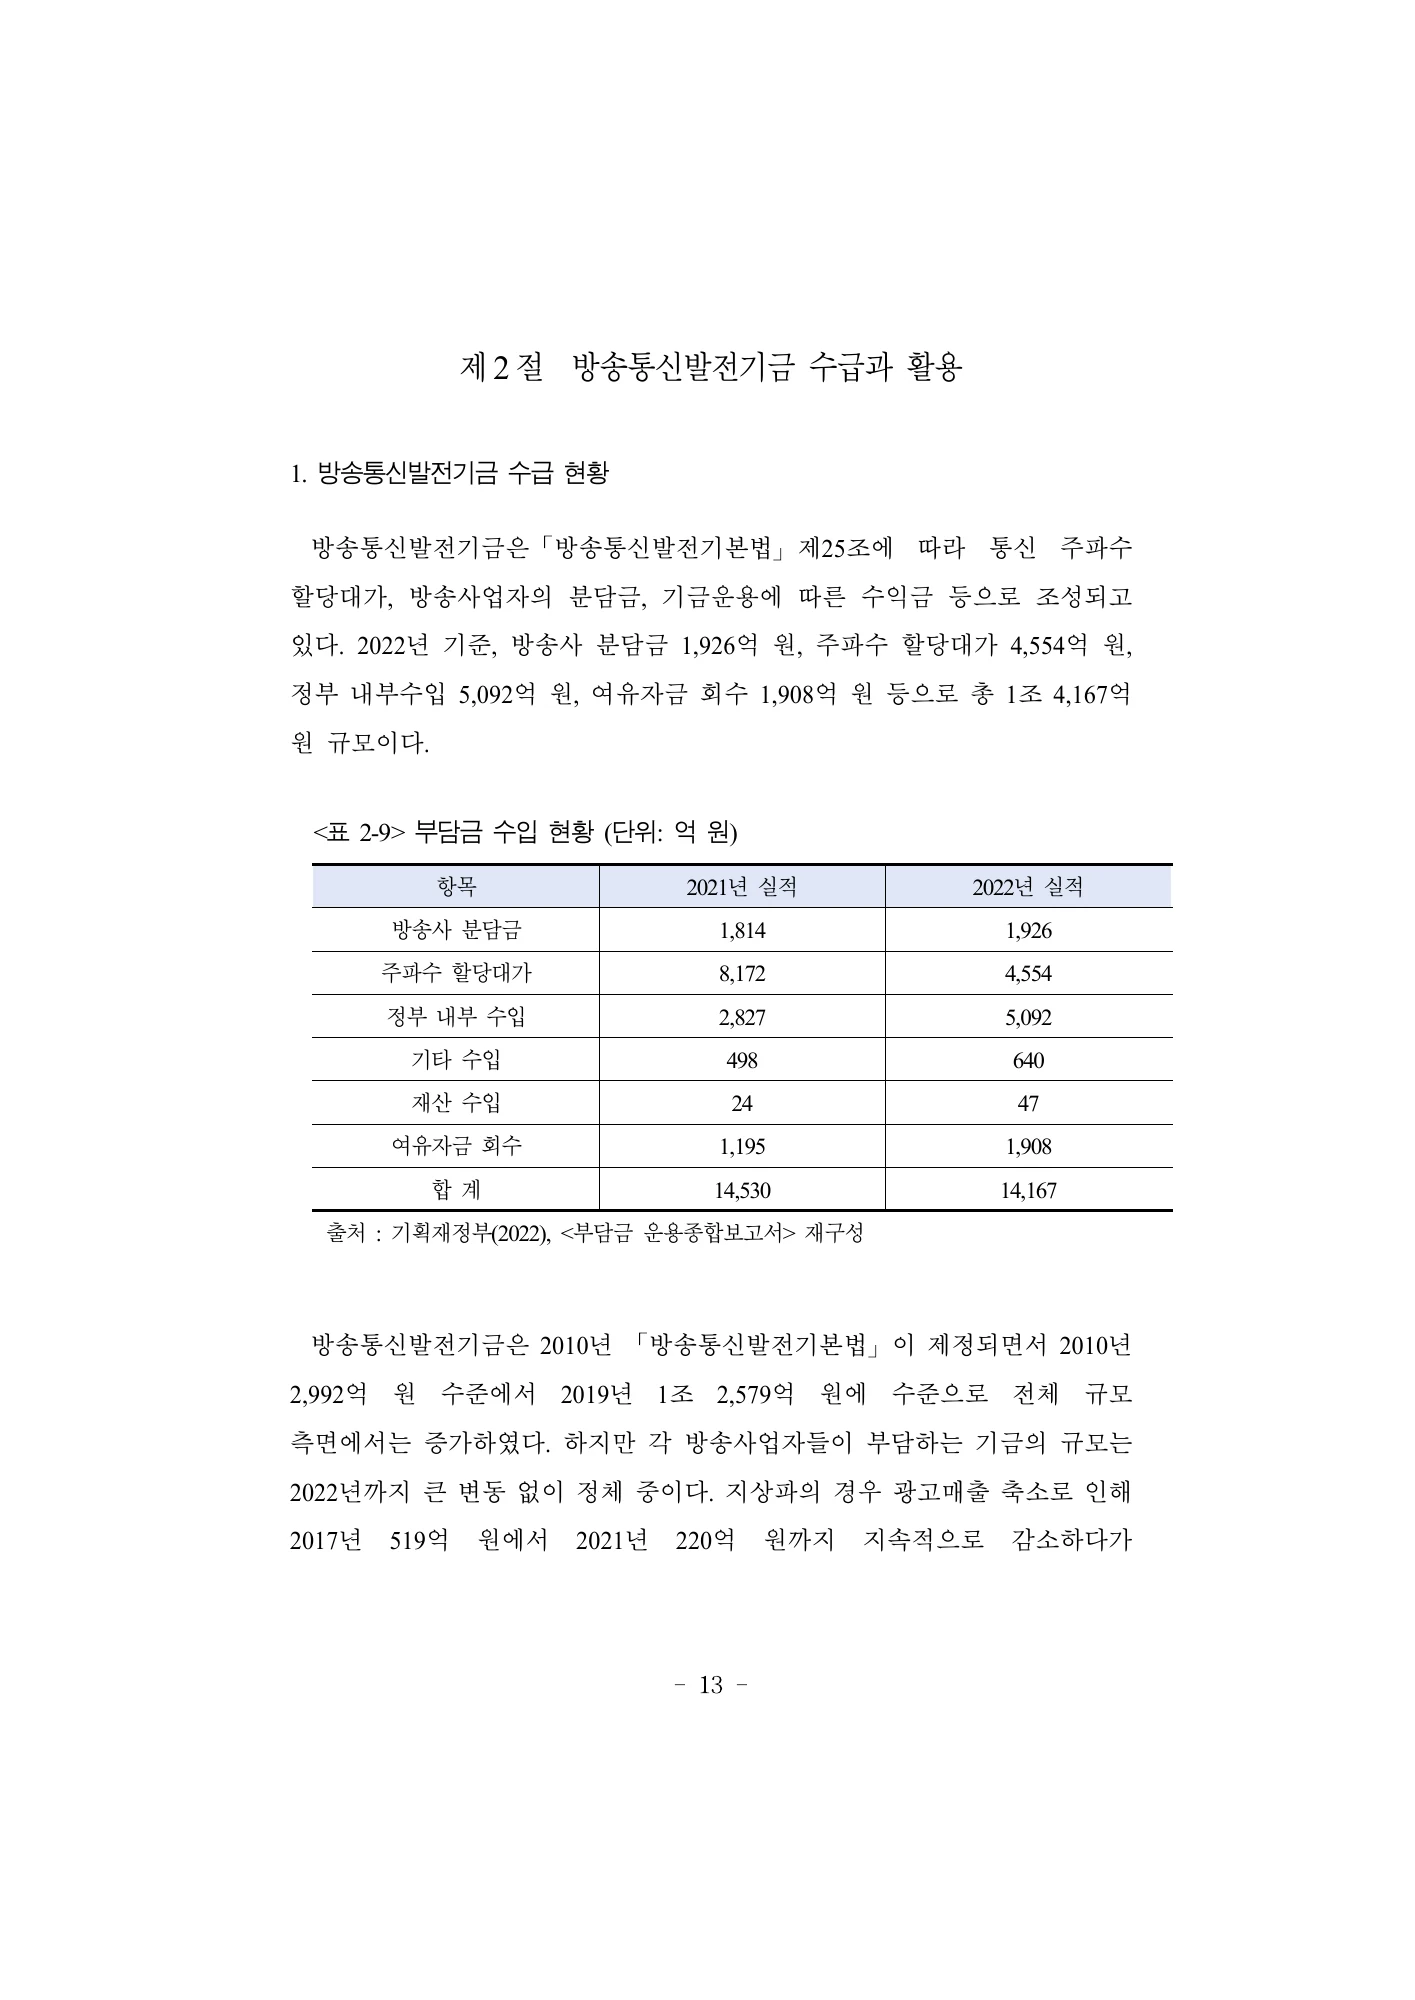
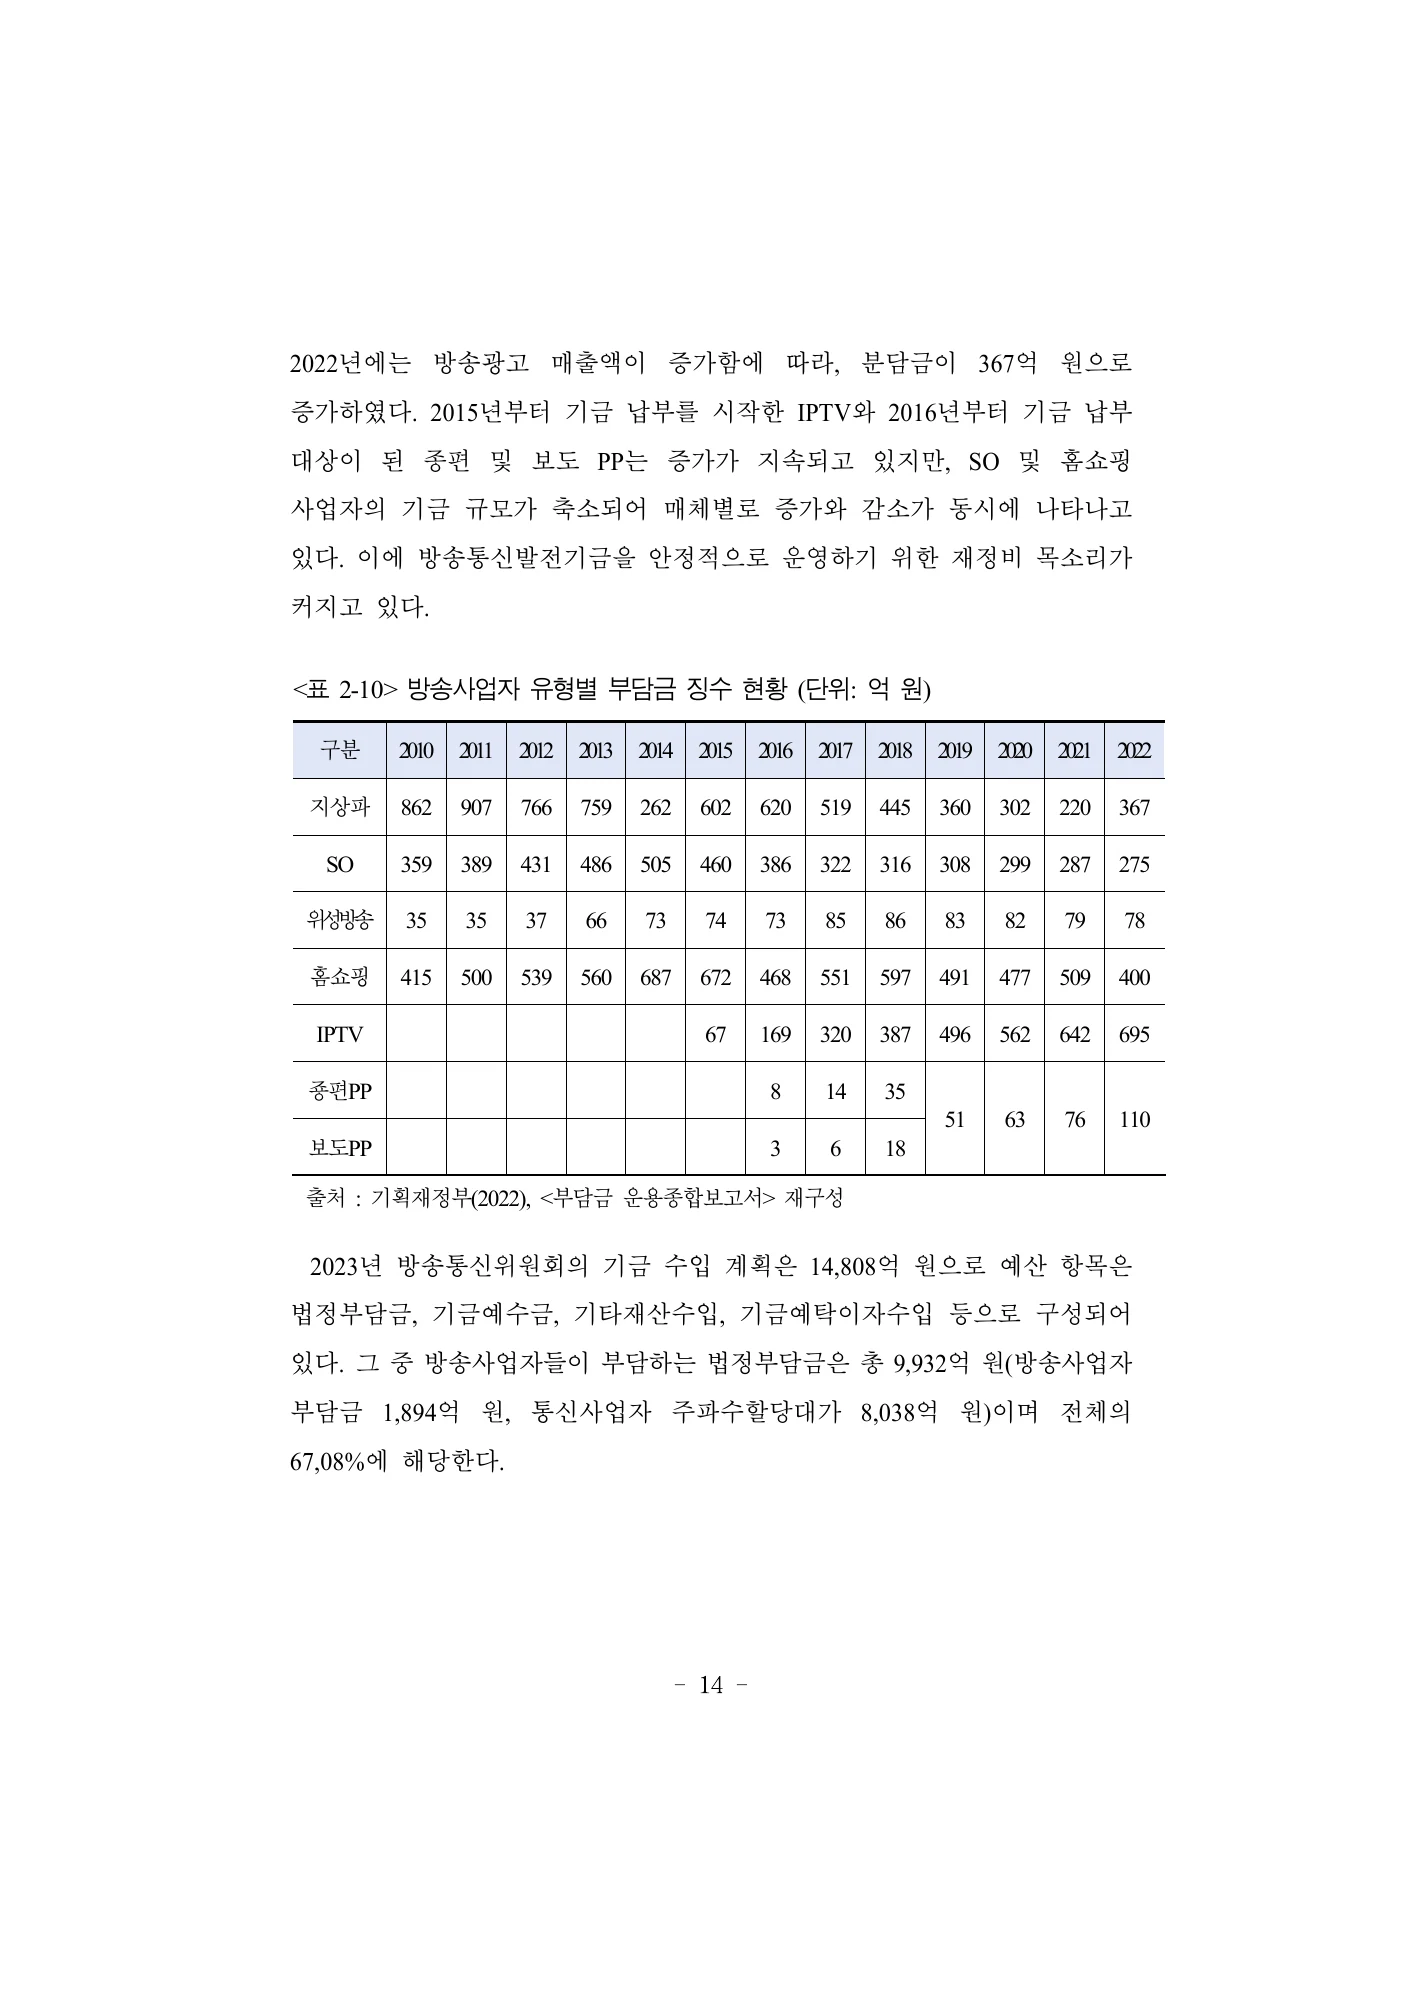
2022년 보고 총수입은 14,167억 원이고 그중 방송사 분담금은 1,926억 원, 주파수 할당대가는 4,554억 원이다. 정부 내부수입·여유자금 회수 등도 포함되므로 전체 규모를 방송사 납부액으로 표현하면 안 된다. 유형별로 지상파·SO·홈쇼핑과 IPTV 등의 추이가 다르다. 지출은 콘텐츠 산업 육성뿐 아니라 R&D·인프라·공공성·접근성 지원을 포함한다. 표의 연간 실적과 2023년 운용 계획도 서로 다른 자료로 구분한다.
Reported 2022 total receipts are KRW 1,416.7 billion, including KRW 192.6 billion in broadcaster contributions and KRW 455.4 billion in spectrum allocation payments. Internal transfers and recovered funds also matter. Types of broadcasters show different trends. Uses extend beyond content to R&D, infrastructure, public purpose, and access. Actual accounts and 2023 plans must remain distinct.
PDF 파일 37, 38, 39, 43, 44쪽PDF pages 37, 38, 39, 43, 44
광고 중심 기준과 다변화된 수익 구조Advertising-based assessment and diversified revenues
시장 장은 OTT 진입, 기기·시청 행태 변화, 방송·광고 매출 이동을 검토한다. 이해관계자는 광고매출·방송서비스매출·영업이익으로 나뉜 기준, 매출 구간의 불연속, 조정계수·감경의 설명과 예측 가능성, 납부와 지원의 관계를 문제로 제기했다. 이는 사업자·전문가 의견이지 모든 업계의 합의나 위법 판정은 아니다. 지원 수혜가 특정 납부 회사에 직접 돌아오는지와 공적 과제에 집단적 효용이 있는지도 구별해야 한다.
The market review covers OTT entry, viewing changes, and revenue shifts. Stakeholders question differing revenue and profit bases, discontinuous brackets, adjustment factors, predictability, and who benefits from spending. These are reported perspectives, not unanimous industry agreement or findings of illegality. Direct support to a payer differs from collective benefit from a public programme.
PDF 파일 12, 13, 58, 59, 60, 62, 63쪽PDF pages 12, 13, 58, 59, 60, 62, 63
투자 의무·기금·조세·행정비용의 차이Distinguish investment, funds, taxation, and administration
해외 비교는 EU AVMSD의 재정적 기여, OECD 디지털 조세 논의, 프랑스 CNC와 직접 투자, 영국 행정비용 조달, 독일 영화부담금, 캐나다 및 스페인·이탈리아·그리스·덴마크·호주를 다룬다. 직접 제작·권리 취득과 기금 납부, 일반 디지털세, 면허 행정비용은 목적·수혜·과세 기반이 같지 않다. 국가별 금액·시행 예정일은 2023년 당시 자료이며 현재 제도로 제시하지 않는다. 특히 법안·정치적 합의·시행 제도를 한 단계로 묶지 않아야 한다.
The international chapter covers AVMSD contributions, OECD tax debates, French and German film financing, UK regulatory fees, and Canadian and other models. Direct production investment, fund payments, digital taxes, and administrative fees differ in purpose and base. Historical proposals, political agreements, and implemented systems must be separated; the 2023 descriptions are not current legal guidance.
PDF 파일 64, 71, 80, 87, 90, 94, 101, 103, 104, 106, 107, 108, 109쪽PDF pages 64, 71, 80, 87, 90, 94, 101, 103, 104, 106, 107, 108, 109
초과이윤 환수에서 공적 기여로의 재정립Reframing public contribution beyond monopoly rents
저자는 전파·배타적 사업권의 희소성이 약해진 상황에서 초과이윤 환수 논리만으로 부과체계를 유지하기 어렵다고 보고, 방송통신 발전이라는 공적 과제와 납부집단의 관계를 다시 정립할 것을 제안한다. 집단 동질성·객관적 근접성·집단 책임·효용 등 특별부담금 논의가 중요하다. 단순히 수익이 크거나 영상 서비스를 제공한다는 사실만으로 모든 사업자 부과가 자동 정당화되는 것은 아니며, 목적·재원 사용·대상 선정의 연결 근거가 필요하다.
The authors propose moving beyond monopoly-rent reasoning toward a clearly justified public contribution. The relationship between payers and the financed public task remains central, including group responsibility and benefit. Large revenue or video provision alone does not automatically justify liability. Purpose, spending, and the selected group require a coherent evidential and legal connection.
PDF 파일 113, 114, 115, 116쪽PDF pages 113, 114, 115, 116
대상 확대와 기준·율 개선의 별도 선택지Separate choices on liability, bases, and rates
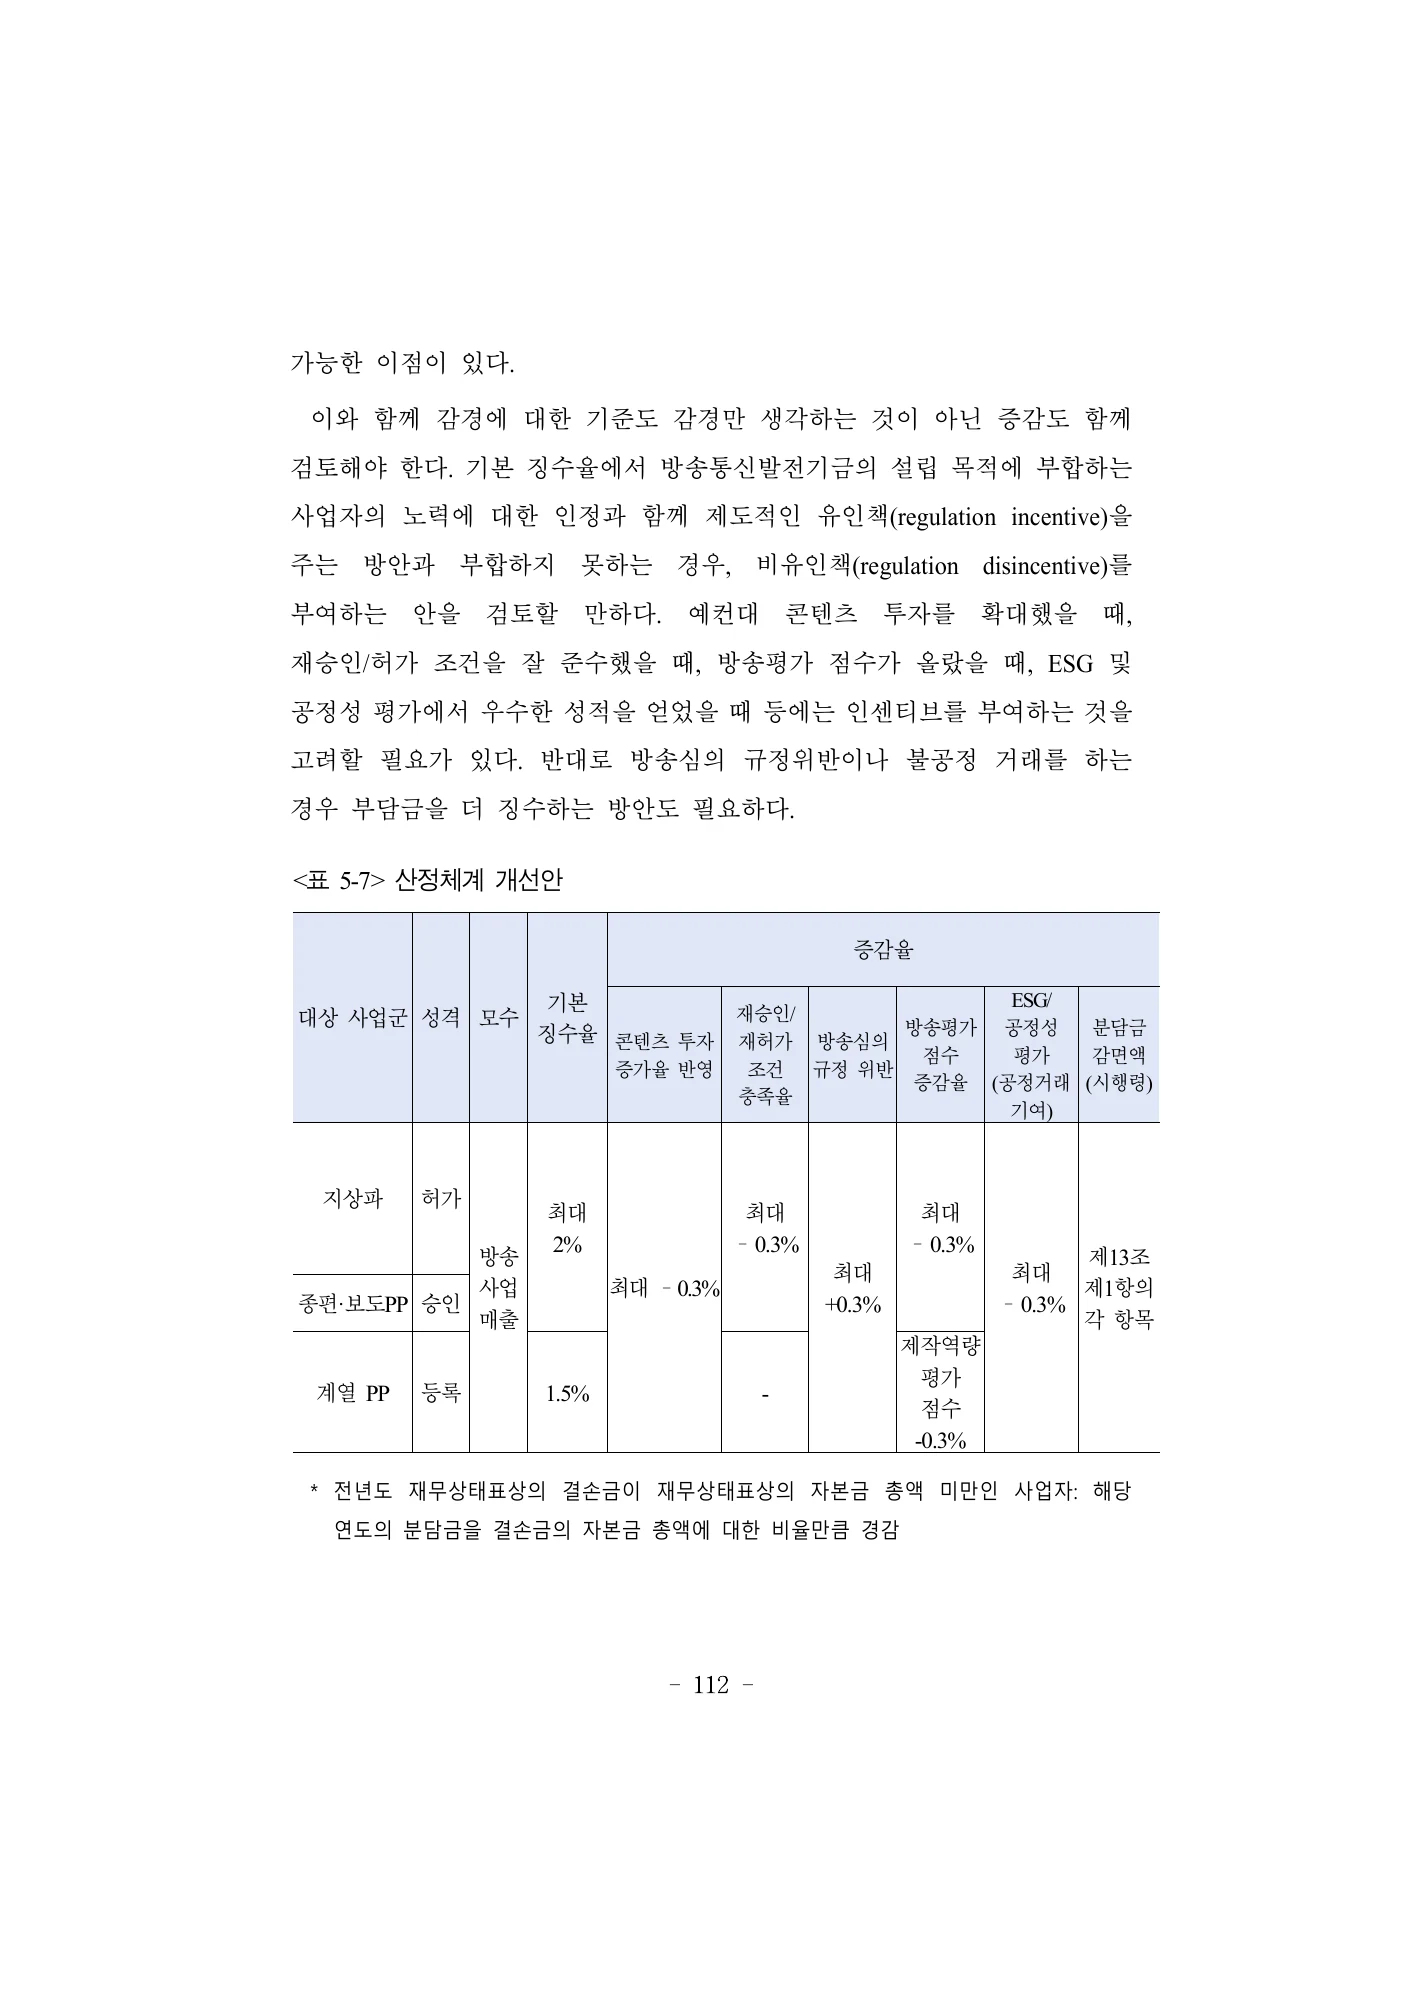
정책안은 MPP·일정 규모 OTT 등 편입을 위한 법률 개정, 자료제출과 규모 기준, 손실 사업자 면제·감경, 단계적 초기율을 검토한다. 다른 산정안은 방송광고 매출 대신 방송사업 매출을 바탕으로 기본율과 콘텐츠 투자·평가·공정거래 등의 증감을 결합한다. 원문의 2%·1.5% 기본율과 최대 0.3%p 조정은 제안 예시다. 초기 편입 후 0.5%부터 단계적으로 올리는 방안도 별도 검토안이므로 두 체계를 하나의 확정 제도로 합치지 않는다.
Options cover statutory expansion to MPPs or larger OTT services, reporting, size thresholds, loss relief, and phased initial rates. A separate assessment proposal uses broadcasting-service revenue and adjustments for investment and public responsibilities. Proposed base rates of 2% and 1.5% and adjustments are illustrative. A phased 0.5% entry option is a different design, not part of one adopted regime.
PDF 파일 118, 119, 120, 123, 127, 128, 130, 135, 136, 137, 138쪽PDF pages 118, 119, 120, 123, 127, 128, 130, 135, 136, 137, 138
단기 개정과 장기 수평 규제의 연결Connect near-term amendments with longer-term horizontal regulation
단기적으로 법·시행령·소관 고시의 역할을 구분하고, 납부 대상과 산정 기준을 검증 가능하게 만들며, 신규 납부집단과 기금 용도의 정합성을 검토한다. 장기적으로는 시청각미디어 일반법과 콘텐츠 진흥 중심의 재원 체계를 논의한다. 재검토기한 단축만이 유일한 해법은 아니며 원문은 기한 내에도 고시 개정이 가능하다고 본다. ESG 등 평가를 감경과 연결하려면 공개·제3자 검증과 객관적 기준이 필요하다는 실행 조건도 제시한다.
Near-term work distinguishes statutes, decrees, and ministry notices; makes liability and assessment verifiable; and aligns uses with the payer group. Longer-term horizontal audiovisual regulation offers another route. Shortening a notice-review period is not the sole solution. Linking contributions to ESG or other evaluations requires disclosure, independent verification, and defensible criteria.
PDF 파일 132, 134, 135, 136, 138쪽PDF pages 132, 134, 135, 136, 138
형평성·이중부담·국제 집행의 선행 검토Equity, duplicate burdens, and cross-border enforcement
마지막 장은 규모 기준이 사실상 특정 회사만 겨냥하는 효과, 계열 PP에 대한 배타적 사업권 이익의 입증, 영업 자유와 비례성, 이중부과 문제를 별도로 검토한다. 글로벌 OTT는 국내 매출 파악·집행 가능성과 FTA 내국민 대우 등 통상 쟁점이 남는다. 원문은 가능한 법리와 위험을 함께 제시하므로 합헌·통상 적합이 확정되었다고 표현하지 않는다. 실제 제도 도입 전 영향 분석, 자료 기준, 이해관계자 협의와 국제 조정이 필요하다는 조건으로 읽는다.
The final analysis considers company-specific threshold effects, evidence of affiliated-channel benefits, proportionality, business freedom, and duplicate burdens. Domestic revenue measurement, enforcement, and trade obligations complicate global OTT inclusion. The report discusses arguments and risks; it does not establish constitutional or treaty compliance. Implementation requires evidence, consultation, and international coordination.
PDF 파일 139, 144, 145, 146, 147, 148, 149, 150, 151, 152, 153, 154, 155, 156, 157쪽PDF pages 139, 144, 145, 146, 147, 148, 149, 150, 151, 152, 153, 154, 155, 156, 157
기금 총액과 부담금 기반이 다른 이유Why fund totals differ from the levy base
2021→2022년 주파수 할당대가는 8,172→4,554억원으로 크게 줄었지만 방송사 분담금은 1,814→1,926억원으로 늘었다. 정부 내부수입은 2,827→5,092억원, 여유자금 회수는 1,195→1,908억원이다. 총수입이 14,530→14,167억원으로 소폭 줄었다는 사실 안에 서로 반대 방향의 재원이 섞여 있다는 점이 수입 안정성 논의의 출발점이다.
Spectrum receipts fall from KRW817.2 to 455.4 billion, while broadcaster contributions rise from KRW181.4 to 192.6 billion. Internal receipts increase from KRW282.7 to 509.2 billion and recovered surplus from KRW119.5 to 190.8 billion. The modest total decline conceals opposing component trends.
광고 매출에서 방송사업 매출로 모수를 바꾸면 세율의 숫자가 낮아도 부담액이 반드시 작아지는 것은 아니다. 비교에는 동일 사업자의 두 매출 범위와 감경 적용 순서가 필요하다. 원문은 공적 기여를 반영한 제도 재설계를 제안하지만, 공개된 예시만으로 모든 사업자의 실제 납부 증감을 계산하거나 총 재원 효과를 확정할 수는 없다.
A lower rate on broader broadcasting revenue need not reduce the payment. Comparison requires each firm’s two revenue definitions and the order of adjustments. The illustrative design does not provide enough information to establish every firm’s payment change or aggregate fiscal yield.
PDF 파일 37, 136, 137, 138쪽PDF pages 37, 136, 137, 138
책무 연동 감경에서 검증과 예측 가능성Verification and predictability in responsibility-linked relief
투자 증가율과 방송평가 개선을 상·중·하 구간으로 나누어 0.3·0.2·0.1%p 감경을 주는 예시는 절대 규모보다 개선 노력을 보상하는 구조다. 투자 증가가 없는 경우 0을 적용하고 허가·승인 조건 이행도 따로 본다. 이 설계를 실행하려면 비교 집단과 기준연도, 투자 인정 범위, 평가 점수의 산식·이의 절차를 먼저 정해야 한다.
Illustrative 0.3/0.2/0.1-percentage-point reductions rank investment and evaluation improvement into tiers. They reward change rather than absolute size and separately consider license-condition compliance. Implementation requires defined peer groups, base years, recognized spending, scoring and review procedures.
ESG와 공정거래 감경에는 공시와 제3자 검증이 필요하다고 명시한다. 심의 위반의 가산과 다른 평가 항목의 감경을 무조건 합산하면 법적 근거·중복평가·비례성 문제가 생길 수 있으므로 상세 규칙이 필요하다. 고시 재검토의 3년 주기 유지 제안도 징수율이 반드시 3년마다 바뀐다는 뜻이 아니라 자료 축적과 시장 대응의 균형에 대한 판단이다.
ESG and fair-trading adjustments require disclosure and third-party verification. Combining additions and reductions needs rules on authority, double counting and proportionality. The proposed three-year notice review balances evidence collection with market responsiveness; it does not mean rates must change every three years.
PDF 파일 133, 136, 137, 138쪽PDF pages 133, 136, 137, 138
핵심 결과를 표로 읽기Read the key results in tables
| 항목: 억 원Item: KRW 100 million | ||
|---|---|---|
| 방송사 분담금Broadcaster contributions | 1,814 | 1,926 |
| 주파수 할당대가Spectrum allocation receipts | 8,172 | 4,554 |
| 정부 내부 수입Government internal receipts | 2,827 | 5,092 |
| 기타 수입Other receipts | 498 | 640 |
| 재산 수입Property receipts | 24 | 47 |
| 여유자금 회수Recovered surplus funds | 1,195 | 1,908 |
| 합계Total | 14,530 | 14,167 |
원문 표 2-9. 총수입에는 정부 내부거래와 여유자금 회수가 포함되어 방송사 분담금·경상 세입과 같지 않다. 당시 실적이며 현재 규모가 아니다.Original Table 2-9. Totals include internal transfers and recovered surplus funds, not just broadcaster contributions or recurring revenue. Historical accounts, not current fund size.
이 표를 읽는 방법How to read this table
이 표의 합계는 조성 재원 전체이며 반복 가능한 영업 기반 세입과 회계상 내부거래가 섞여 있다. 방송사 분담금 두 행만 보면 증가하지만 전체 합계는 감소한다. 어느 행을 분모로 쓰는지 먼저 정하지 않고 산업의 기금 의존도나 부담 비중을 비교하면 의미가 달라진다.The total combines receipts of different recurrence and accounting character. Broadcaster contributions rise while the total falls. Dependence or burden ratios require an explicitly chosen denominator.
2021년 세부 행을 합하면 14,530억원, 2022년은 14,167억원으로 표의 총계와 맞는다. 다만 주파수 수입과 여유자금 회수의 변동은 방송 광고의 매출 동향과 동일하지 않다. 이 두 해의 집계로 장기 재정 안정성이나 사업자별 납부 능력을 직접 추정하지 않는다.The rows reconcile to the displayed totals of KRW1,453.0 and 1,416.7 billion. Spectrum and surplus movements are not broadcasting-advertising trends, and two aggregate years cannot establish long-term stability or individual ability to pay.
PDF 파일 37쪽PDF page 37
원문 표 2-9Original Table 2-9 · PDF 파일 37쪽PDF page 37
| 항목Element | 보고서 제안Proposal |
|---|---|
| 지상파·종편·보도 PP 기본율Base: terrestrial and general/news PP | 2.0% |
| 계열 PP 기본율Base: affiliated PP | 1.5% |
| 콘텐츠 투자 등 감경 예시Illustrative investment-related discount | 최대 -0.3%pUp to -0.3 percentage points |
| 심의 위반 가산 예시Illustrative review-violation addition | 최대 +0.3%pUp to +0.3 percentage points |
방송사업 매출 기준의 한 가지 제안 구조를 발췌했다. 별도로 논의된 신규 편입 초기율 0.5%와 혼합하지 않는다. 조정 기준·법적 근거·재정 영향의 후속 검토가 필요하다.Selected elements of one proposed broadcasting-revenue design. Do not combine with the separate 0.5% phased-entry option. Criteria, authority, and fiscal effects require further assessment.
이 표를 읽는 방법How to read this table
기본율 2.0%에서 최대 0.3%p를 빼면 해당 항목만 적용했을 때 1.7%가 되는 방식이다. 2.0%의 0.3%를 감면한다는 계산이 아니다. 여러 항목의 적용 순서와 한도는 별도 규칙이 필요하므로 선택된 행을 합쳐 개인 사업자의 최종율을 계산하지 않는다.Subtracting a 0.3-percentage-point adjustment from a 2.0% base gives 1.7% for that single adjustment; it is not 0.3% of 2.0%. Selected rows do not establish a final firm-level rate without ordering and caps.
1.5% 계열 PP 기본율과 새 편입 초기 0.5%는 같은 안의 동일 단계가 아니다. 원문은 최대 감경 시 평균 약 0.8–0.9%도 예상하지만 실제 전체 사업자 자료로 재현한 분포를 제시하지 않는다. 이 기대치를 세수 중립이나 확정 부담 완화로 부르지 않는다.The 1.5% affiliated-PP base and the separate 0.5% entry rate belong to distinct options. The source’s expected 0.8–0.9% after maximum relief is not a reproduced firm-level distribution and does not establish revenue neutrality or guaranteed relief.
PDF 파일 130, 136, 137, 138쪽PDF pages 130, 136, 137, 138
원문 표 5-7 및 설명Original Table 5-7 and discussion · PDF 파일 130, 136, 137쪽PDF pages 130, 136, 137
핵심 수치를 그래프로 읽기Read the key numbers visually
총액 14,167억원의 구성이다. 방송사 분담금과 기금 전체 수입은 같지 않다.Components of KRW1,416.7 billion; broadcaster contributions are not the whole fund.
단위: Unit: 억원KRW100m
표 2-9의 2022년 실적. 내부거래와 여유자금 회수가 포함되어 경상 세입이나 현재 규모로 사용하지 않는다.Historical 2022 values from Table 2-9, including transfers and surplus recovery; not recurring revenue or current size.
원문 수치 재구성 · PDF 37쪽Re-presented source values · PDF pages 37
원문의 핵심 표·그래프Key tables & figures in the source
표·그림이 수록된 원문 페이지입니다. 이미지를 누르면 확대할 수 있습니다.Original pages containing the selected tables or figures. Select an image to enlarge it.
기금 수입 구성 원표Original fund receipt composition
사업자 유형별 부담금 추이Contributions by broadcaster type
분담금 산정체계 개선안Proposed assessment framework
투자와 책무 이행에 따른 감경 구간 예시Illustrative investment and compliance adjustments
법제 기록과 제안의 검증 범위Limits of this historical policy analysis
이 연구는 2023년 제도·통계와 이해관계자 의견을 토대로 한 정책·법제 분석이며 개정 효과를 관측한 인과 연구가 아니다. 해외 디지털세 요건·예정일과 일부 영문 요약에는 다른 주제가 섞인 문구가 있어 원문만으로 현행법을 안내하지 않는다. 계열 PP 정당성이나 최종 부담률 0.8~0.9% 예시는 저자 판단·계산으로 독립 재현되지 않았다. 제시한 조문·징수율·인센티브는 채택·시행·재정 개선 달성 사실과 구별해 보존한다.
This is a historical policy and legal analysis, not an impact evaluation of adopted amendments. Some tax descriptions, projected dates, and English-summary passages require reconciliation. Affiliated-channel reasoning and illustrative final rates are author assessments, not independently replicated results. Draft provisions, rates, and incentives are preserved as proposals rather than enacted rules or achieved fiscal improvements.
PDF 파일 15, 21, 22, 71, 106, 107, 136, 138, 148쪽PDF pages 15, 21, 22, 71, 106, 107, 136, 138, 148
근거 쪽: Evidence pages: 2, 3, 4, 5, 6, 12, 13, 14, 15, 16, 17, 18, 19, 21, 22, 23, 37, 38, 39, 43, 44, 58, 59, 60, 62, 63, 64, 71, 80, 87, 90, 94, 101, 103, 104, 106, 107, 108, 109, 113, 114, 115, 116, 118, 119, 120, 121, 123, 126, 127, 128, 130, 132, 133, 134, 135, 136, 137, 138, 139, 144, 145, 146, 147, 148, 149, 150, 151, 152, 153, 154, 155, 156, 157 · PDF 파일 기준, 인쇄 쪽수와 다를 수 있습니다. · PDF file pagination may differ from printed page numbers.
근거와 검토 범위Source and review scope
161쪽의 제공된 원문 자료를 기준으로 본문·표·선정 이미지를 확인했습니다. 해설은 연구 내용을 새 문장으로 정리했으며, 실제 원문 페이지를 함께 실었습니다. 분석 결과의 독립 재현이나 기관의 공식 입장 확인을 뜻하지 않습니다.
The text, tables and selected images were checked against the 161-page source document supplied for this site. This guide is an editorial summary accompanied by original source pages. This does not imply independent replication or institutional endorsement.
확인한 PDF 쪽: Source PDF pages: 1, 2, 3, 4, 5, 6, 12, 13, 14, 15, 16, 17, 18, 19, 21, 22, 23, 37, 38, 39, 43, 44, 58, 59, 60, 62, 63, 64, 71, 80, 87, 90, 94, 101, 103, 104, 106, 107, 108, 109, 113, 114, 115, 116, 118, 119, 120, 121, 123, 126, 127, 128, 130, 132, 133, 134, 135, 136, 137, 138, 139, 144, 145, 146, 147, 148, 149, 150, 151, 152, 153, 154, 155, 156, 157