정책·산업 자료 · 원문 해설Policy & industry material · Source-based guide
해외 영화산업 정책 동향 조사International Trends in Film Industry Policy
원문에서 김용희의 구체적인 참여 역할은 확인 중입니다.Yonghee Kim’s specific contribution is still being checked against the source.
연구 내용Overview
주요국의 영화·영상산업 지원과 OTT의 재정적 기여 제도를 비교하고, 디지털서비스세와 통상 쟁점을 검토한 이슈페이퍼다. 원문 표지는 이혜원을 저자로 기재하고 있어 김용희의 참여 여부를 별도로 확인해야 한다.
An issue paper comparing film support and financial contributions by streaming services across jurisdictions, with discussion of digital services taxes and trade issues. Its cover names Hyewon Lee; Yonghee Kim’s contribution remains unconfirmed.
원보고서의 문제의식·분석·제안을 정리한 해설입니다. 수치는 표시한 표와 쪽을 기준으로 읽습니다. 아래 표는 핵심 항목을 웹에서 읽도록 재구성했고, 원문 표·그림이 있는 페이지를 함께 제공합니다.This reading guide explains the report’s questions, analyses, and proposals in new wording. Tables below re-present selected source results for web reading, alongside images of the relevant original pages.
핵심부터 읽기Start with the main findings
- 해외 제도에서 비교할 것은 비율의 크기만이 아닙니다. 프랑스의 직접 제작투자 의무, 지정 기금에 대한 납부, 미국 주정부의 제작비 세액공제는 돈이 이동하는 경로가 서로 다릅니다. 제작사가 어떤 권리를 남기는지, 독립 제작에 얼마가 배분되는지, 이를 누가 감독하는지가 재원 총액과 함께 정책 성격을 결정합니다.Headline percentages are insufficient for comparing foreign systems. Direct production investment, payments to an earmarked fund and state production-tax credits move money through different channels. Retained producer rights, allocations to independent production and supervisory capacity matter alongside the total funding raised.PDF 파일 20, 24, 26, 39쪽PDF pages 20, 24, 26, 39
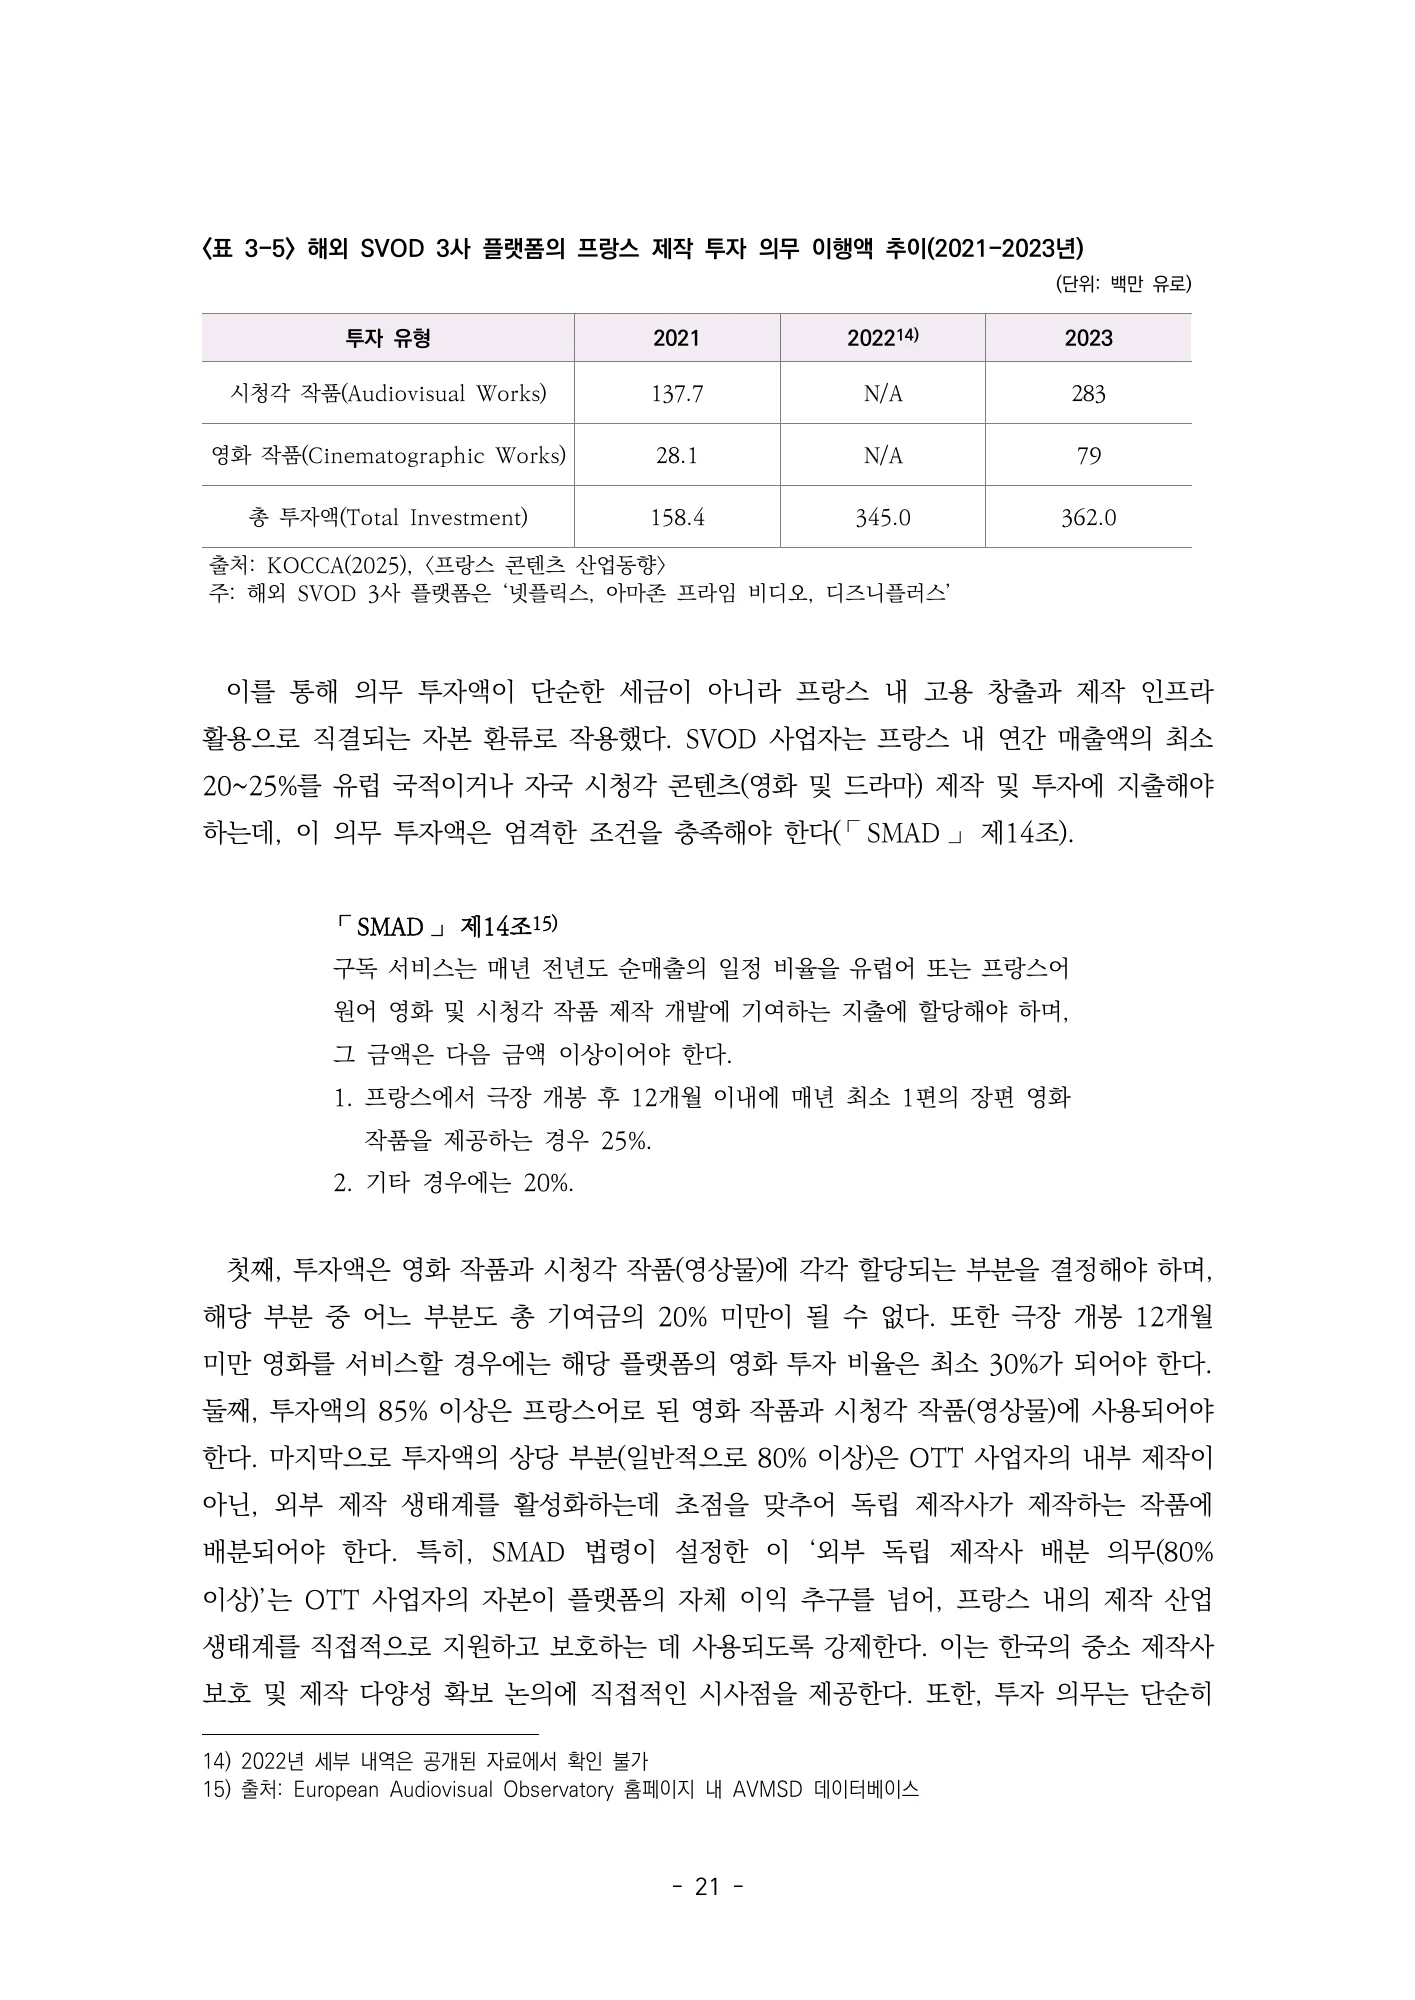
- 프랑스 사례의 2023년 투자 이행액은 시청각 작품 2억8,300만 유로와 영화 7,900만 유로, 합계 3억6,200만 유로입니다. 다만 같은 표의 2021년 두 부문 1억3,770만·2,810만 유로를 더하면 1억6,580만 유로로, 기재된 합계 1억5,840만 유로와 맞지 않습니다. 2022년 세부 내역도 N/A이므로 부문별 연속 성장률은 확정하지 않습니다.For 2023 the French compliance table reports EUR 283 million for audiovisual works and EUR 79 million for films, totalling EUR 362 million. The 2021 components sum to EUR 165.8 million, however, whereas the printed total is EUR 158.4 million. With 2022 components unavailable, a consistent sector-by-sector growth series cannot be established from this table.PDF 파일 24쪽PDF page 24
- 국내 대안은 투자액 유치와 제작사의 장기 수익 기반을 함께 묶습니다. IP 지분을 남긴 공동제작에 매칭 자금을 제공하고, 독립·지역 콘텐츠 투자에 가중치를 두며, 계약·기획·후반작업 인력을 지원하는 구상입니다. 이는 이미 성과를 낸 지원사업의 평가가 아니라 2025년 이슈페이퍼의 정책 제안입니다.The domestic alternatives link investment attraction to producers’ long-term revenues: matching finance for co-productions retaining IP, extra incentives for independent or regional work, and support for contracting, development and post-production skills. These are the issue paper’s 2025 proposals, not evaluated achievements of an implemented programme.PDF 파일 58, 59, 60, 61쪽PDF pages 58, 59, 60, 61
영화·영상 재원을 어떻게 되돌릴 것인가How should resources return to film and audiovisual production?
이 이슈페이퍼는 극장 중심 수익이 약해지고 OTT 투자가 커지는 환경에서 영화·영상 진흥 재원을 어떻게 마련할지를 묻습니다. 세금을 걷는 방식, 특정 산업에 기여를 요구하는 방식, 제작 투자를 유도하는 방식을 구분해 비교합니다. 표지는 이혜원을 저자로 명시하므로 이 자료를 김용희의 단독 연구로 소개하지 않으며, 현재 확인된 것은 보고서 내용과 출처입니다. 정책 제안은 보고서가 작성된 2025년의 논의로 읽어야 합니다.
This issue paper asks how film and audiovisual support can be financed as theatrical revenue weakens and streaming investment expands. It separates general taxation, industry-specific contributions and investment incentives. The cover names Hyewon Lee, so Yonghee Kim’s authorship remains unconfirmed. Its policy discussion is a dated 2025 position, not a statement of current law.
PDF 파일 1, 2, 64쪽PDF pages 1, 2, 64
문헌·법제·국가 사례를 비교한 자료A comparative documentary and policy review
자료는 국내 입법 논의, 해외 기금과 투자제도, 조세·통상 문헌을 연결한 비교 검토입니다. 소비자 설문이나 특정 제도 도입 전후의 자체 인과추정이 중심인 보고서는 아닙니다. 국가별 사례의 세율·적용 범위와 현재 시행 상태는 별도로 갱신 확인해야 하며, 이 웹 해설은 원문이 비교한 정책 수단과 논리를 설명합니다. 외부 문헌에서 재인용한 수치를 새로 조사한 사실이나 독립 재현한 효과로 바꾸지 않습니다.
The evidence combines Korean legislative discussion, foreign funding systems, investment obligations and tax/trade literature. It is not primarily an original consumer survey or a causal evaluation of one reform. This explanation describes the instruments and arguments compared in the source; externally cited estimates are not repackaged as newly measured or independently replicated findings.
PDF 파일 2, 3, 15, 47쪽PDF pages 2, 3, 15, 47
국내 부담금 논의의 법적 기반을 검토Domestic contribution proposals and legal foundations
국내 논의에서는 영화산업 지원의 필요성과 부담금 부과의 정당화가 같은 질문이 아니라는 점을 검토합니다. 보고서는 납부 집단의 관련성·수혜·책임과 OTT의 법적 지위, 여러 기관에 나뉜 규제 체계와 법적 근거를 쟁점으로 다룹니다. 이것은 저자의 법정책적 논증이지 특정 부담금이 위헌이라는 확정 판결을 제시하는 것이 아닙니다. 지원 목적이 타당하더라도 수단별 근거와 집행 가능성을 따로 설계해야 한다는 문제의식입니다.
The domestic chapter distinguishes the need to support production from the justification for a particular levy. It discusses affected groups, benefits and responsibility, OTT classification and fragmented governance. These are legal-policy arguments rather than a definitive court ruling. A legitimate cultural objective does not remove the need to examine the chosen collection mechanism.
PDF 파일 2쪽PDF page 2
해외 제도는 하나의 'OTT 부담금'이 아님Foreign systems are not one uniform OTT levy
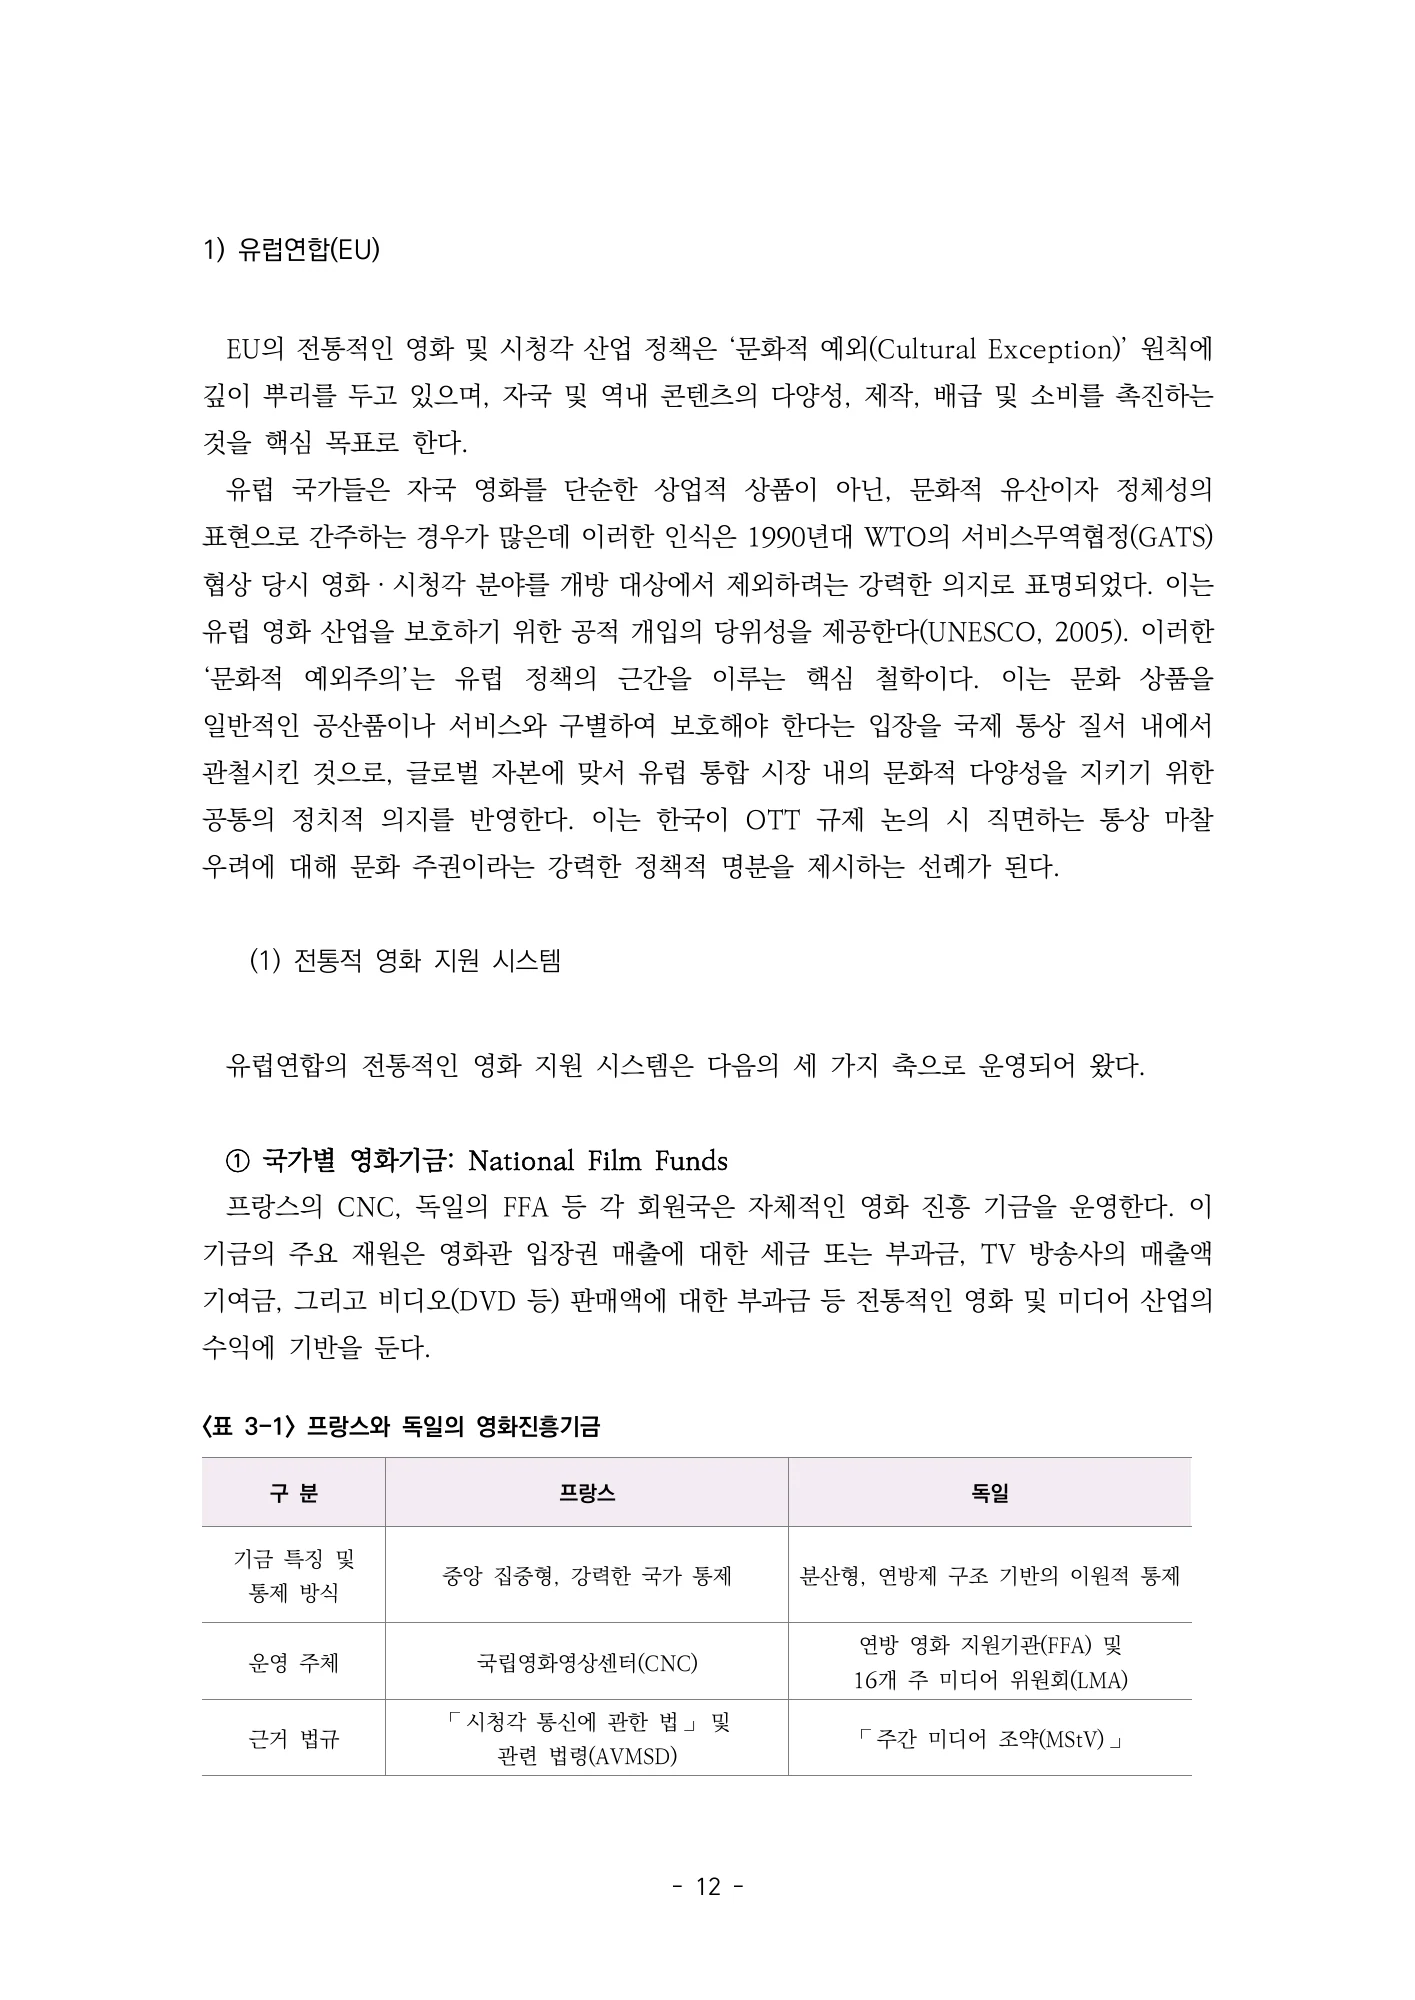
해외 비교는 EU와 프랑스·독일·스페인, 캐나다, 미국, 일본을 다룹니다. 프랑스의 재투자 중심 접근과 독일의 분산된 체계, 스페인의 기금 납부, 캐나다의 방송 규율, 미국의 세제 인센티브와 일본의 유연한 접근을 서로 다른 모델로 소개합니다. 프랑스 CNC와 독일 FFA 비교표도 중앙집중·연방적 구조의 차이를 보여줍니다. 다른 나라의 숫자 하나를 국내에 그대로 옮기기보다 재원·운영주체·문화정책과의 결합을 함께 살피는 비교입니다.
The comparison covers the EU, France, Germany, Spain, Canada, the United States and Japan. It distinguishes reinvestment, federal/decentralized structures, fund payments, broadcasting regulation, tax incentives and softer coordination. The France–Germany table illustrates governance differences. Borrowing a headline percentage without its financing and institutional context would miss the report’s comparative point.
PDF 파일 2, 15쪽PDF pages 2, 15
디지털서비스세와 콘텐츠 기금의 차이Digital services tax differs from a content fund
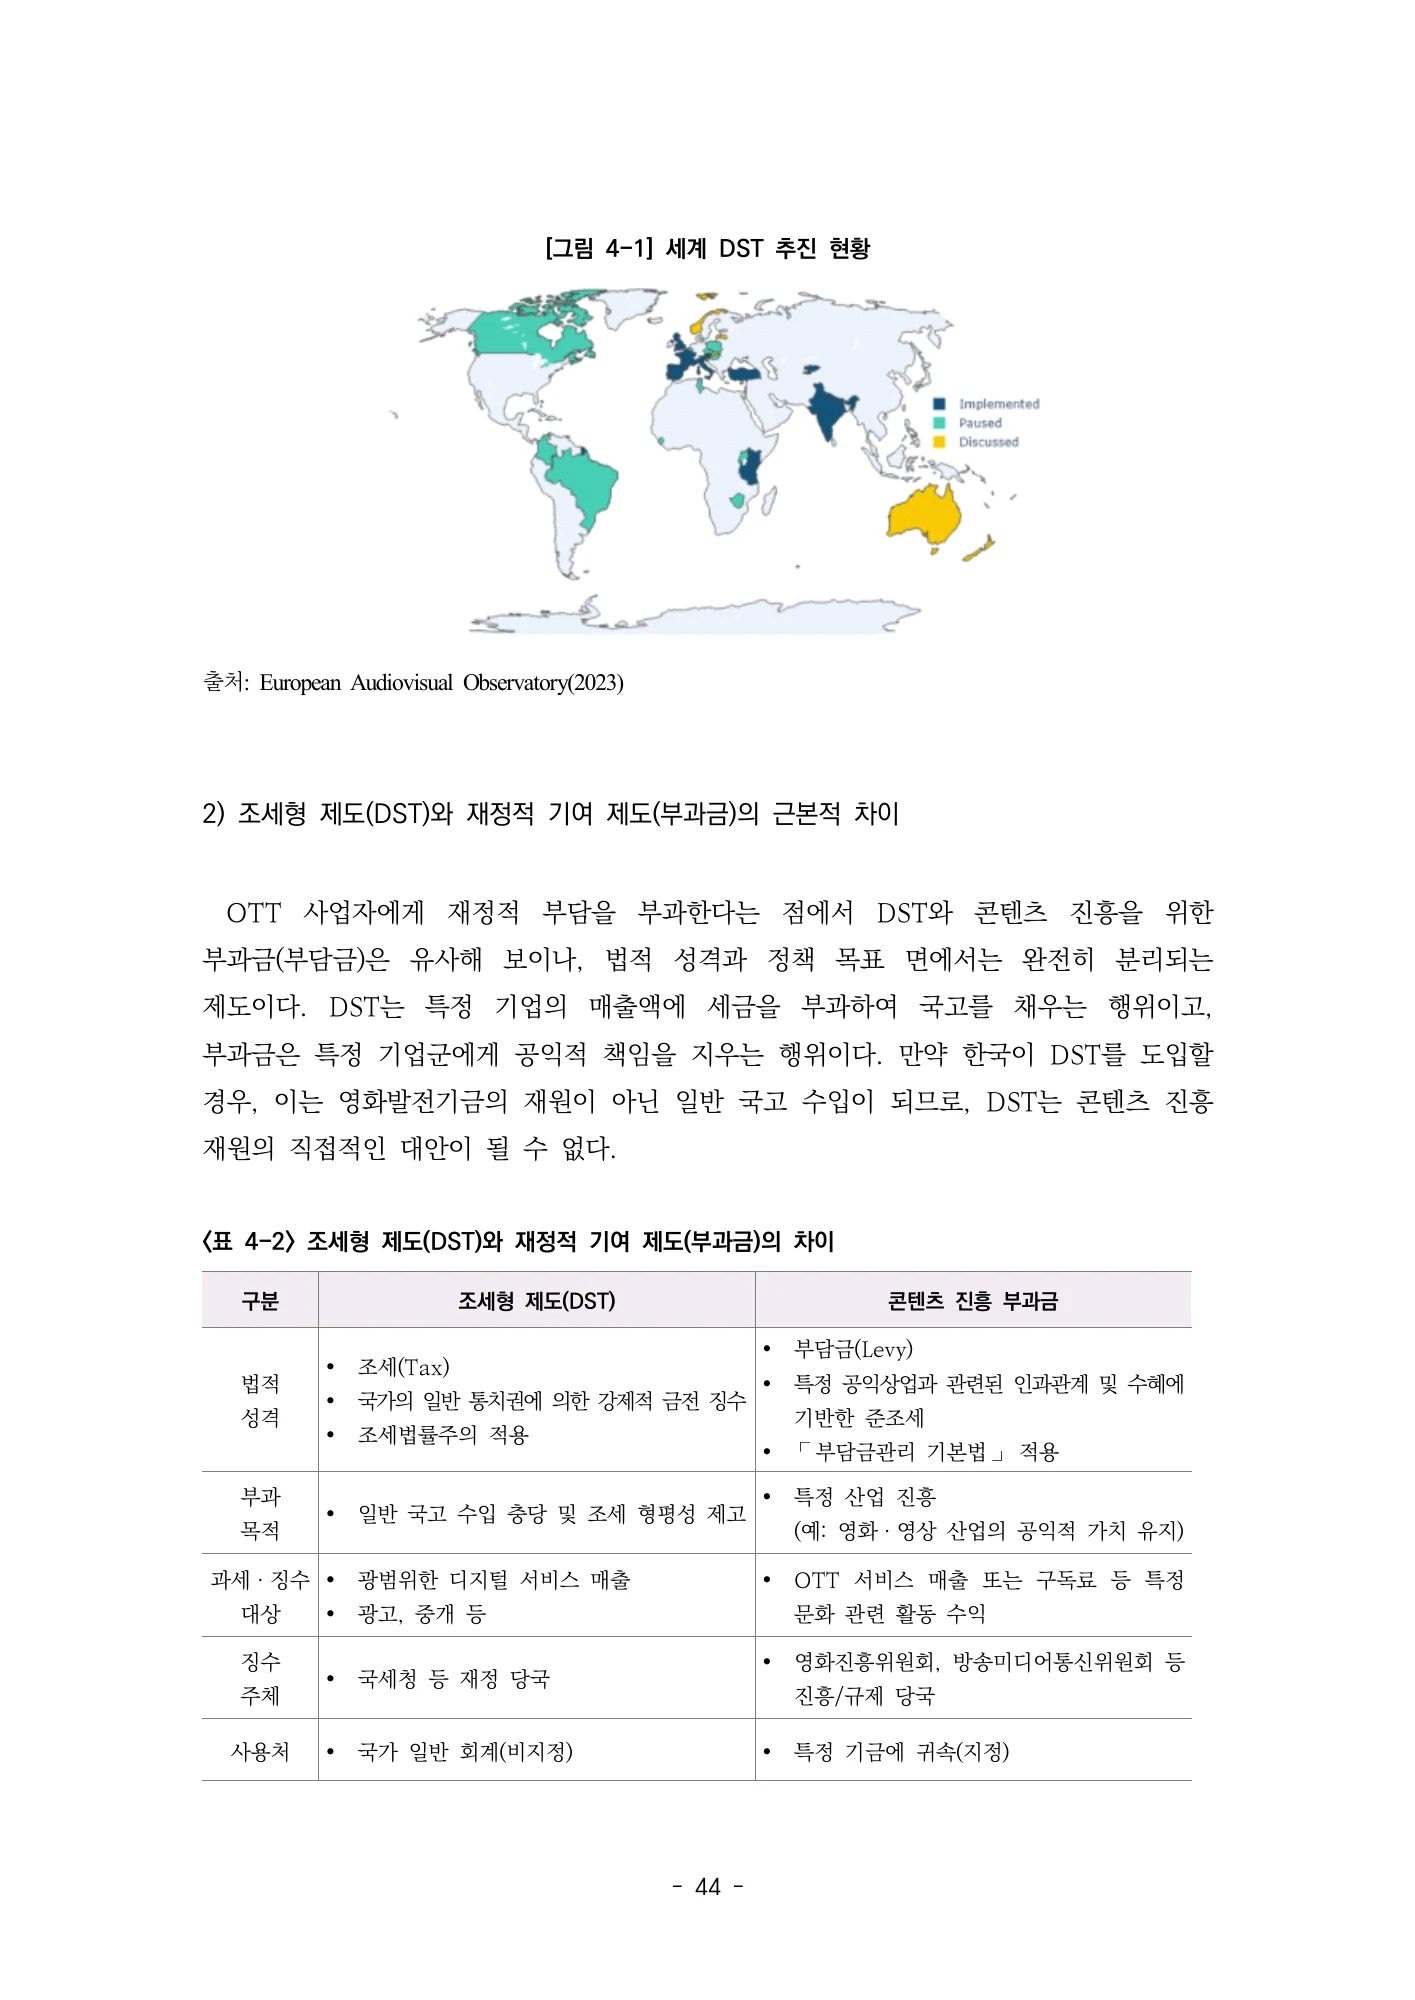
보고서의 핵심 구분은 DST와 콘텐츠 진흥 부과금입니다. 둘 다 기업에 금전 부담을 줄 수 있지만 DST는 일반 조세수입과 조세 형평성, 콘텐츠 부과금은 특정 산업의 공익목표와 지정된 재원을 중심으로 설명합니다. 따라서 디지털서비스세를 도입하면 그 수입이 자동으로 영화지원금이 된다고 볼 수 없습니다. 과세 대상·징수 주체·회계 귀속을 구분해야 정책 대안 사이의 재원 효과와 책임 관계를 비교할 수 있습니다.
The paper distinguishes DST from earmarked cultural contributions. Both impose costs, but the former concerns general tax revenue and tax equity, while the latter is tied to an industry-specific purpose and funding destination. A DST therefore does not automatically become film-support revenue. Tax base, collecting authority and allocation arrangements must be examined separately.
PDF 파일 47쪽PDF page 47
통상 위험은 가능성 검토로 제시Trade risks are evaluated rather than adjudicated
GATS, 한미 FTA, 투자자 분쟁 등은 보고서가 검토한 정책 위험의 범위입니다. 원문은 강제 납부보다 자율 협력의 안정성을 강조하지만, 웹 해설에서는 자발적이라는 이름만으로 통상 위험이 완전히 사라진다고 단정하지 않습니다. 실제 법문, 적용 방식, 차별 여부와 협약의 구속력에 따라 검토가 필요합니다. 특정 국가나 기업이 향후 분쟁을 제기할지, 배상액이 얼마가 될지를 이 비교 자료로 확정할 수는 없습니다.
The trade chapter considers GATS, the Korea–U.S. FTA and investment disputes. The source favors voluntary cooperation, but labeling an arrangement voluntary does not itself prove that all trade risks disappear. Legal text, implementation, discrimination and enforceability matter. Neither future litigation nor damages are established by this documentary comparison.
PDF 파일 2, 60, 64쪽PDF pages 2, 60, 64
투자협약·성과 인센티브·IP 공유를 연결Link agreements, incentives and IP sharing
대안은 자율적 콘텐츠 투자협약, 성과 연동 세제 인센티브, 공동제작·IP 공유, 다자간 공익 펀드와 인력·기술 기반 지원을 묶는 방향입니다. 협약의 실효성을 높이기 위해 행정 지원과 투자 실적을 연결하고, 국내 제작사의 권리와 장기 수익 기반을 고려하자고 제안합니다. 독립·지역·실험 콘텐츠처럼 상업적 투자만으로 부족한 영역의 지원도 다룹니다. 이 수단들이 이미 실행돼 성과를 냈다는 뜻이 아니라 보고서가 제안하는 정책 묶음입니다.
Proposals combine voluntary investment agreements, performance-linked tax incentives, co-production and IP sharing, multilateral public-interest funds, and skills and technology support. The report connects administrative facilitation to measurable investment and considers independent, regional and experimental work. These are proposed instruments, not achieved outcomes from an implemented package.
PDF 파일 58, 60쪽PDF pages 58, 60
이행 측정과 제작 생태계 역량이 필요Implementation requires measurement and production capacity
실행 관점에서는 약정한 투자가 실제 국내 제작·인력·IP 기반으로 이어졌는지 측정할 기준이 필요합니다. 투자액만 늘었는지, 권리가 국내 제작사에 남는지, 소규모 제작자도 접근 가능한지를 구분할 수 있어야 합니다. 보고서는 단기 기금 부족을 한 번에 해결하기보다 안정적인 투자 유입과 제작 생태계 자립을 목표로 삼습니다. 웹에서는 이를 정책 목표와 점검 과제로 정리하며 확인되지 않은 예산·세수·고용 실적을 추가하지 않았습니다.
Implementation requires distinguishing spending volume from domestic production, workforce and IP benefits. Access for smaller producers also matters. The paper prioritizes stable investment and ecosystem capacity over an immediate solution to every funding gap. These are objectives and evaluation questions; this account adds no unverified budget, revenue or employment achievements.
PDF 파일 58, 60, 64쪽PDF pages 58, 60, 64
직접 투자 의무를 읽는 세 가지 조건Three conditions behind direct investment obligations
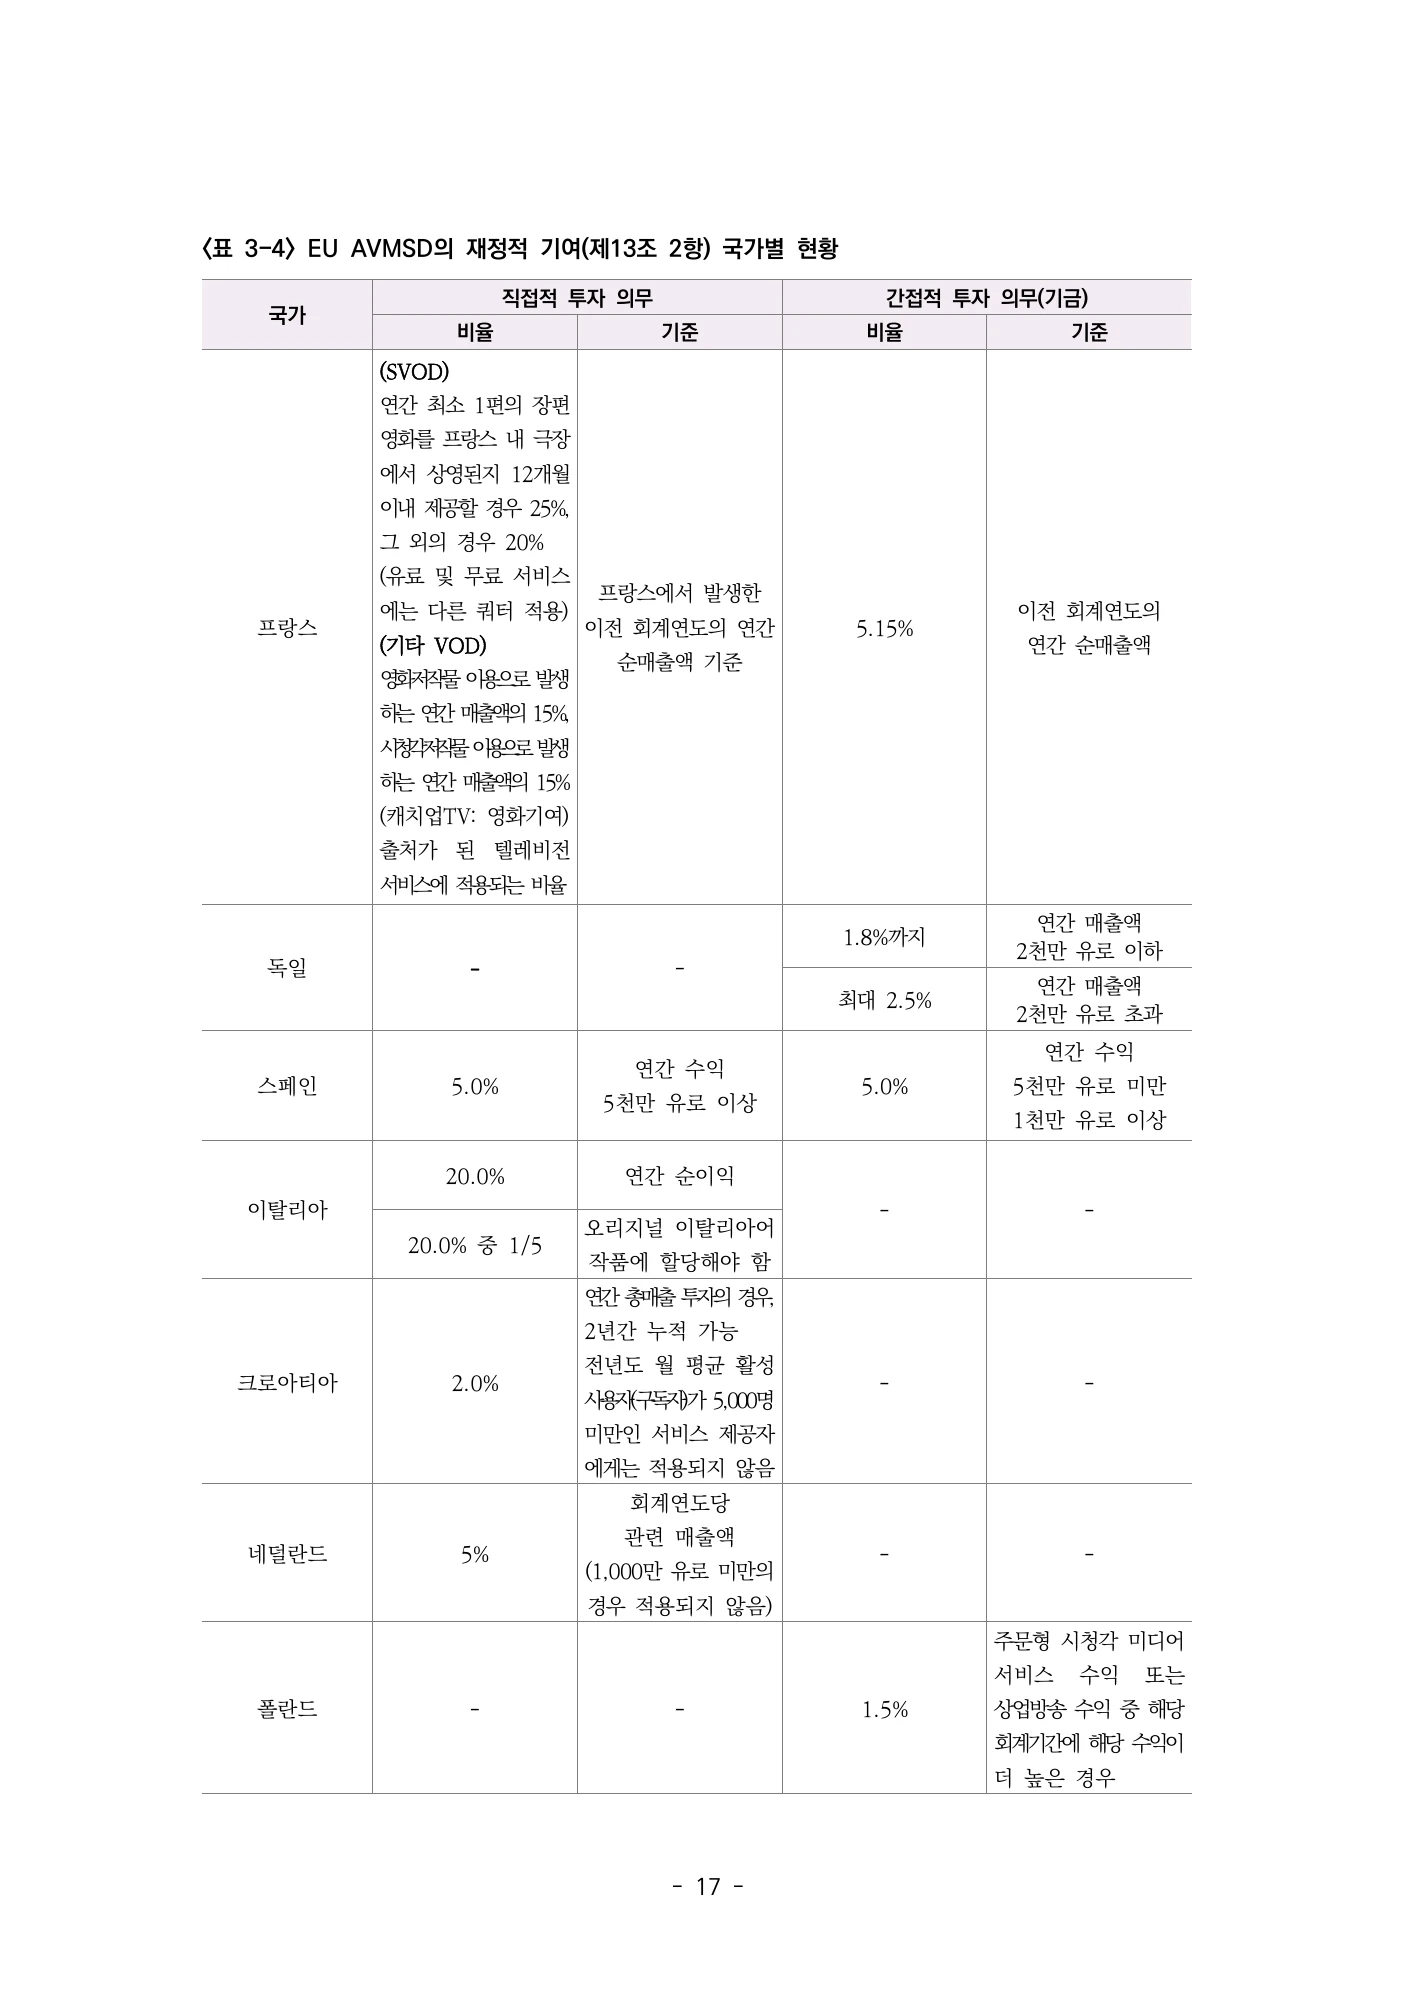
프랑스 설명은 자국 내 전년도 순매출을 기준으로 한 투자 비율에 언어·장르·독립 제작 배분과 홀드백을 결합합니다. 보고서가 소개한 20%와 25%는 모든 영상사업자에게 동일하게 적용되는 단일 세율이 아닙니다. 극장 개봉 뒤 언제 제공하는지와 서비스 종류 등에 따라 조건이 달라지는 투자 의무로 설명됩니다.
The French discussion combines prior-year domestic net revenue with language, genre, independent-production and release-window conditions. Its 20% and 25% figures are not a single tax rate applying uniformly to all audiovisual businesses; the obligations depend on service and release-window conditions.
따라서 국내 적용을 검토할 때는 징수율만 정할 것이 아니라 적격 투자 인정 범위, 외부 제작사에 남는 권리, 실제 이행을 확인할 회계·감독 역량까지 정해야 합니다. 원문도 프랑스 모델의 복잡한 배분 규칙을 관리하려면 CNC·Arcom의 전문성과 감시 체계가 필요하다고 지적합니다. 해외 제도를 한국에서 곧바로 시행할 수 있다는 결론은 아닙니다.
Domestic adaptation would also require eligible-investment rules, retained rights for outside producers and accounting and supervisory capacity. The source itself highlights the expertise needed to administer the French allocation rules. The comparison does not establish that the model can simply be implemented in Korea.
PDF 파일 20, 24, 26쪽PDF pages 20, 24, 26
제작 대행을 넘어 IP 수익이 남는 구조From production services to retained IP revenue
공동제작 부분은 국내 제작사가 최소 20%의 IP 지분을 확보하는 프로젝트에 초기 자금 일부를 매칭 융자·투자하는 예를 제안합니다. 영세 제작사의 경우 선구매 계약 뒤에도 국내 부가판권과 유통권 일부를 유보하도록 지원하자는 구상입니다. 20%는 이 보고서의 설계 예시이며 법정 기준이나 관측된 평균 계약 조건이 아닙니다.
The co-production section proposes matching loans or investment where a Korean producer retains at least 20% of IP. It also proposes helping smaller producers retain some domestic ancillary and distribution rights after presales. The 20% threshold is a design example, not a statutory rule or an observed average contract term.
계약 표준안·중립적 분쟁조정·IP 전문인력 양성을 함께 제시하는 이유는 현금 지원만으로 협상력과 권리 활용 역량이 확보되지 않기 때문입니다. 또한 독립·지역·실험 콘텐츠용 공동 펀드와 기술 인프라 지원을 연결합니다. 문화적 목적이나 자발적 협력이라는 명칭만으로 통상상 정당성이 자동 확보되는 것은 아니므로 원문의 기대와 법적 확정 판단을 구분합니다.
Standard contracts, neutral dispute support and IP specialists complement finance because cash alone does not secure bargaining or exploitation capability. The package also links public-interest funds and technical infrastructure. Cultural objectives or voluntary labels do not themselves establish trade-law compatibility; the source’s policy expectations remain distinct from a legal determination.
PDF 파일 59, 60, 61, 62쪽PDF pages 59, 60, 61, 62
핵심 결과를 표로 읽기Read the key results in tables
| 구분Dimension | DST | 콘텐츠 진흥 부과금Content contribution |
|---|---|---|
| 성격Character | 일반 조세General tax | 특정 목적 부담금Purpose-specific levy |
| 주요 목적Purpose | 일반 재정·조세 형평General revenue and tax equity | 특정 산업 진흥Industry promotion |
| 귀속Destination | 일반 회계General budget | 지정 기금Earmarked fund |
원문 표 4-2의 개념 비교를 간추렸습니다. 현재 법률적 결론이나 모든 국가의 동일한 회계 처리를 뜻하지 않습니다.Condensed conceptual comparison from Table 4-2; it is not a current legal determination or a universal accounting rule.
이 표를 읽는 방법How to read this table
표의 ‘귀속’ 행은 금전 부담의 크기보다 돈의 사용처를 비교합니다. 일반 국고 수입은 별도의 배분 결정 없이 영화 지원으로 자동 이전되지 않으며, 지정 기금은 대상 산업과 사업 목적을 따로 정합니다. 같은 디지털 매출이 언급되더라도 두 제도를 같은 재원으로 합산할 수 없습니다.The destination row compares where money goes, rather than how large a charge is. General revenue does not automatically transfer to film support without an allocation decision; an earmarked fund specifies its sector and purpose. References to digital revenue do not make the instruments interchangeable or additive.
원문은 표의 다음 쪽에서 국제 조세와 통상 위험도 구분합니다. DST와 문화 기여의 법적 근거·과세 대상·집행 주체가 다르므로 어느 쪽이 항상 더 안전하다는 순위표로 읽기 어렵습니다. 이는 보고서의 개념 비교이며 국가별 현재 제도는 개별 확인이 필요합니다.The continuation also separates international tax and trade risks. Different legal bases, bases of assessment and collecting authorities preclude treating the table as a universal ranking of legal safety. It is the report’s conceptual comparison, not an update of every jurisdiction’s current rules.
PDF 파일 47, 48쪽PDF pages 47, 48
원문 표 4-2 재구성Adapted from original Table 4-2 · PDF 파일 47쪽PDF page 47
원문의 핵심 표·그래프Key tables & figures in the source
표·그림이 수록된 원문 페이지입니다. 이미지를 누르면 확대할 수 있습니다.Original pages containing the selected tables or figures. Select an image to enlarge it.
프랑스·독일의 기금 구조French and German funding structures
국가별 직접 투자와 기금 납부의 비교Direct investment versus fund contributions across countries
프랑스 투자 이행액과 배분 조건French investment compliance and allocation conditions
세금과 지정 기여의 차이Tax and earmarked contribution
외부 사례와 제안의 효과를 구분Distinguish foreign examples from validated policy effects
이 자료의 강점은 수단 간 차이를 비교하는 데 있지만, 여러 국가의 법제를 같은 시점·범위로 독립 재검증한 감사 결과는 아닙니다. 현재 세율과 법안 상태, 국내 적용 적법성은 별도 확인이 필요합니다. 원문의 '위험 차단'이나 큰 경제적 효과 같은 강한 표현도 검토 의견과 기대 수준으로 구분했습니다. 저자·참여 역할이 미확인인 상태를 유지하며, 본문을 읽을 수 있게 제공하는 것과 김용희 개인의 수행 실적을 확정하는 일은 분리합니다.
The report’s strength is comparative instrument design, not independent validation of every foreign law or policy effect. Current rates, bill status and domestic legality need separate checking. Strong claims about eliminating risks or generating benefits remain proposals or expectations. Unconfirmed personal participation is preserved; access to the explanation does not certify authorship.
PDF 파일 1, 47, 58, 64쪽PDF pages 1, 47, 58, 64
근거 쪽: Evidence pages: 1, 2, 3, 15, 20, 24, 26, 39, 47, 48, 58, 59, 60, 61, 62, 64 · PDF 파일 기준, 인쇄 쪽수와 다를 수 있습니다. · PDF file pagination may differ from printed page numbers.
근거와 검토 범위Source and review scope
67쪽의 제공된 원문 자료를 기준으로 본문·표·선정 이미지를 확인했습니다. 해설은 연구 내용을 새 문장으로 정리했으며, 실제 원문 페이지를 함께 실었습니다. 분석 결과의 독립 재현이나 기관의 공식 입장 확인을 뜻하지 않습니다.
The text, tables and selected images were checked against the 67-page source document supplied for this site. This guide is an editorial summary accompanied by original source pages. This does not imply independent replication or institutional endorsement.
확인한 PDF 쪽: Source PDF pages: 1, 2, 3, 15, 20, 24, 26, 39, 47, 48, 58, 59, 60, 61, 62, 64