정책·산업 자료 · 원문 해설Policy & industry material · Source-based guide
유료방송 콘텐츠 거래시장 분석과 제언Analysis and recommendations for the pay-TV content trading market
김용희의 원문 역할: 연구책임자Yonghee Kim’s documented role: Principal investigator
연구 내용Overview
국내외 유료방송 플랫폼과 콘텐츠 사업자의 재무·가입자·콘텐츠 비용 자료를 비교하고 거래제도 개선을 제안한 연구입니다. 자료 항목의 국가·기업 간 차이와 일부 추정치가 포함된다는 한계를 본문에 명시합니다.
This study compares financial, subscriber and content-cost data for pay-TV platforms and content providers and proposes trading reforms. It explicitly notes differences in accounting categories and the use of estimates for missing data.
원보고서의 문제의식·분석·제안을 정리한 해설입니다. 수치는 표시한 표와 쪽을 기준으로 읽습니다. 아래 표는 핵심 항목을 웹에서 읽도록 재구성했고, 원문 표·그림이 있는 페이지를 함께 제공합니다.This reading guide explains the report’s questions, analyses, and proposals in new wording. Tables below re-present selected source results for web reading, alongside images of the relevant original pages.
핵심부터 읽기Start with the main findings
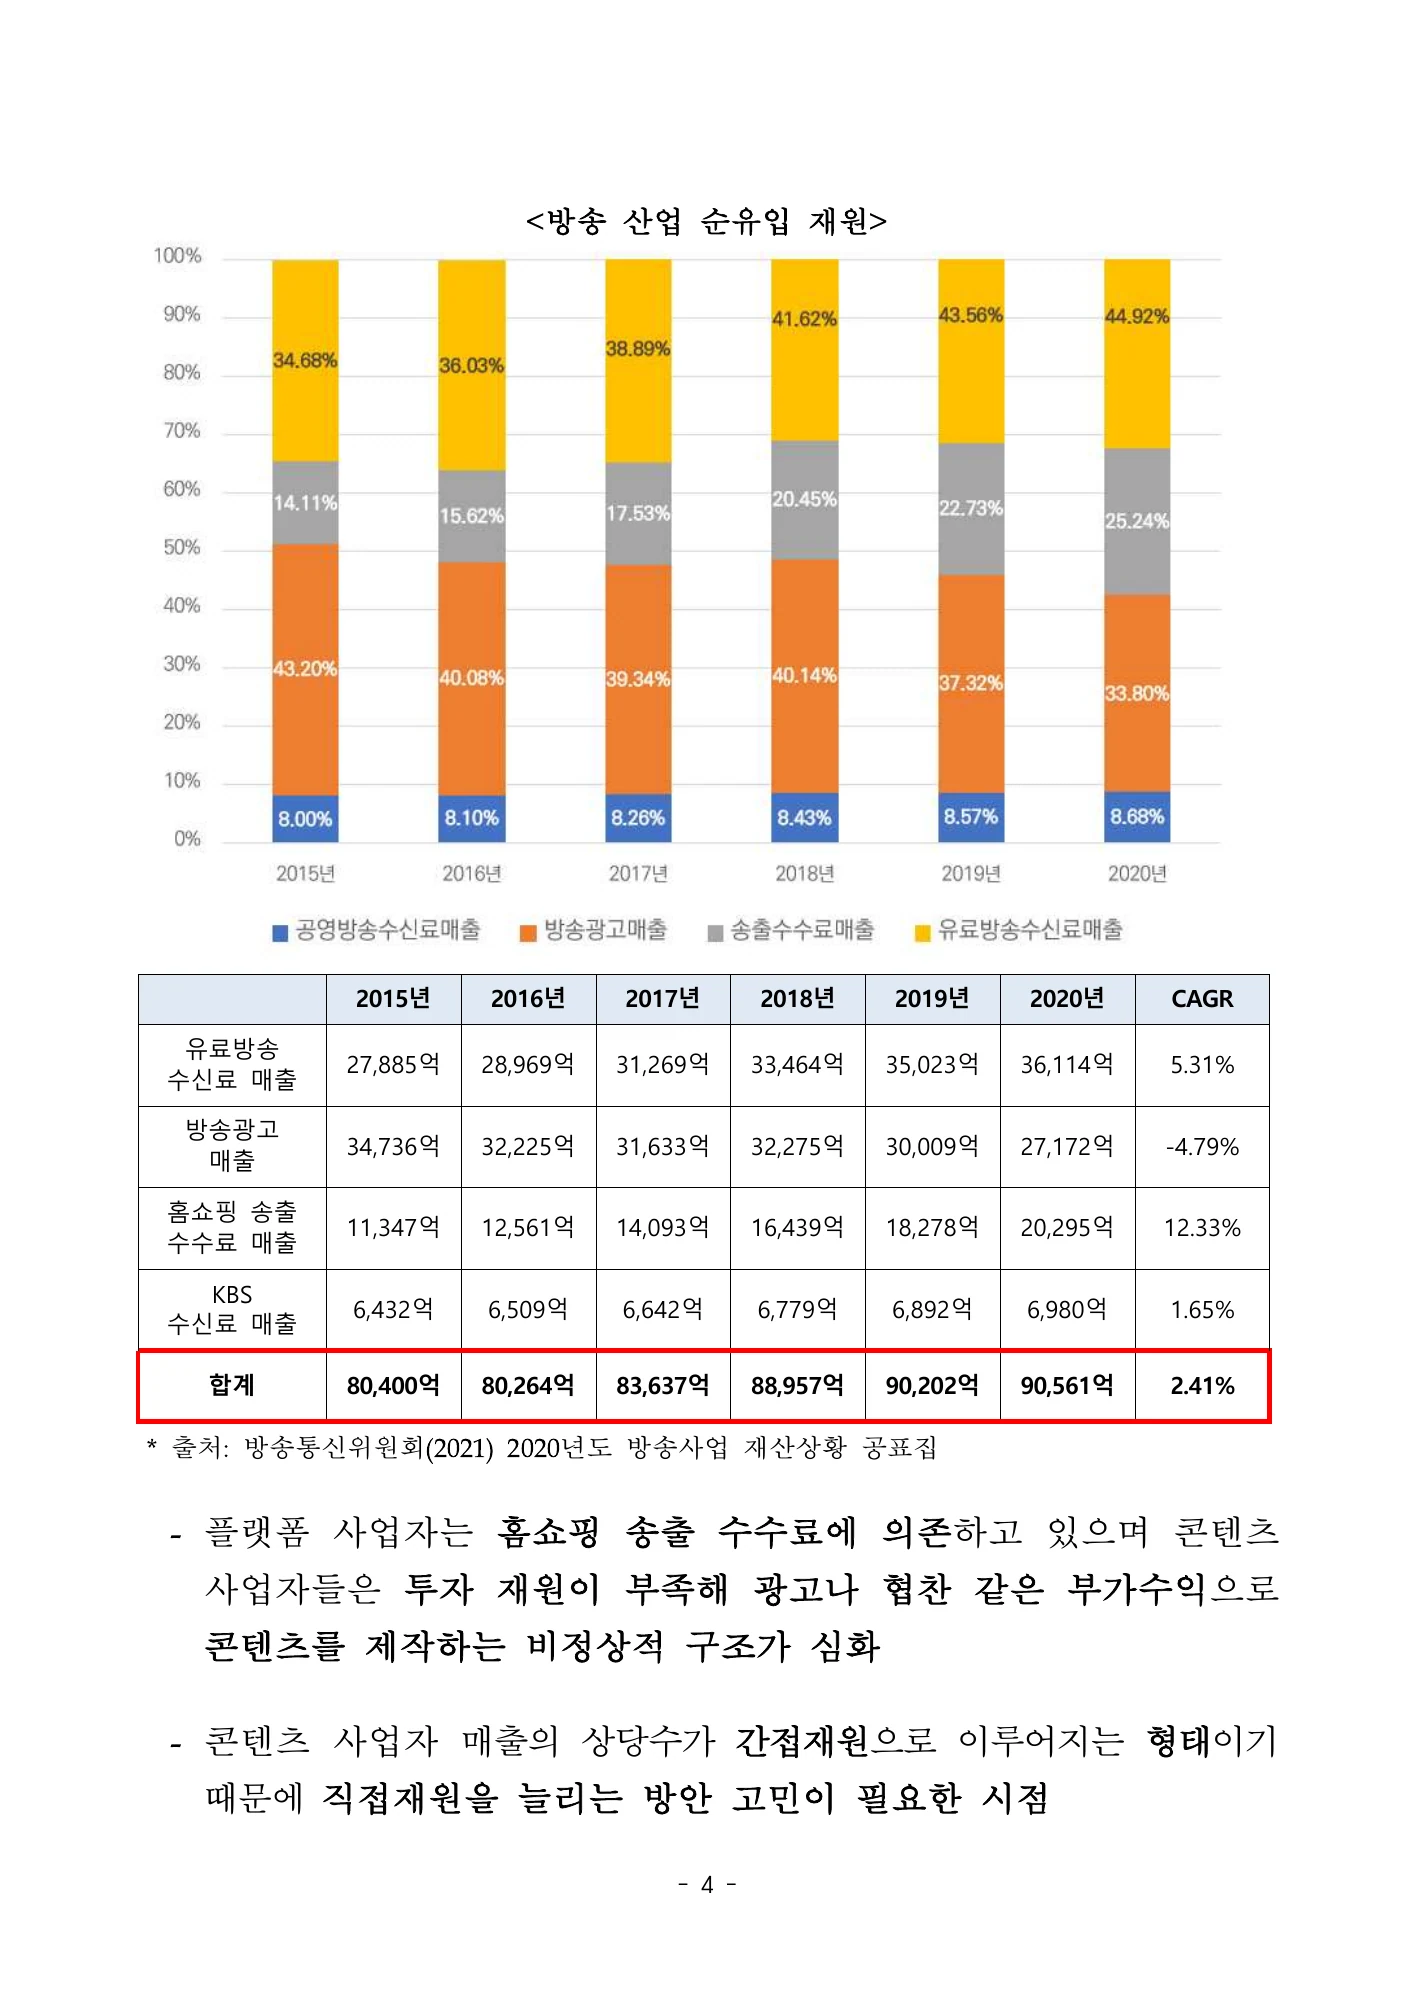
- 보고서는 콘텐츠 대가 문제를 플랫폼과 PP 사이의 배분뿐 아니라 방송산업으로 들어오는 재원의 구성으로 설명한다. 수신료 증가만 보지 않고 광고 감소와 홈쇼핑 송출수수료 의존을 함께 살펴야 한다.Content remuneration is considered through both platform–channel distribution and the composition of funding entering broadcasting. Subscription growth must be read alongside advertising decline and dependence on home-shopping carriage fees.PDF 파일 6, 7, 8쪽PDF pages 6, 7, 8
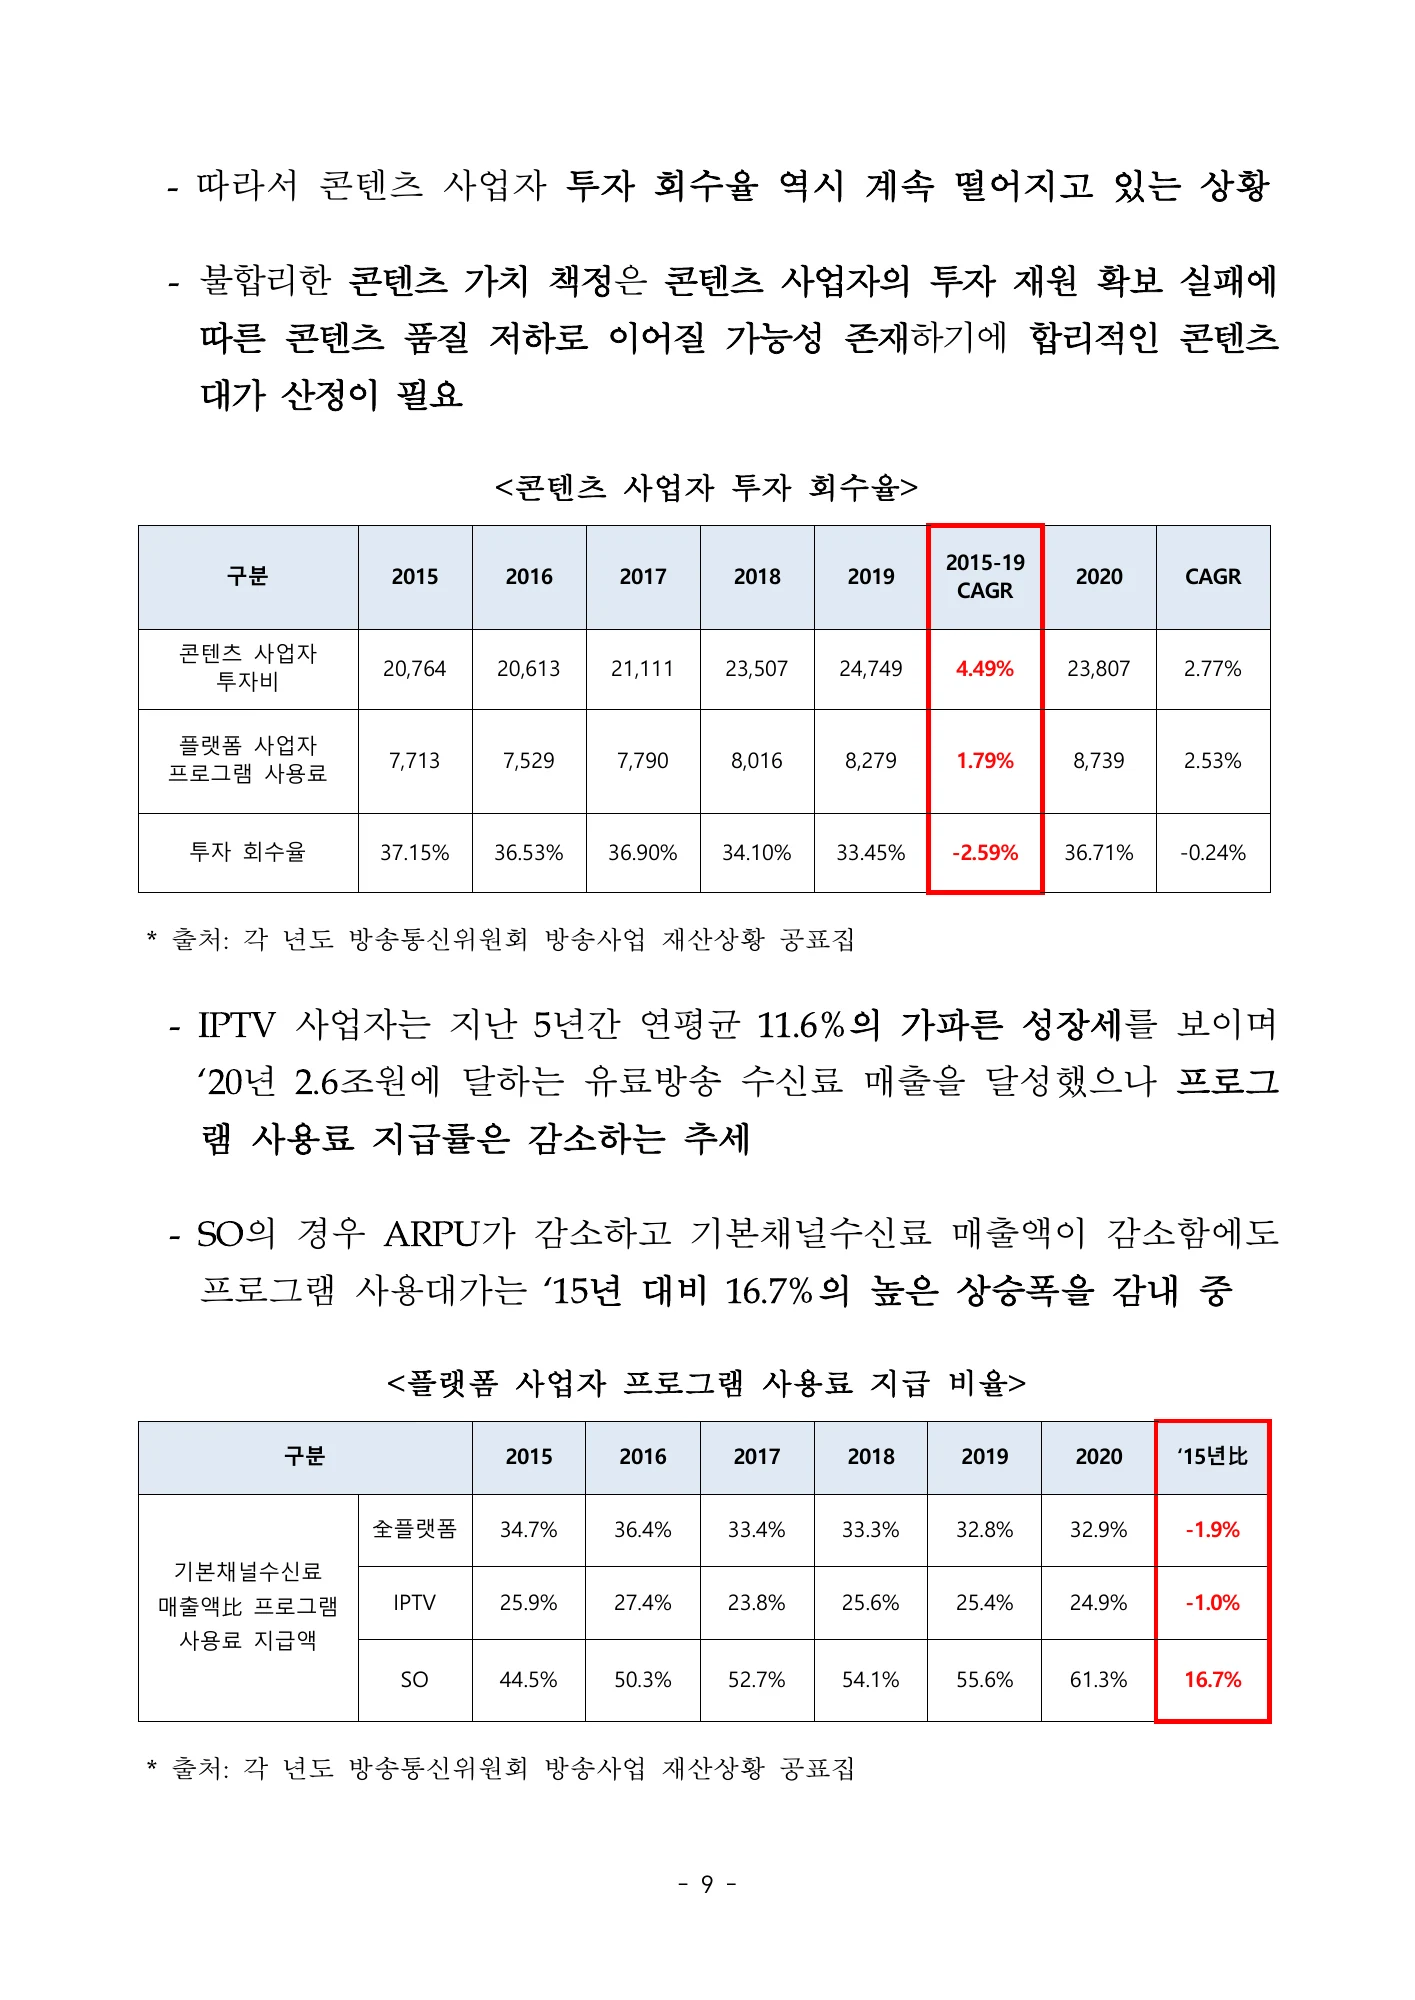
- 2020년 기본채널 수신료 대비 지급비율은 SO 61.3%, IPTV 24.9%지만 이는 각각의 기본채널 수입을 분모로 한다. 전체 방송사업 매출이나 전체 수신료를 분모로 한 비율과 서로 섞을 수 없다.The 2020 ratios are61.3% for cable and24.9% for IPTV, each relative to its basic-channel subscription revenue. They must not be mixed with ratios based on total broadcasting or total subscription revenue.PDF 파일 12, 13쪽PDF pages 12, 13
- 제안은 자율협상을 유지하면서 평가·분쟁조정·계약시기를 투명하게 관리하는 구조다. 모수 확대와 최저배분율은 검토안이며 법정 지급률이나 현재 계약조건으로 제시하지 않는다.The proposed model retains negotiation while making evaluation, dispute handling and contract timing more transparent. A wider base and minimum allocation ratios are options, not established legal payment rates or current contract terms.PDF 파일 28, 29, 30, 31, 32, 33쪽PDF pages 28, 29, 30, 31, 32, 33
콘텐츠 거래의 대가와 재원 문제Content prices and the funding base
보고서는 플랫폼의 성장과 콘텐츠 제작투자 회수가 맞물리지 않는 유료방송 거래 구조를 검토한다. 글로벌 OTT, 사업자 결합과 광고 이동 속에서 콘텐츠 대가를 어떻게 결정하고 분쟁을 줄일지 묻는다. 이를 위해 시장의 매출을 단순 합산하는 대신 외부에서 들어오는 재원을 따로 보고, 국내 지급 구조와 해외 기업의 투자 회수·수익성 지표를 비교한 뒤 제도 대안을 제시한다. 김용희는 원문 연구진 명단에서 연구책임자로 확인되지만, 제안된 방안이 실제 채택되었다는 사실까지 이 보고서가 입증하는 것은 아니다.
The report examines how platform growth connects with recovery of content investment in pay television. Global OTT services, consolidation and advertising shifts frame its questions about remuneration and disputes. It distinguishes external funding from transactions inside the broadcasting ecosystem, compares domestic and overseas company measures, and develops institutional options. The source credits Kim Yonghee as research lead. That authorship evidence does not imply that the recommended arrangements were later implemented.
PDF 파일 3, 4, 5, 6쪽PDF pages 3, 4, 5, 6
외부 유입 재원과 국내 거래 추이External funding and domestic trading trends
시장 내부의 프로그램 사용료 등을 중복 계산하지 않으려는 순유입 관점에서 수신료·광고·홈쇼핑 송출수수료·KBS 수신료를 나누어 본다. 원문 집계에서 2015~2020년 총액은 80,400억원에서 90,561억원으로 증가하지만 광고는 감소하고 홈쇼핑 송출수수료 비중이 커진다. 콘텐츠 투자비 대비 프로그램 제공 매출의 비율, 기본채널 수신료 대비 사용료 비율은 서로 다른 지표다. 예컨대 2020년 SO 61.3%와 IPTV 24.9%는 후자의 분모를 사용하는 비율로서 전체 매출 배분율로 바꾸어 표현하지 않는다.
The net-inflow perspective separates subscriptions, advertising, home-shopping carriage fees and KBS licence fees to avoid double-counting internal payments. The source’s total rises from KRW 8.040 trillion in 2015 to KRW 9.0561 trillion in 2020, while advertising falls and carriage fees grow. Programme revenue relative to production cost differs from programme payments relative to basic-tier subscription revenue. The reported 2020 ratios of 61.3% for cable and 24.9% for IPTV use the latter denominator, not total corporate revenue.
PDF 파일 6, 7, 8, 9, 12, 13쪽PDF pages 6, 7, 8, 9, 12, 13
해외 비교 자료의 구성과 한계Construction and limits of the international dataset
해외 자료는 2020년 기업보고서·재무제표와 S&P Global, 일부 Yahoo 자료 등을 수집·재가공했다. 콘텐츠 사업자 16개국 41개, 플랫폼 21개국 45개가 대상이며 세부 항목이 없는 경우 추정치가 포함된다. 미국·캐나다·인도·유럽 사례로 프로그램 제공 매출, 제작비와 수신료 대비 사용료를 비교하지만 국가별 기업 범위·수직결합·수익 인식이 동일하지 않다. 원문도 비밀유지계약과 항목 차이를 경고하므로, 표의 평균을 한 나라 전체의 확정적 적정 가격이나 정책 기준으로 옮기지 않는다.
The international dataset reworks 2020 company reports, financial statements and S&P Global information, with some Yahoo-based or average-based estimates where detail is missing. It covers 41 content companies in 16 countries and 45 platforms in 21 countries. Cases span the United States, Canada, India and Europe. Differences in corporate scope, vertical integration, accounting and confidentiality limit comparability. Country averages are consequently descriptive sample measures rather than definitive national prices or regulatory benchmarks.
PDF 파일 10, 11, 14, 15, 16, 17, 18쪽PDF pages 10, 11, 14, 15, 16, 17, 18
수익성과 협상력의 해석Interpreting profitability and bargaining power
가입자, 광고, EBITDA 마진과 ARPU를 함께 살펴 국내의 낮은 수익·회수 구조를 문제로 제기한다. 거래 관계에서는 플랫폼과 콘텐츠가 상호 의존하면서도 독점적 콘텐츠, 플랫폼 집중, 수직계열화에 따라 협상력이 달라진다고 설명한다. 이는 시장 구조를 읽는 비교·개념 분석이며 낮은 ARPU가 제작투자 부족의 유일한 원인임을 계량적으로 식별한 인과 연구는 아니다. 국내 가입자 추이 설명도 일부 해외 국가의 표상 증가와 단순화된 본문 문장이 충돌하므로 모든 해외 시장이 감소한다고 일반화하지 않는다.
Subscriber trends, advertising, EBITDA margins and ARPU support the report’s diagnosis of constrained returns. Its bargaining framework explains how exclusive content, platform concentration and vertical integration may change negotiating power between mutually dependent parties. This is comparative and conceptual analysis, not causal identification of low ARPU as the sole determinant of investment. Some narrative generalisations about overseas subscriber decline also exceed the countries actually shown in the table.
PDF 파일 19, 20, 21, 22, 23, 24, 25쪽PDF pages 19, 20, 21, 22, 23, 24, 25
자율 거래와 공적 개입의 조합Combining autonomous negotiation with intervention
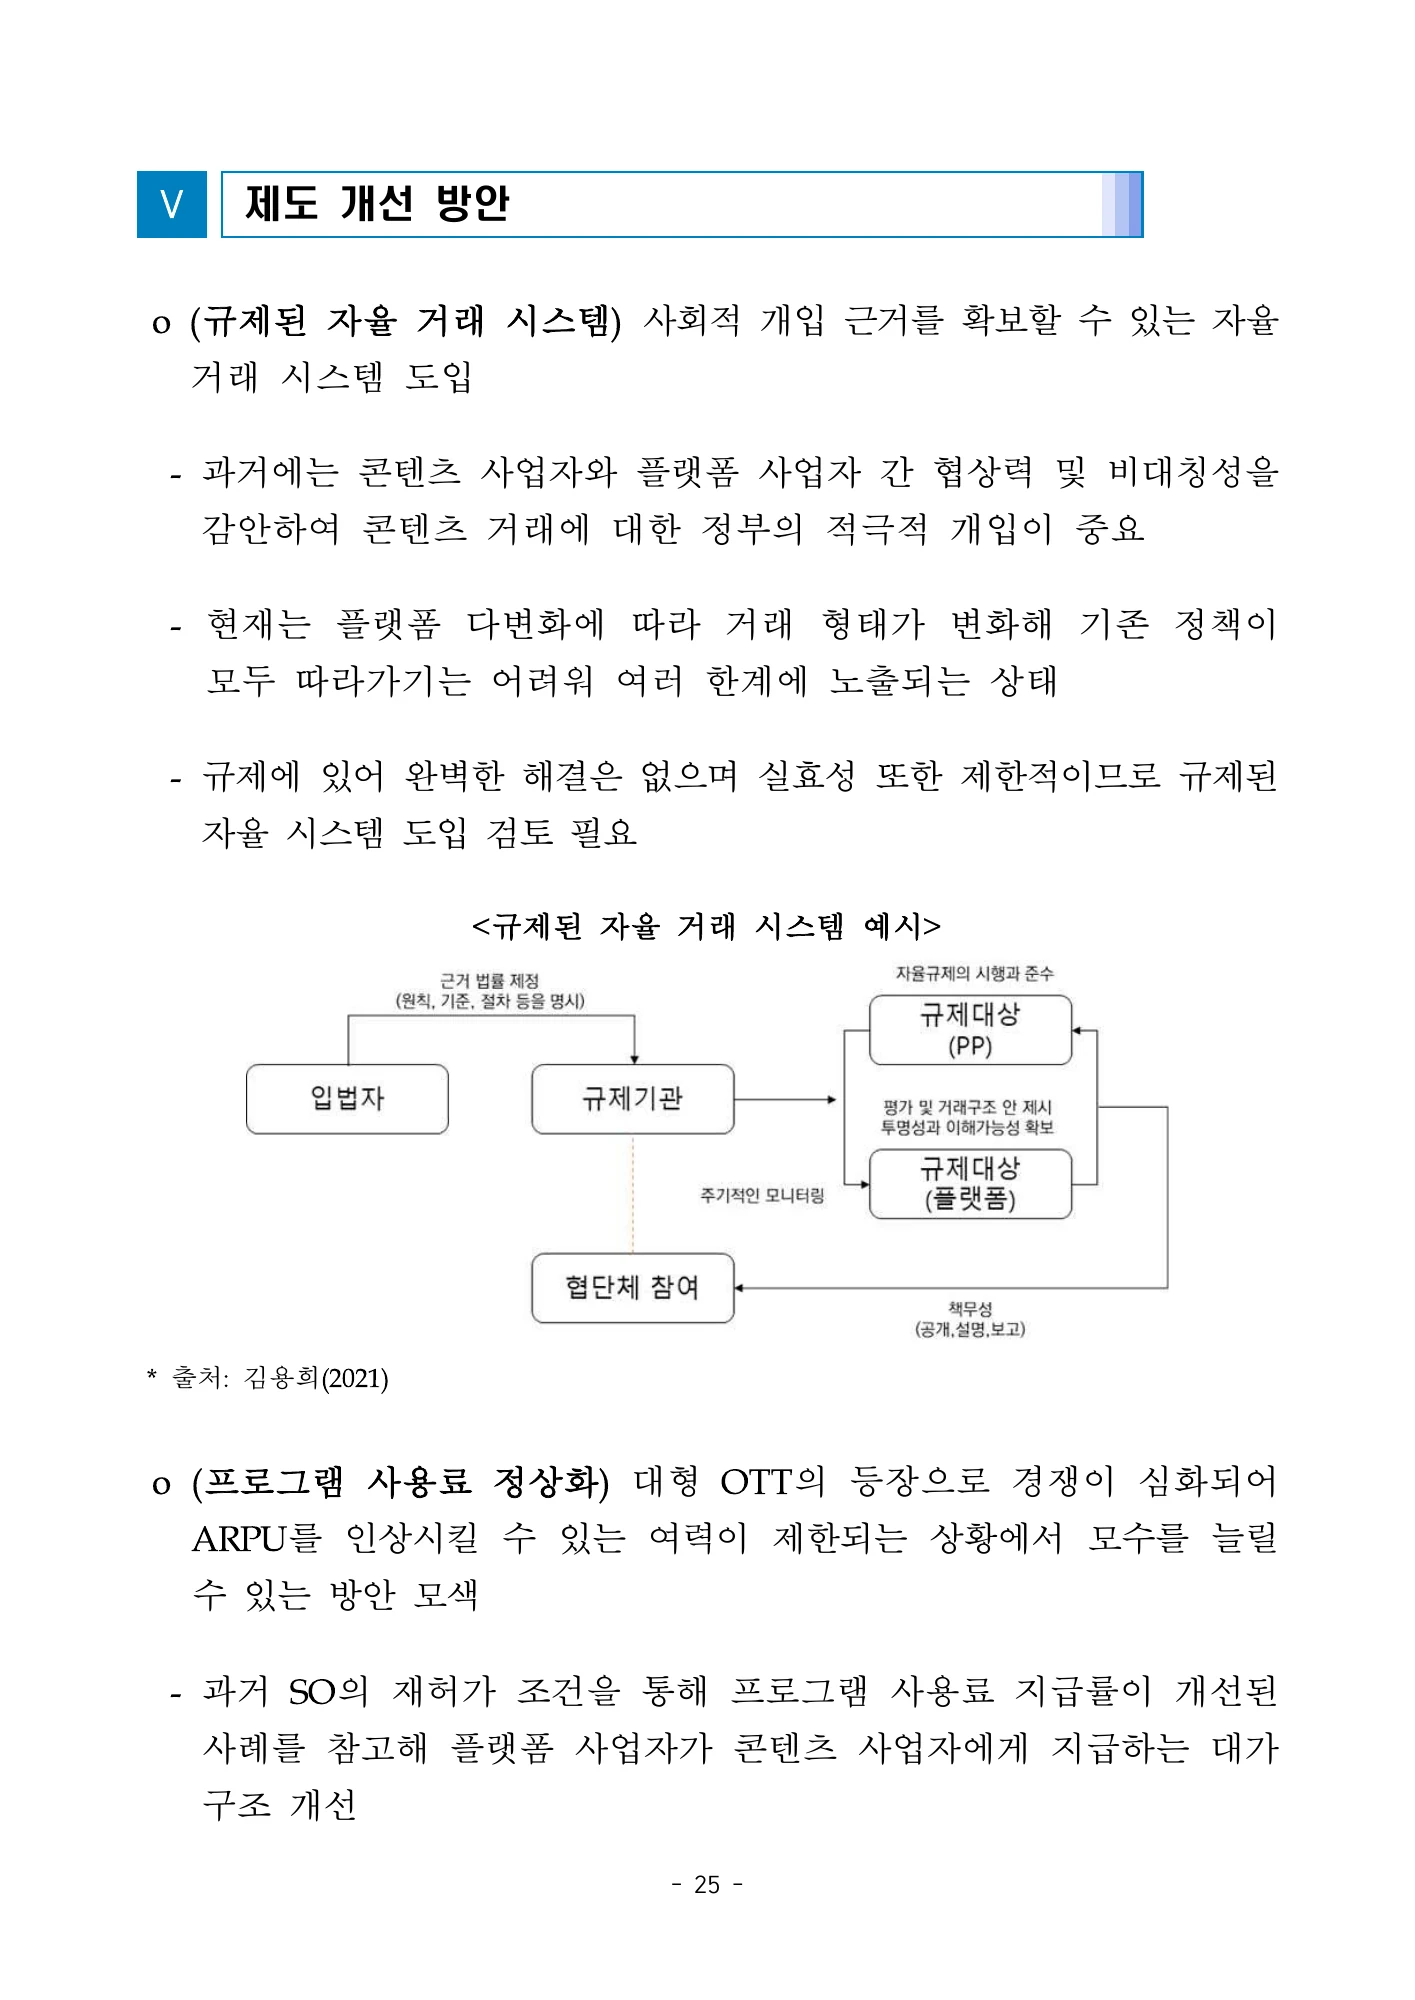
대안은 규제된 자율 거래, 프로그램 사용료 산정 모수의 확대, 플랫폼 성과 연동 배분, 동일 기준의 채널 평가, 분쟁 평가체계와 편성 자율성 강화다. 기본채널 수신료에 홈쇼핑 송출수수료 등을 더하거나 과거·미래 자료를 결합하는 구상도 제시한다. 최소 배분율 35~60% 등의 수치는 정책 검토안으로서 법정 의무나 도출된 유일 최적값이 아니다. 콘텐츠 지원에서는 당시 세액공제 확대를 주장하지만, 다른 국가 비율과 공제 대상을 그대로 같은 기준으로 비교할 수 없다는 한계를 함께 고려해야 한다.
Options include regulated autonomy, a broader remuneration base, performance-linked allocation, common channel-evaluation criteria, dispute processes and greater scheduling autonomy. Suggested formulas combine basic subscription revenue with other funding and historical with projected values. A proposed minimum allocation range of 35–60% is a policy option, not an established legal obligation or uniquely estimated optimum. The accompanying tax-support argument also requires care because international rates and eligible expenditure are not directly interchangeable.
PDF 파일 26, 27, 28, 29, 30, 31쪽PDF pages 26, 27, 28, 29, 30, 31
선계약·후공급과 평가 절차Contracting before supply and evaluation procedures
실행에서는 평가 기준을 공개하고 이해관계자가 수용할 분쟁 절차를 만들며 계약 만료 전에 다음 공급계약을 체결하는 예측 가능성을 강조한다. 표준계약서의 계약 종료 조항, 고의적 협상 지연에 대한 제재, 제도 정착을 위한 차년도 1분기 대안 등을 검토한다. 마지막 법안 비교표는 발의 내용을 정리한 것이므로 현행 법 조문으로 표시하지 않는다. 웹에서는 거래 단계별로 평가·협상·계약·공급·분쟁의 순서를 분리해 읽되, 개별 가격과 비밀 계약 자료가 없으면 적정 대가를 수치로 확정할 수 없음을 밝힌다.
Implementation centres on transparent evaluation, accepted dispute procedures and agreement on programme supply before the previous contract expires. The report discusses termination clauses, intentional negotiating delays and a transitional first-quarter option. Its final legislative comparison records proposed amendments, not necessarily enacted text. For the reader, evaluation, negotiation, contracting, supply and dispute handling are separate stages. Confidential contract-level data would still be needed to determine appropriate prices in specific transactions.
PDF 파일 30, 31, 32, 33쪽PDF pages 30, 31, 32, 33
외부 재원의 구성과 지급비율의 분모를 함께 읽기Read funding composition together with the ratio denominator
원문의 순유입 재원 표는 2015년 8조 400억원에서 2020년 9조 561억원으로 늘어난 합계를 보여준다. 그러나 항목별 방향은 다르다. 방송광고는 3조 4,736억원→2조 7,172억원으로 줄고 홈쇼핑 송출수수료는 1조 1,347억원→2조 295억원으로 커졌다. 전체 증가율만으로 콘텐츠 제작의 재원 여건이 개선됐다고 말하기 어려운 이유다. 이 집계는 원문이 선택한 네 항목의 합이며 방송산업의 모든 수입이나 실질 부가가치를 뜻하지 않는다.
The selected inflow total rises from KRW8.0400 trillion in2015 toKRW9.0561 trillion in2020, but its components move differently. Advertising falls fromKRW3.4736 trillion to2.7172 trillion, while home-shopping carriage fees increase from1.1347 trillion to2.0295 trillion. Aggregate growth therefore does not establish better production financing. This total comprises four source-selected categories, not all industry receipts or real value added.
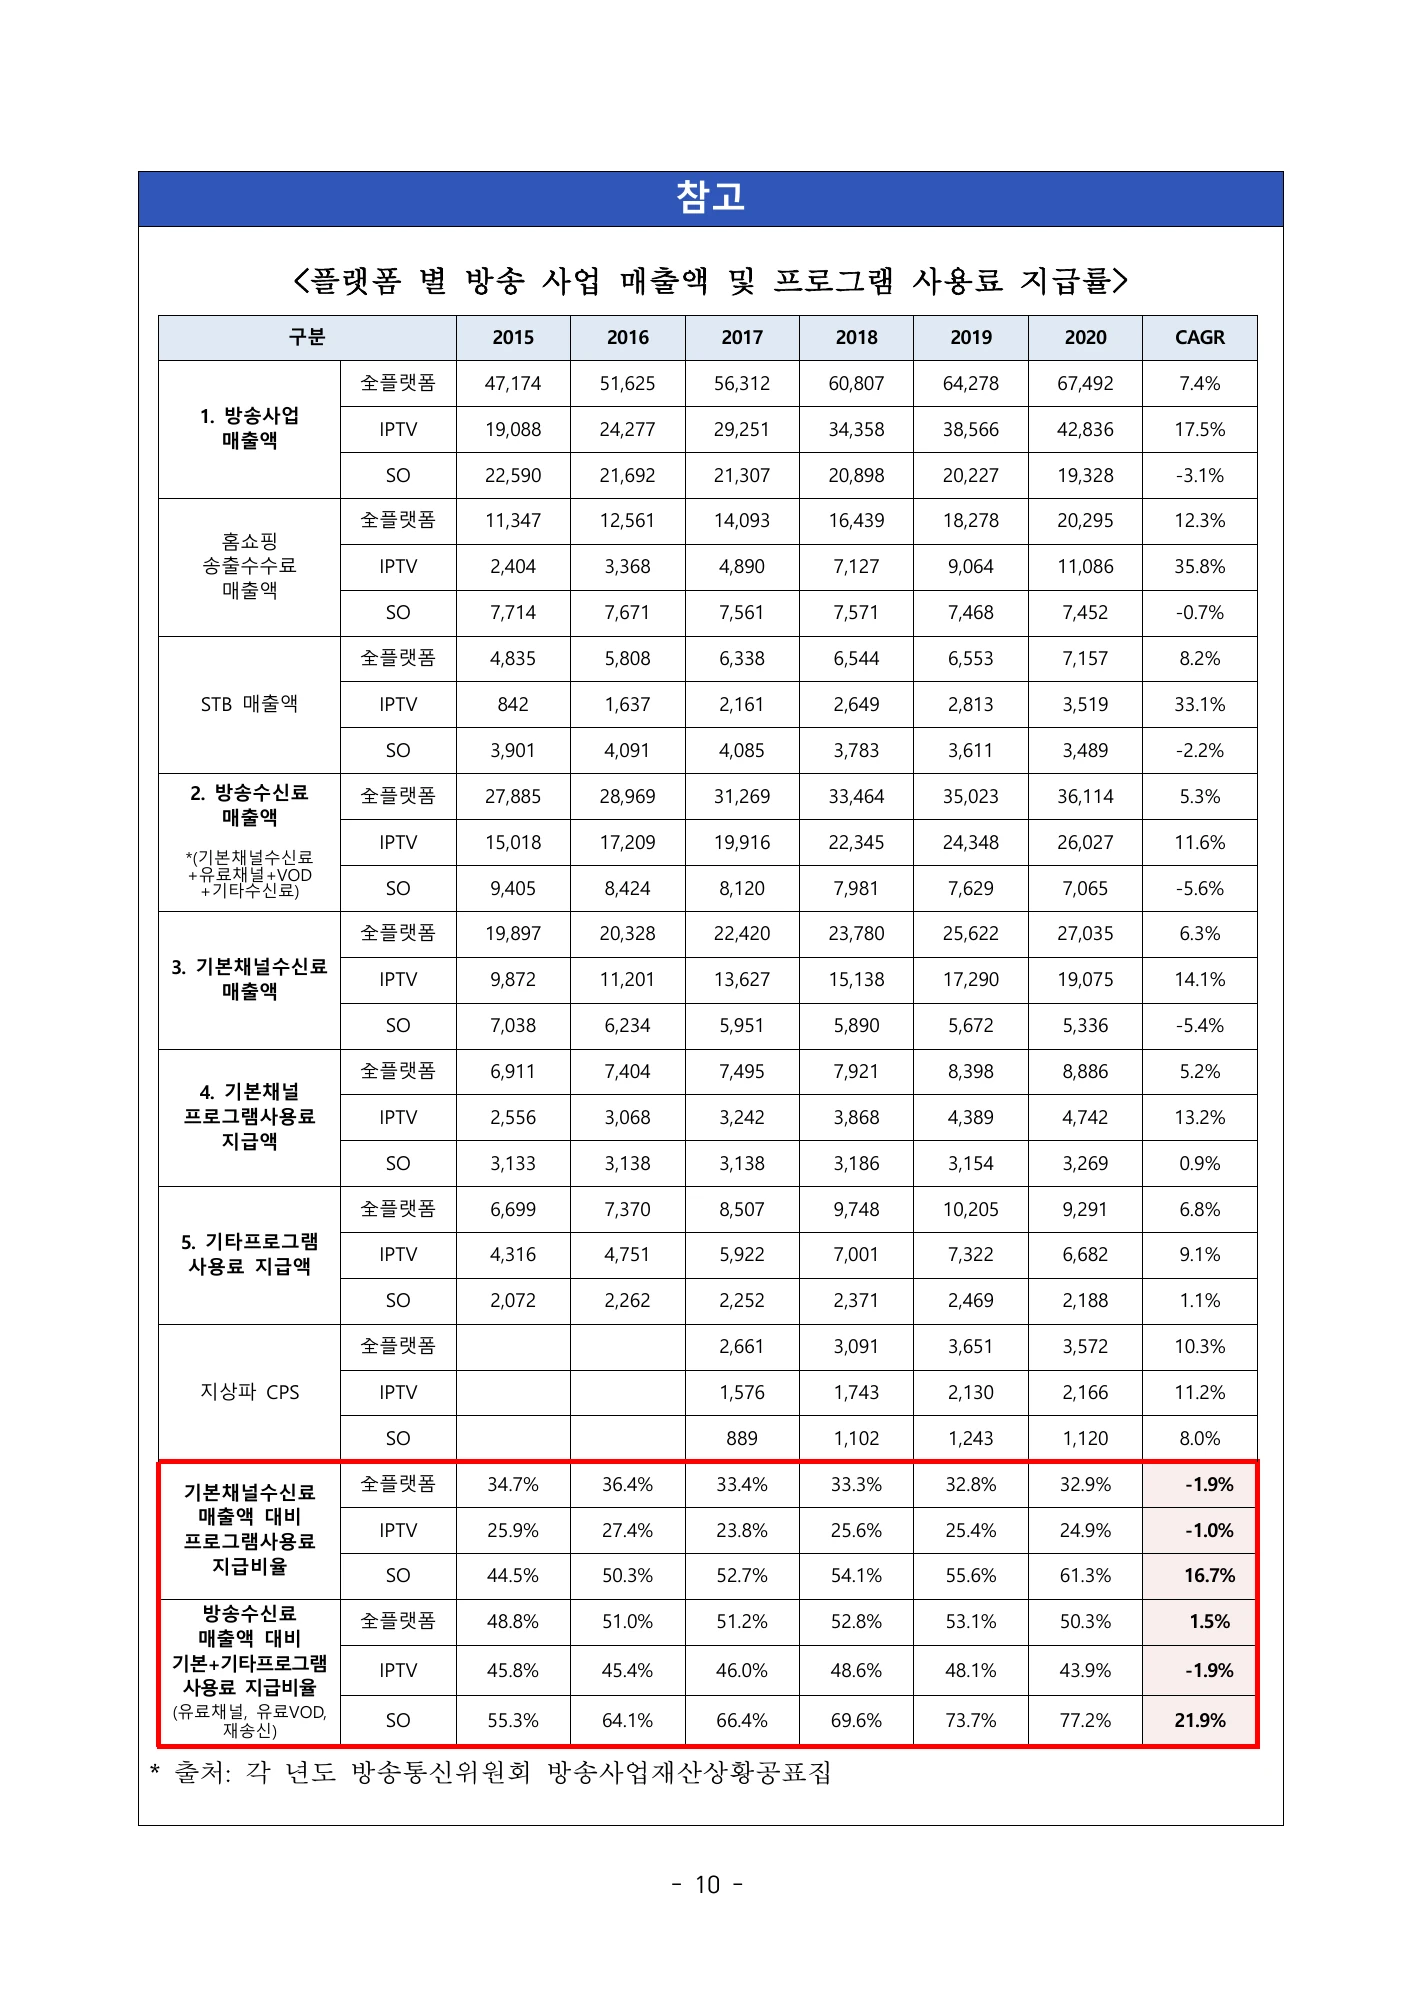
13쪽은 기본채널 수입 대비 기본채널 사용료와 전체 수신료 대비 기본·기타 사용료를 나란히 보여준다. 2020년 SO는 각각 61.3%와 77.2%, IPTV는 24.9%와 43.9%다. 뒤의 비율에는 유료채널·VOD·재송신 관련 사용료가 포함되어 범위가 넓다. SO 61.3%와 IPTV 43.9%를 직접 비교하면 분자와 분모를 모두 바꾸는 오류가 된다. 지급 총액, 배분율과 사업자 수익성을 각각 구분해야 거래 구조를 정확히 설명할 수 있다.
File p.13 shows basic fees/basic-channel revenue alongside basic-plus-other fees/total subscription revenue. For2020 these are61.3% and77.2% for cable,24.9% and43.9% for IPTV. The latter includes premium channels,VOD and retransmission payments. Comparing61.3% cable with43.9% IPTV changes both numerator and denominator. Amounts, allocation shares and profitability need separate treatment.
PDF 파일 7, 11, 12, 13쪽PDF pages 7, 11, 12, 13
자율협상에 평가의 투명성과 계약 완료 시점을 더하기Add transparent evaluation and clear deadlines to negotiation
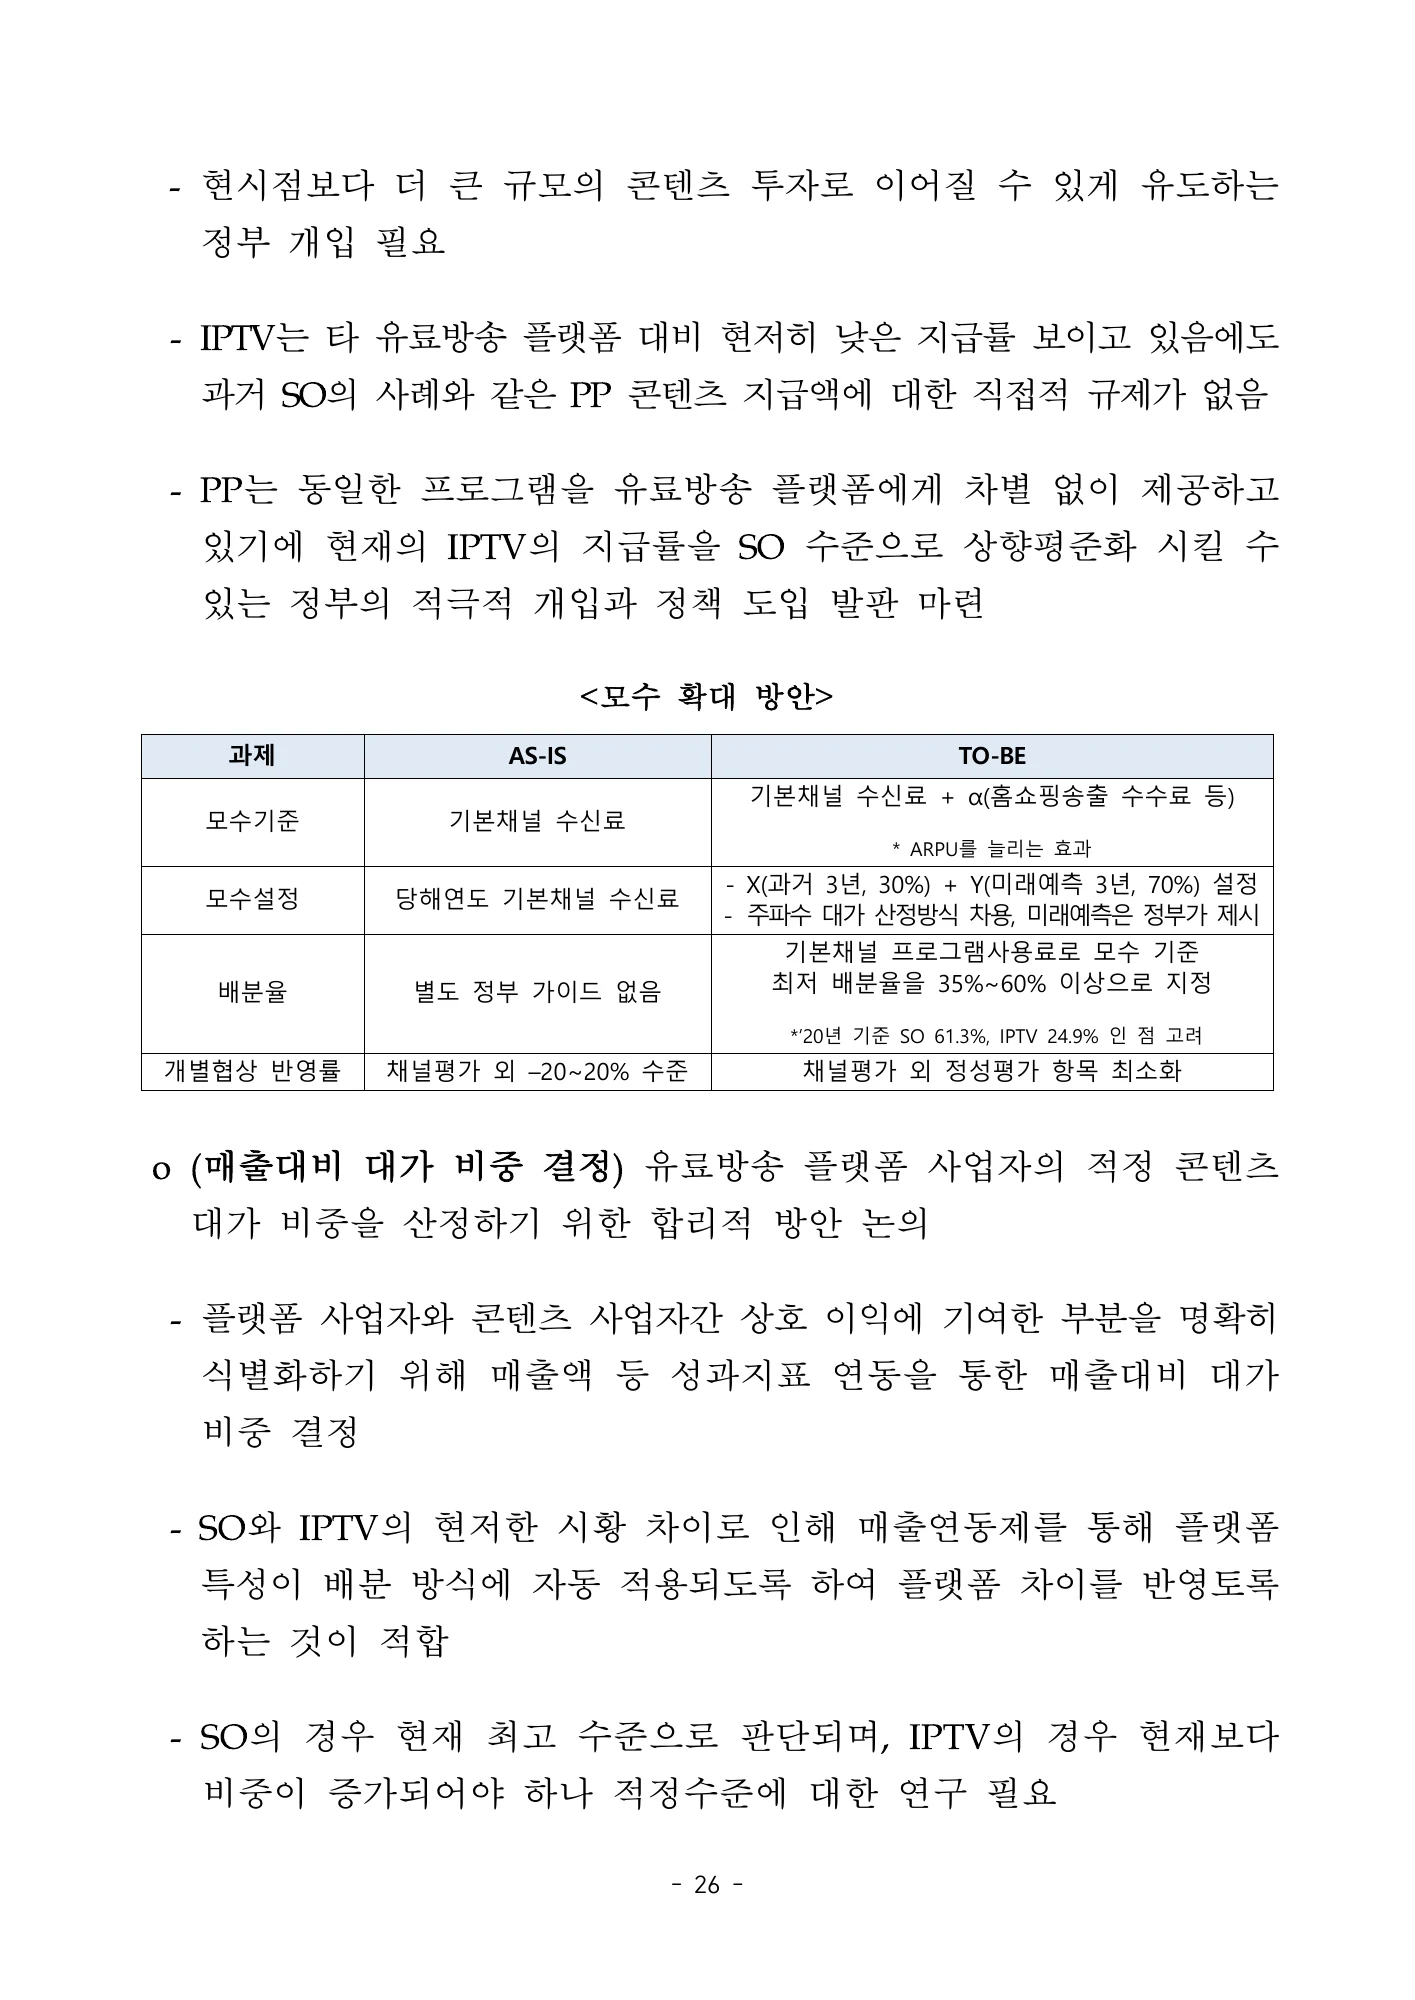
모수 확대안은 기본채널 수신료에 홈쇼핑 송출수수료 등 α를 더하고, 과거 3년 30%·미래 예측 3년 70% 같은 설정 예시를 제시한다. 최저 배분율 35~60% 이상도 검토안에 포함된다. 원문은 SO·IPTV의 시장 상황 차이를 반영할 매출 연동과 적정 비중의 추가 연구도 요구한다. 따라서 이 수치를 이미 합의된 정답으로 전달하지 않으며, 예측 주체·범위·정산 방식·위험 부담을 정해야 작동하는 정책 설계로 읽는다.
The proposed base adds an alpha component such as home-shopping fees to basic subscriptions and illustrates a30% past-three-year/70% forecast-three-year blend. Minimum allocations of35–60% or more are considered, alongside revenue linkage and further work on suitable shares for different platforms. These are not settled answers: forecast responsibility, scope, settlement and risk allocation still require design.
평가 측면에서는 지상파·보도·종편까지 공통의 원칙에서 비교하고 시청자 요구·자체제작·다양성·지역성을 반영하자고 제안한다. 분쟁이 생기면 평가 결과를 검토할 위원회가 필요하다고 본다. 계약 측면에서는 차년도 계약을 연내 완료하되 연착륙을 위한 1분기 인정 대안, 갱신 외 종료 사유와 고의 지연에 대한 제재를 검토한다. 채널 평가 점수가 곧 개별 콘텐츠의 시장가격이라는 뜻은 아니며 원문 후반의 발의안도 당시 입법 논의로 남겨 둔다.
Evaluation proposals apply common principles across terrestrial, news and general channels, considering demand, original production, diversity and locality, with a committee for contested evaluations. Contract proposals seek year-end completion, a possible first-quarter transition allowance, termination grounds and responses to deliberate delay. An evaluation score is not a market price for each programme, and the reproduced bills remain dated legislative proposals.
PDF 파일 28, 29, 30, 31, 32, 33쪽PDF pages 28, 29, 30, 31, 32, 33
핵심 결과를 표로 읽기Read the key results in tables
| 항목(억원)Measure (KRW 100m) | 2015 | 2020 |
|---|---|---|
| 방송 수신료Subscription revenue | 27,885 | 36,114 |
| 광고Advertising | 34,736 | 27,172 |
| 홈쇼핑 송출수수료Home-shopping carriage fees | 11,347 | 20,295 |
| KBS 수신료KBS licence fee | 6,432 | 6,980 |
| 합계Total | 80,400 | 90,561 |
원문 정의의 외부 유입 재원이다. 산업 내부 대가를 추가 합산하지 않는다.External inflows as defined by the source; internal programme payments must not be added again.
이 표를 읽는 방법How to read this table
표의 합계는 유료방송 수신료·방송광고·홈쇼핑 송출수수료·KBS 수신료를 더한 것이다. 2015~2020 연평균 증가율 2.41%는 이 명목 합계의 변화이며 물가를 제거한 실질 성장률이나 콘텐츠 투자액 증가율이 아니다.The total combines pay-TV subscriptions, advertising, home-shopping fees and KBS licence fees. Its2.41% compound annual growth for2015–2020 concerns that nominal total, not inflation-adjusted growth or production investment.
항목 간 구성 변화가 중요하다. 광고의 −4.79%와 홈쇼핑 송출수수료의 +12.33%는 서로 다른 규모에서 계산한 연평균 변화율이므로 단순 합산해 산업 성장률을 만들지 않는다. 같은 재원이 다른 사업자 매출로 다시 잡히는 내부 거래와도 구분한다.Composition matters. Advertising’s−4.79% and home-shopping’s+12.33% are compound rates on different bases; adding them does not produce industry growth. They must also be distinguished from internal transfers recorded as another firm’s revenue.
PDF 파일 7쪽PDF page 7
원문 해당 쪽에서 선별·재구성Selected and reconstructed from the cited source pages · PDF 파일 7쪽PDF page 7
| 플랫폼Platform | 2015 | 2020 |
|---|---|---|
| SOCable SO | 44.5% | 61.3% |
| IPTV | 25.9% | 24.9% |
전체 매출 대비 비율과 다르다. 44.5%→61.3%는 표시값 기준 16.8%p이며 원문 변화 행은 16.7%로 표기한다.These are not ratios to total revenue. Displayed cable values imply 16.8 percentage points, while the source change row states 16.7%.
이 표를 읽는 방법How to read this table
61.3%와 24.9%는 2020년 SO와 IPTV 각각의 기본채널 수신료를 분모로 한 비율이다. 2015년 SO 44.5%에서의 변화는 표시값으로 16.8%포인트지만 원문은 16.7%로 적어 반올림된 수치의 차이를 그대로 확정하지 않는다.The61.3% and24.9% values use each platform type’s2020 basic-channel subscription revenue. Cable’s displayed44.5% in2015 implies16.8 percentage points, while the source prints16.7%; the rounded presentation should not be treated as exact unrounded change.
투자 회수율 36.71%는 콘텐츠 사업자 투자비에 대한 프로그램 사용료의 비율로, 플랫폼 지급률과 분모가 다르다. 광고·협찬·다른 유통 수익이 포함된 전체 투자수익률이나 영업이익률로 바꾸어 읽지 않는다.The36.71% investment-recovery figure uses content investment as its denominator and differs from platform payment ratios. It is not total ROI including advertising, sponsorship and other distribution, nor an operating margin.
PDF 파일 12, 13쪽PDF pages 12, 13
원문 해당 쪽에서 선별·재구성Selected and reconstructed from the cited source pages · PDF 파일 12쪽PDF page 12
핵심 수치를 그래프로 읽기Read the key numbers visually
동일 연도·동일한 기본채널 수입 기준에서 플랫폼 유형별 지급비율을 비교한다.Compares platform types within the same year and basic-channel revenue definition.
단위: Unit: %
원문 12·13쪽. 각 유형의 기본채널 수신료가 분모다. 기업규모·수익성·인과효과를 통제한 비교는 아니다.Source file pp.12–13. Each type’s basic-channel subscription revenue is the denominator. This does not adjust for scale, profitability or causal effects.
원문 수치 재구성 · PDF 12, 13쪽Re-presented source values · PDF pages 12, 13
원문의 핵심 표·그래프Key tables & figures in the source
표·그림이 수록된 원문 페이지입니다. 이미지를 누르면 확대할 수 있습니다.Original pages containing the selected tables or figures. Select an image to enlarge it.
방송시장 외부 유입 재원 추이Trends in external market funding
제작투자 회수와 플랫폼 지급률Production recovery and platform payment ratios
플랫폼별 매출과 두 종류의 사용료 지급률Platform revenue and two payment-ratio definitions
규제된 자율 거래 시스템의 제안Proposed regulated self-governed trading system
사용료 산정 모수 개선안Proposals to revise the payment base
정책 제안과 검증된 성과의 경계Distinguishing recommendations from verified outcomes
핵심 근거는 회계·시장 자료의 재가공과 제도 비교이며 특정 개편을 실험한 자료가 아니다. 지급률 변화는 퍼센트포인트와 상대 증가율을 구분해야 하고, 해외 기업의 평균도 단순 평균인지 매출 가중 평균인지 확인해야 한다. 사용료를 늘렸을 때 가입자 가격·사업자 투자·시청자 후생이 어떻게 변하는지까지 본 보고서가 검증한 것은 아니다. 따라서 대가 현실화가 필요하다는 원문 판단과 이를 실행할 구체 방식의 효과를 분리한다. 이 구분은 제도 제안의 논거를 보존하면서도 후속 재검증에 필요한 자료를 드러낸다. 계약 자료의 공개가 제한된 상황에서는 표의 회계 항목과 추정 여부를 유지하는 것이 중요하다. 낮은 평균 회수율을 모든 개별 콘텐츠가 손실이라는 의미로 일반화할 수도 없다.
The evidence consists chiefly of reworked accounting and market data and institutional comparison, not an experiment with the proposed reforms. Percentage-point changes differ from relative growth, and international averages require clarity about weighting. The report does not establish how greater payments would affect retail prices, investment or viewer welfare. Its normative case for revised remuneration is therefore separated from evidence about any particular mechanism’s effects, preserving both the argument and the need for subsequent validation. With limited contract disclosure, accounting definitions and estimation status remain essential. A low average recovery ratio does not imply that every individual programme is loss-making.
PDF 파일 10, 12, 19, 22, 29, 32, 33쪽PDF pages 10, 12, 19, 22, 29, 32, 33
근거 쪽: Evidence pages: 2, 3, 4, 5, 6, 7, 8, 9, 10, 11, 12, 13, 14, 15, 16, 17, 18, 19, 20, 21, 22, 23, 24, 25, 26, 27, 28, 29, 30, 31, 32, 33 · PDF 파일 기준, 인쇄 쪽수와 다를 수 있습니다. · PDF file pagination may differ from printed page numbers.
근거와 검토 범위Source and review scope
33쪽의 제공된 원문 자료를 기준으로 본문·표·선정 이미지를 확인했습니다. 해설은 연구 내용을 새 문장으로 정리했으며, 실제 원문 페이지를 함께 실었습니다. 분석 결과의 독립 재현이나 기관의 공식 입장 확인을 뜻하지 않습니다.
The text, tables and selected images were checked against the 33-page source document supplied for this site. This guide is an editorial summary accompanied by original source pages. This does not imply independent replication or institutional endorsement.
확인한 PDF 쪽: Source PDF pages: 1, 2, 3, 4, 5, 6, 7, 8, 9, 10, 11, 12, 13, 14, 15, 16, 17, 18, 19, 20, 21, 22, 23, 24, 25, 26, 27, 28, 29, 30, 31, 32, 33