정책·산업 자료 · 원문 해설Policy & industry material · Source-based guide
LG 헬로비전을 둘러싼 미디어 산업 현황 및 정책제안Media Industry Conditions and Policy Proposals Relating to LG HelloVision
원문에서 김용희의 구체적인 참여 역할은 확인 중입니다.Yonghee Kim’s specific contribution is still being checked against the source.
연구 내용Overview
유료방송과 OTT의 시장 변화, 콘텐츠 대가 거래와 이해관계자별 입장, 지역성과 공적 책무를 반영한 정책 방향을 정리한 자료다. 제목에 기관명이 있으나 개인 연구진과 정식 발주 관계는 확인되지 않았다.
Material reviewing pay-TV and streaming-market changes, content-payment negotiations and stakeholder positions, and policies addressing local services and public responsibilities. The title names LG HelloVision, while individual authorship and commissioning status remain unconfirmed.
원보고서의 문제의식·분석·제안을 정리한 해설입니다. 수치는 표시한 표와 쪽을 기준으로 읽습니다. 아래 표는 핵심 항목을 웹에서 읽도록 재구성했고, 원문 표·그림이 있는 페이지를 함께 제공합니다.This reading guide explains the report’s questions, analyses, and proposals in new wording. Tables below re-present selected source results for web reading, alongside images of the relevant original pages.
핵심부터 읽기Start with the main findings
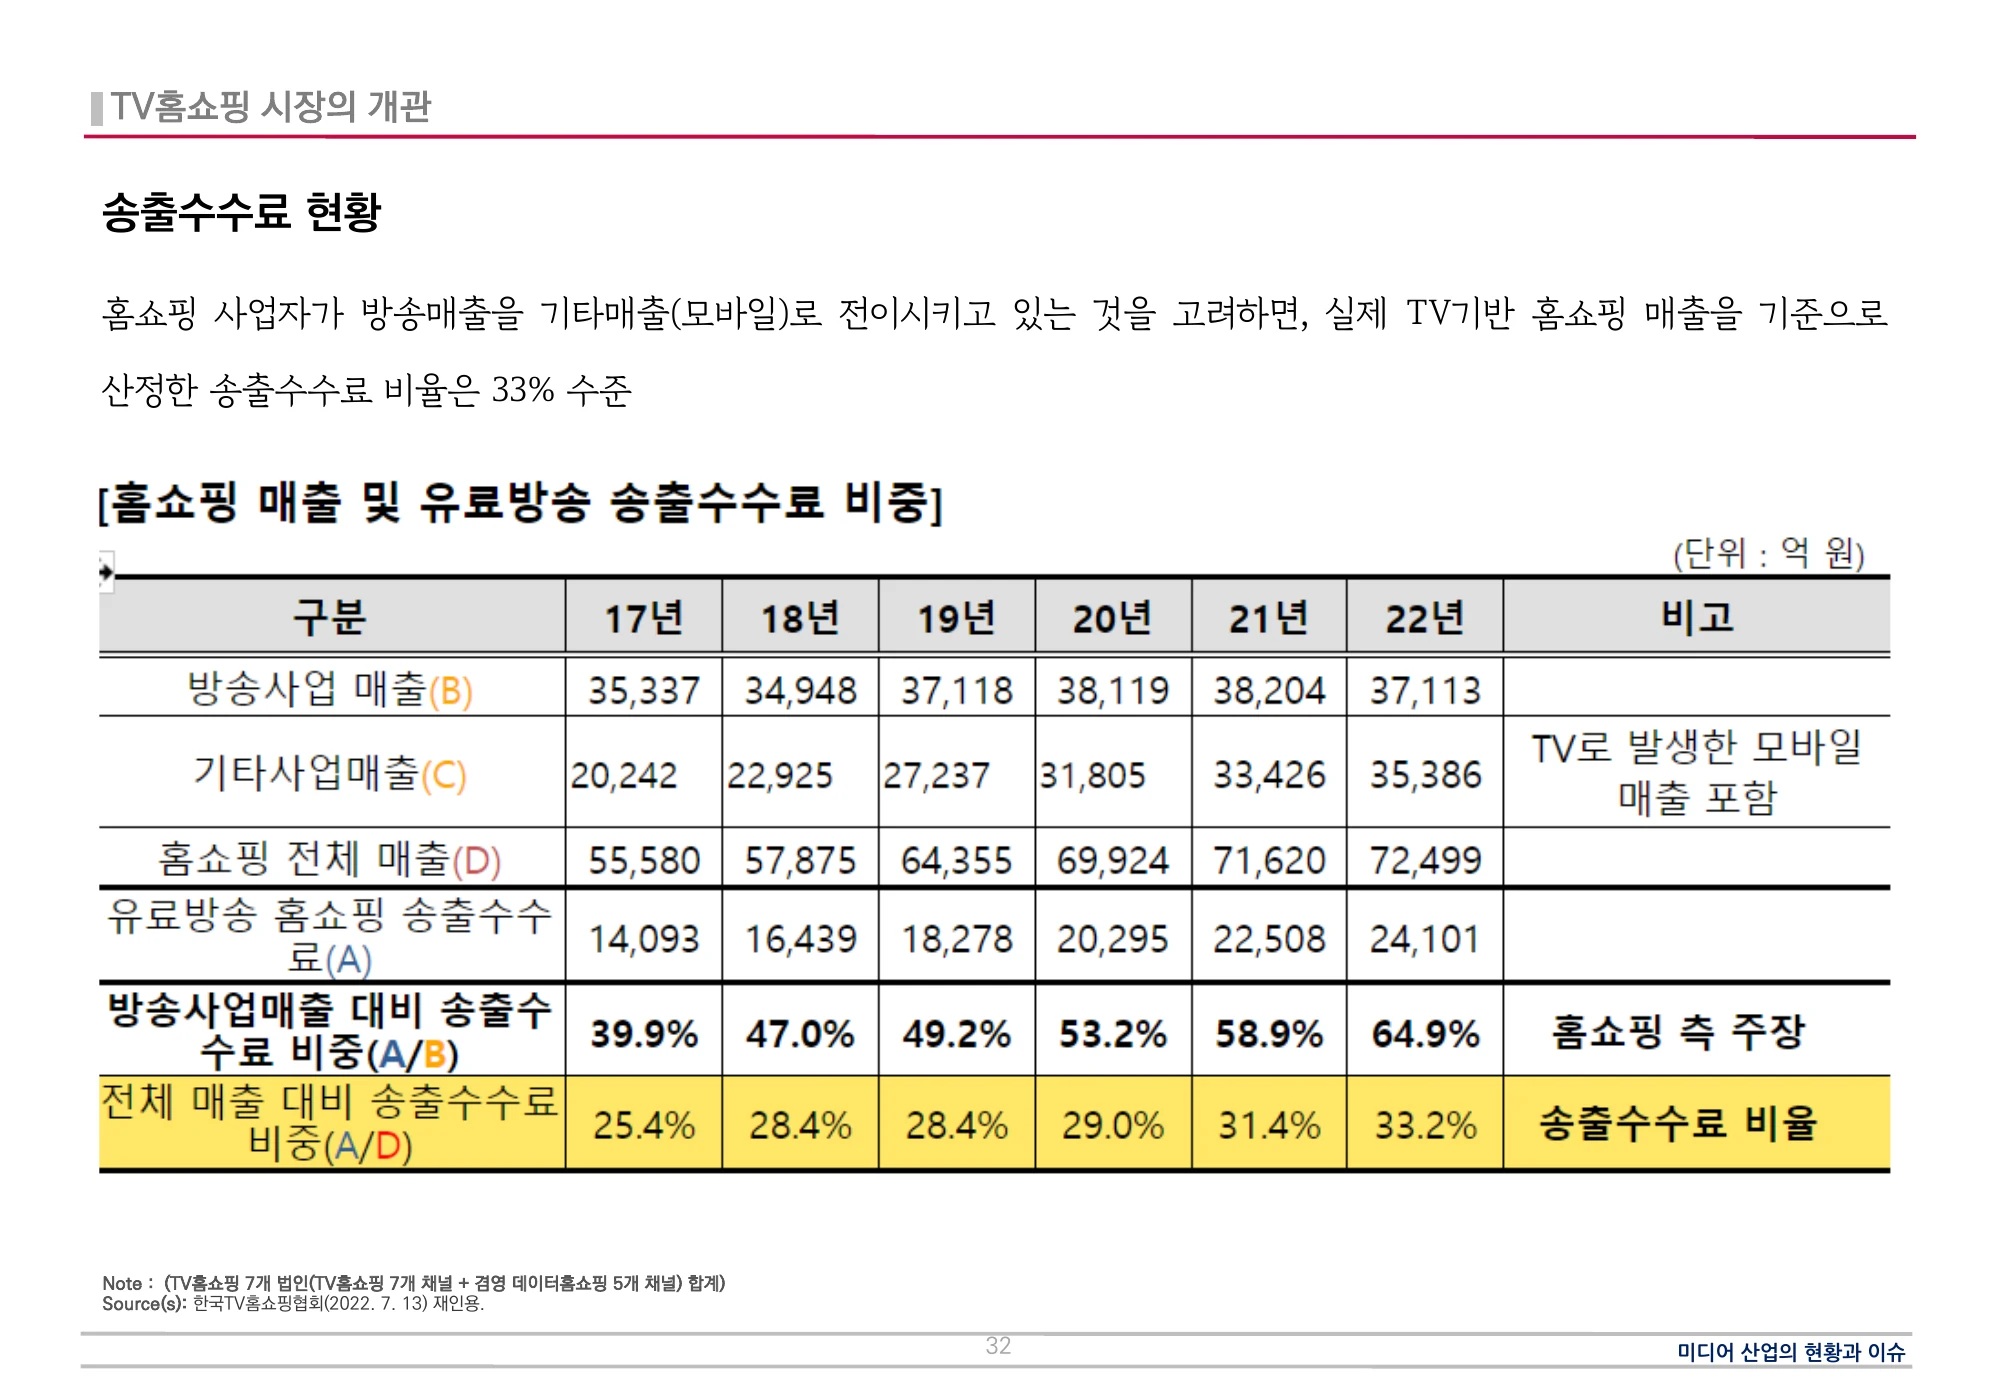
- 발표자료의 중심은 케이블 사업자의 매출 감소를 한 기업 문제로만 보지 않고 홈쇼핑·채널·OTT·기기의 거래관계 속에서 읽는 것이다. 홈쇼핑 송출대가와 콘텐츠 사용료는 돈의 방향이 다르고 매출 기준도 달라, 비율 하나로 어느 쪽이 공정한지 결론 내리기 어렵다.The presentation reads cable economics through its transactions with home shopping, channels, OTT and devices. Carriage fees and content payments flow in different directions and use different revenue bases, so one ratio cannot settle fairness.PDF 파일 31, 32, 34, 35, 69, 70, 71, 72쪽PDF pages 31, 32, 34, 35, 69, 70, 71, 72
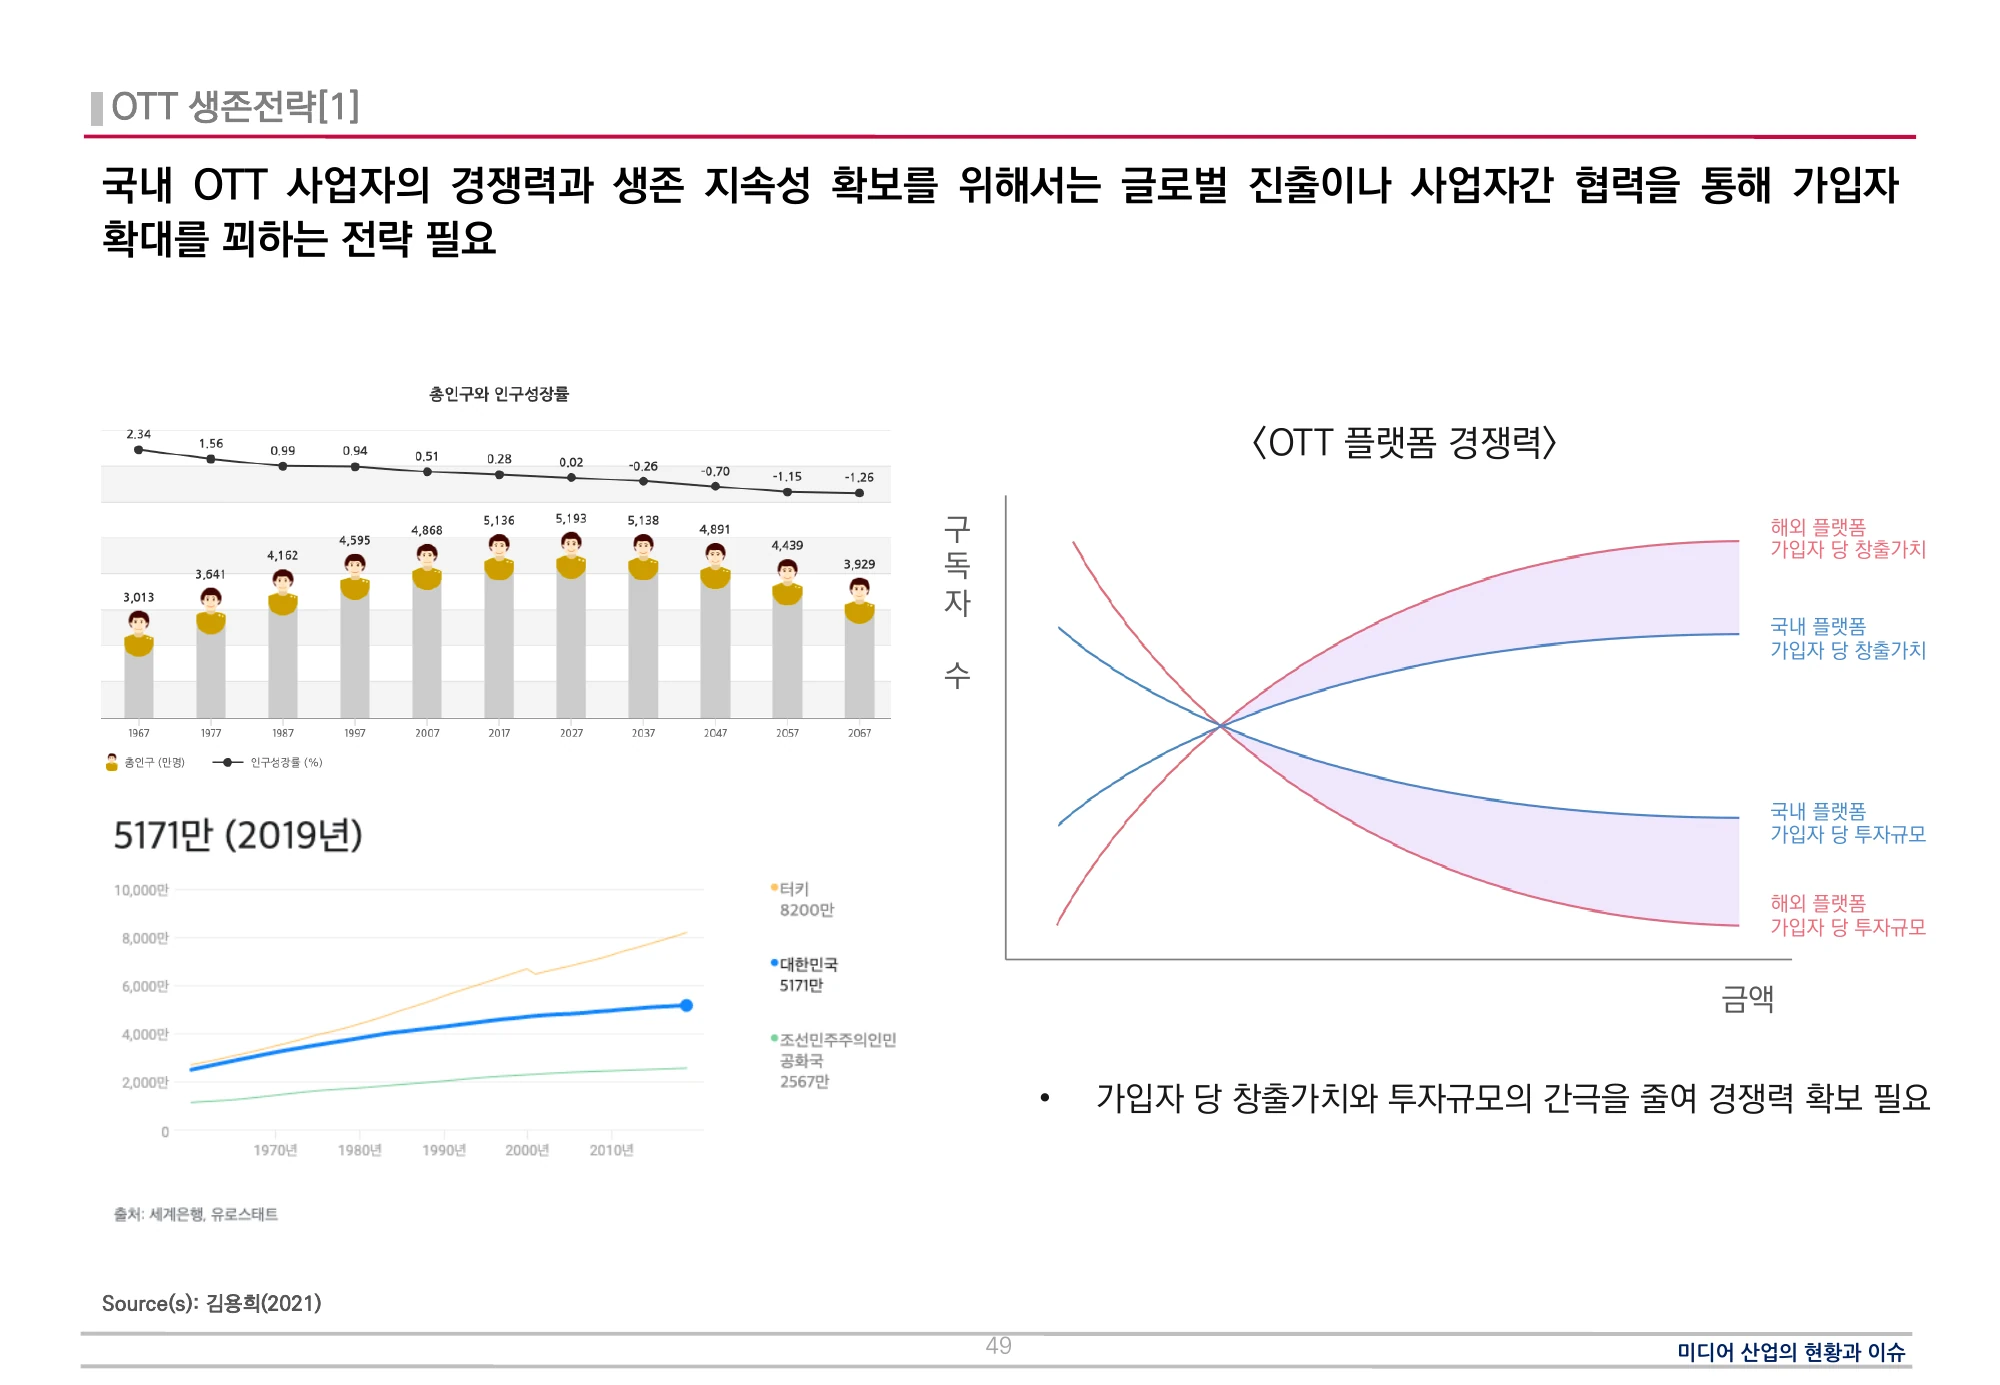
- OTT 협력안은 가입자 수 확대 자체보다 가입자당 창출 가치와 투자 규모의 간극을 줄이는 데 초점을 둔다. 플랫폼별 이용자 수나 중복 이용 합계가 곧 고유 유료가입자 수·수익성이 되는 것은 아니며, 자료의 전략 그림도 실측 수익함수가 아닌 개념도다.The OTT strategy focuses on the gap between value generated and investment per subscriber. Users, overlapping service totals and paying unique subscribers differ. The strategic diagram is conceptual, not an estimated profit function.PDF 파일 45, 49쪽PDF pages 45, 49
- ESG 제안은 환경 주제 프로그램 제작에 머무르지 않고 실제 제작 공정·계약·지역성과 공급망 배출까지 연결한다. 측정·검증을 위한 민관협력과 재정적 유인을 제안하지만 감경·세액공제가 시행되어 효과를 냈다고 보고한 자료는 아니다.ESG proposals extend from programme themes to production processes, contracts, local responsibilities and supply-chain emissions. Public–private measurement and incentives are proposed, not evaluated as enacted and effective.PDF 파일 80, 85, 86, 87쪽PDF pages 80, 85, 86, 87
케이블 사업자의 문제를 미디어 가치사슬 전체에서 읽기Read cable operators within the whole media value chain
이 발표자료는 LG헬로비전을 둘러싼 환경을 방송시장, 홈쇼핑, OTT, 새로운 플랫폼, 방송통신발전기금, 콘텐츠 이용대가, ESG라는 일곱 축으로 분석한다. 케이블 가입자나 방송 매출만 보는 대신 플랫폼이 콘텐츠를 전달하고 콘텐츠가 가입자를 끌어오는 상호의존 구조를 출발점으로 삼는다. 유료방송의 저가 구조, 거래대가의 배분, 신규 플랫폼과의 경쟁이 서로 연결돼 있다는 문제의식이다. 제목에 특정 기업이 등장하지만 모든 주장이나 제안을 그 기업의 공식 입장 또는 확정된 정책으로 읽어서는 안 된다.
The presentation examines the environment around LG HelloVision through seven connected areas: broadcasting, home shopping, OTT, emerging platforms, the development fund, content payments, and ESG. Its starting point is mutual dependence: platforms deliver content, while content attracts audiences. Low subscription prices, the distribution of transaction revenue, and competition from new platforms therefore belong to one value chain. The company named in the title does not make every argument an official corporate position or an adopted policy.
PDF 파일 1, 3, 28, 39, 57, 60, 68, 75쪽PDF pages 1, 3, 28, 39, 57, 60, 68, 75
통계·시장 전망·이해관계자 주장을 구분한 자료Distinguish statistics, forecasts, and stakeholder positions
방송사업실태조사와 방송시장 경쟁상황평가, 사업자 재무자료, 모바일인덱스 이용 통계, S&P Global과 Statista의 시장자료, 기존 연구·발표를 종합한 정책 발표자료다. 자체 실험이나 새로 추정한 인과모형은 아니다. 가입계정 수와 실제 시청자 수, 매출과 영업이익, 기본채널 수신료와 홈쇼핑 수수료는 서로 다른 지표다. 2022년 현황, 2023년까지의 이용 통계, 2028년을 대상으로 한 당시 전망이 함께 있으므로 각 도표의 연도·집계범위를 유지해 읽어야 한다.
The evidence combines official broadcasting statistics and competition assessments, financial statements, MobileIndex usage figures, S&P Global and Statista material, and earlier studies. This is a policy synthesis rather than a new experiment or causal estimation. Subscription accounts differ from individual viewers; revenue differs from profit; basic-channel fees differ from home-shopping carriage fees. The slides mix historical observations with forecasts made at the time, so a chart’s date, denominator, and evidence type matter as much as its headline.
PDF 파일 4, 5, 8, 12, 16, 18, 42, 45쪽PDF pages 4, 5, 8, 12, 16, 18, 42, 45
방송시장: 포화와 수익구조의 분화Broadcasting: saturation and diverging revenue structures
자료는 유료방송 가입 증가의 둔화와 IPTV·SO의 서로 다른 경영 경로를 함께 제시한다. 가구 수보다 가입계정 수가 많은 현상은 병원·호텔 등의 복수가입을 포함하므로 보급률을 단순한 개인 이용률로 바꾸면 안 된다. SO의 매출·이익 감소와 IPTV의 성장, VOD 수익 약화, 낮은 ARPU를 비교하며 가입 규모만으로 협상력이나 수익성을 판단하기 어렵다고 설명한다. 한편 규제가 강해서 ARPU가 낮다는 주장은 자료 안에서도 추가 연구가 필요한 가설로 제시된다.
The slides pair slowing subscription growth with different financial trajectories for IPTV and cable. Accounts exceeding household counts partly reflect multiple subscriptions and business customers, so they cannot be converted directly into individual penetration. Declining cable revenue and margins, IPTV growth, weaker VOD revenue, and low ARPU are considered together. Subscription scale alone cannot summarize bargaining power or profitability. Importantly, the proposed association between heavier regulation and lower ARPU is presented as a hypothesis for further study, not an identified causal result.
PDF 파일 8, 9, 11, 12, 13, 14, 15, 16, 17, 18쪽PDF pages 8, 9, 11, 12, 13, 14, 15, 16, 17, 18
홈쇼핑: 거래대가의 기준과 정보 비대칭Home shopping: pricing rules and asymmetric information
홈쇼핑 부문에서는 방송 취급고의 정체·감소와 모바일 구매 유도, 플랫폼별로 다른 협상구조를 짚는다. 송출수수료 비율은 방송 매출만 분모로 삼는지 TV가 유도한 모바일 매출까지 포함하는지에 따라 달라진다. 자료는 가입자·시청률 정보와 홈쇼핑의 채널별 실적 정보 사이의 검증 가능성 차이를 문제로 본다. 개선안은 합리적인 대가 검증, 임의 감액이나 일방적 송출 중단에 대한 규칙, 정부의 분쟁 중재와 상설 발전협의체다. 이는 자료가 제안한 방향이며 실제 분쟁에 관한 확정 판단은 아니다.
For home shopping, the presentation links stagnant television sales, efforts to shift purchasing toward mobile channels, and platform-specific bargaining conditions. A carriage-fee ratio changes depending on whether its denominator includes only reported broadcast revenue or television-influenced mobile purchases. The report emphasizes unequal access to verifiable transaction information. Proposed responses include evidence-based price checks, rules addressing unilateral reductions or threatened service interruptions, mediation, and a standing industry forum. These remain the presentation’s policy proposals rather than findings adjudicating a particular dispute.
PDF 파일 31, 32, 34, 35, 36, 37, 38쪽PDF pages 31, 32, 34, 35, 36, 37, 38
OTT: 가입자 확대에서 협력·차별화 전략으로OTT: cooperation and differentiation beyond scale
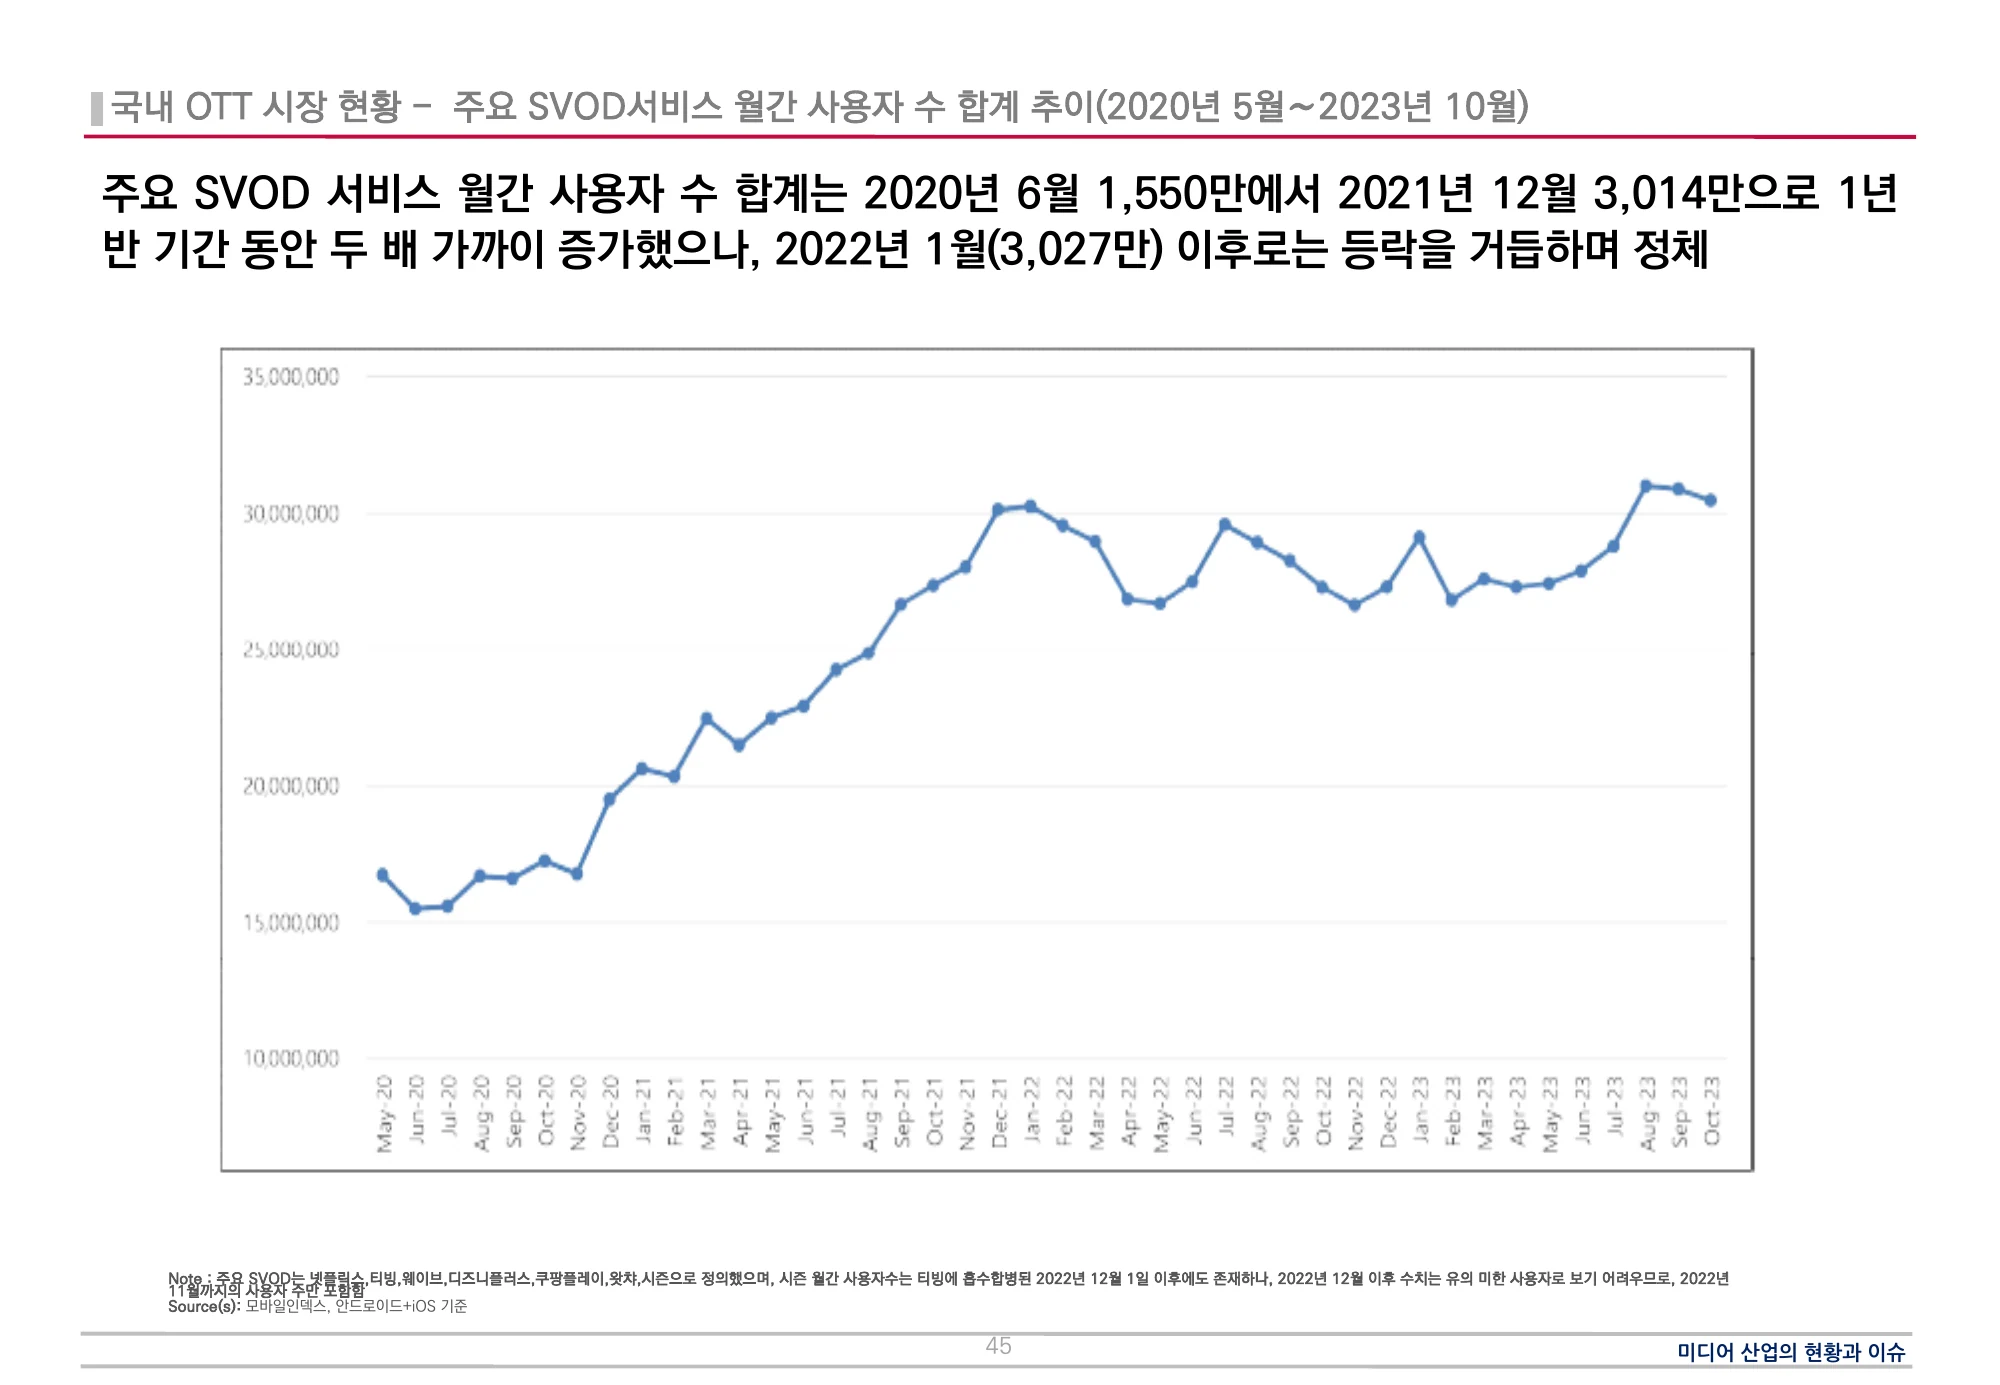
OTT 부문은 세계 시장의 구독자 전망과 국내 서비스의 실제 이용 추이를 구분한다. 국내 주요 SVOD 월간 이용자 수 합계는 자료상 2020년 6월 1,550만에서 2021년 12월 3,014만으로 늘었으나, 이후에는 등락과 정체가 나타난다. 여러 서비스 이용자를 더한 값이어서 고유 이용자 수가 아니다. 생존 전략으로는 글로벌 진출, 서비스 간 결합과 제휴, 명확한 고객층을 겨냥한 전문 OTT를 제시한다. 구독자당 투자와 창출가치의 간극을 줄이는 것이 핵심이며 단순히 가입자를 늘리는 처방으로 축약하지 않는다.
The OTT section separates global subscription forecasts from observed domestic usage. The sum of monthly users across selected Korean SVOD services rises from 15.50 million in June 2020 to 30.14 million in December 2021, followed by fluctuation and stagnation. This sum double-counts people using multiple services. Suggested strategies include international reach, partnerships and bundling, and specialty services with clear audiences. The underlying question is how to narrow the gap between investment and value generated per subscriber, rather than pursuing subscriber totals in isolation.
PDF 파일 42, 45, 49, 52, 56쪽PDF pages 42, 45, 49, 52, 56
새 기기와 결합 서비스가 흔드는 규제 경계New devices and hybrid services challenge regulatory boundaries
자율주행차의 미디어 이용, 메타버스 안의 영상서비스, 쇼퍼블 TV를 사례로 기존 매체별 법체계의 경계 문제를 제기한다. 같은 영상이 게임·방송·통신·커머스의 여러 틀에 걸칠 때 이용자가 어떤 서비스를 소비하는지에 초점을 맞춘 정의가 필요하다는 주장이다. 자동차 2천만 대에 운행시간 1.5시간을 곱한 예시는 잠재 시간의 가정 계산이지 실제 광고시장 규모나 시청시간의 실측값이 아니다. 새로운 기기가 곧바로 수익성 있는 시장이 된다고 단정하지 않는다.
Examples include media consumption in autonomous vehicles, video inside virtual worlds, and shoppable television. Hybrid services may cross legal categories built around separate media. The presentation argues for examining what audiences consume rather than relying only on device labels. Its multiplication of 20 million vehicles by 1.5 hours illustrates a hypothetical pool of available time; it is neither measured viewing nor an advertising-revenue estimate. New devices therefore represent strategic and regulatory questions, not demonstrated profitable markets.
PDF 파일 58, 59쪽PDF pages 58, 59
방발기금: 산정기준·공적책무·운용의 논의The fund: assessment bases, public duties, and governance
기금 장에서는 사업군별 부과 모수가 광고매출·방송서비스 매출·영업이익으로 다르다는 점과 감경 원칙·사용처의 정합성을 다룬다. 종편, 케이블, IPTV의 주장을 나란히 보여주며 감경률의 형평성, 지역채널과 공적책무 비용, 특정 사업군에 대한 재원 의존을 논점으로 정리한다. 플랫폼 간 시장 상황이 달라졌다는 문제의식에서 차등 기준과 인센티브를 검토하지만, 자료에 적힌 요율과 부과 범위는 작성 당시의 제도·논의다. 현행 법령이나 소관기관의 확정 해석을 제공하는 페이지는 아니다.
The fund section distinguishes advertising revenue, broadcasting-service revenue, and operating profit as assessment bases for different business groups. It compares stakeholder positions on reductions, local-channel obligations, the use of proceeds, and dependence on particular contributors. Different market conditions motivate discussion of differentiated treatment and incentives. However, the rates, institutional divisions, and proposals are historical material from the presentation. They should not be treated as a current-law calculator or an authoritative interpretation from the administering institution.
PDF 파일 61, 64, 65, 66, 67쪽PDF pages 61, 64, 65, 66, 67
콘텐츠 대가: 분모와 범위가 다른 비교Content payments: compare like denominators and scopes
콘텐츠 대가 장은 프로그램 사용료와 지상파 재송신료의 변화, PP·종편과 플랫폼의 상반된 입장을 정리한다. 콘텐츠 가치를 반영한 배분 확대 요구와 선계약 후공급·협상 일정의 상호 이행 요구를 함께 제시한다. 특히 일반 PP만의 프로그램 사용료 비중과 지상파 재송신료까지 합산한 비중은 서로 다르다. 분배율을 올렸을 때 확보된다고 제시한 금액 역시 조건부 시나리오이며 이미 지급된 재원은 아니다. 어느 한쪽 주장만을 산업 전체의 합의로 소개하지 않는다.
The content-payment section tracks program fees and terrestrial retransmission payments while contrasting content-provider and platform positions. Calls for a larger value-based share appear alongside demands for reciprocal compliance with contracts and negotiation schedules. Ratios for general PP fees differ from ratios that also include terrestrial retransmission payments. Additional resources calculated under higher payment shares are conditional scenarios, not money already distributed. The competing viewpoints are preserved instead of being presented as an industry-wide agreement.
PDF 파일 69, 70, 71, 72, 73, 74쪽PDF pages 69, 70, 71, 72, 73, 74
ESG: 콘텐츠 주제를 넘어 제작과 공급망으로ESG: beyond program themes to production and supply chains
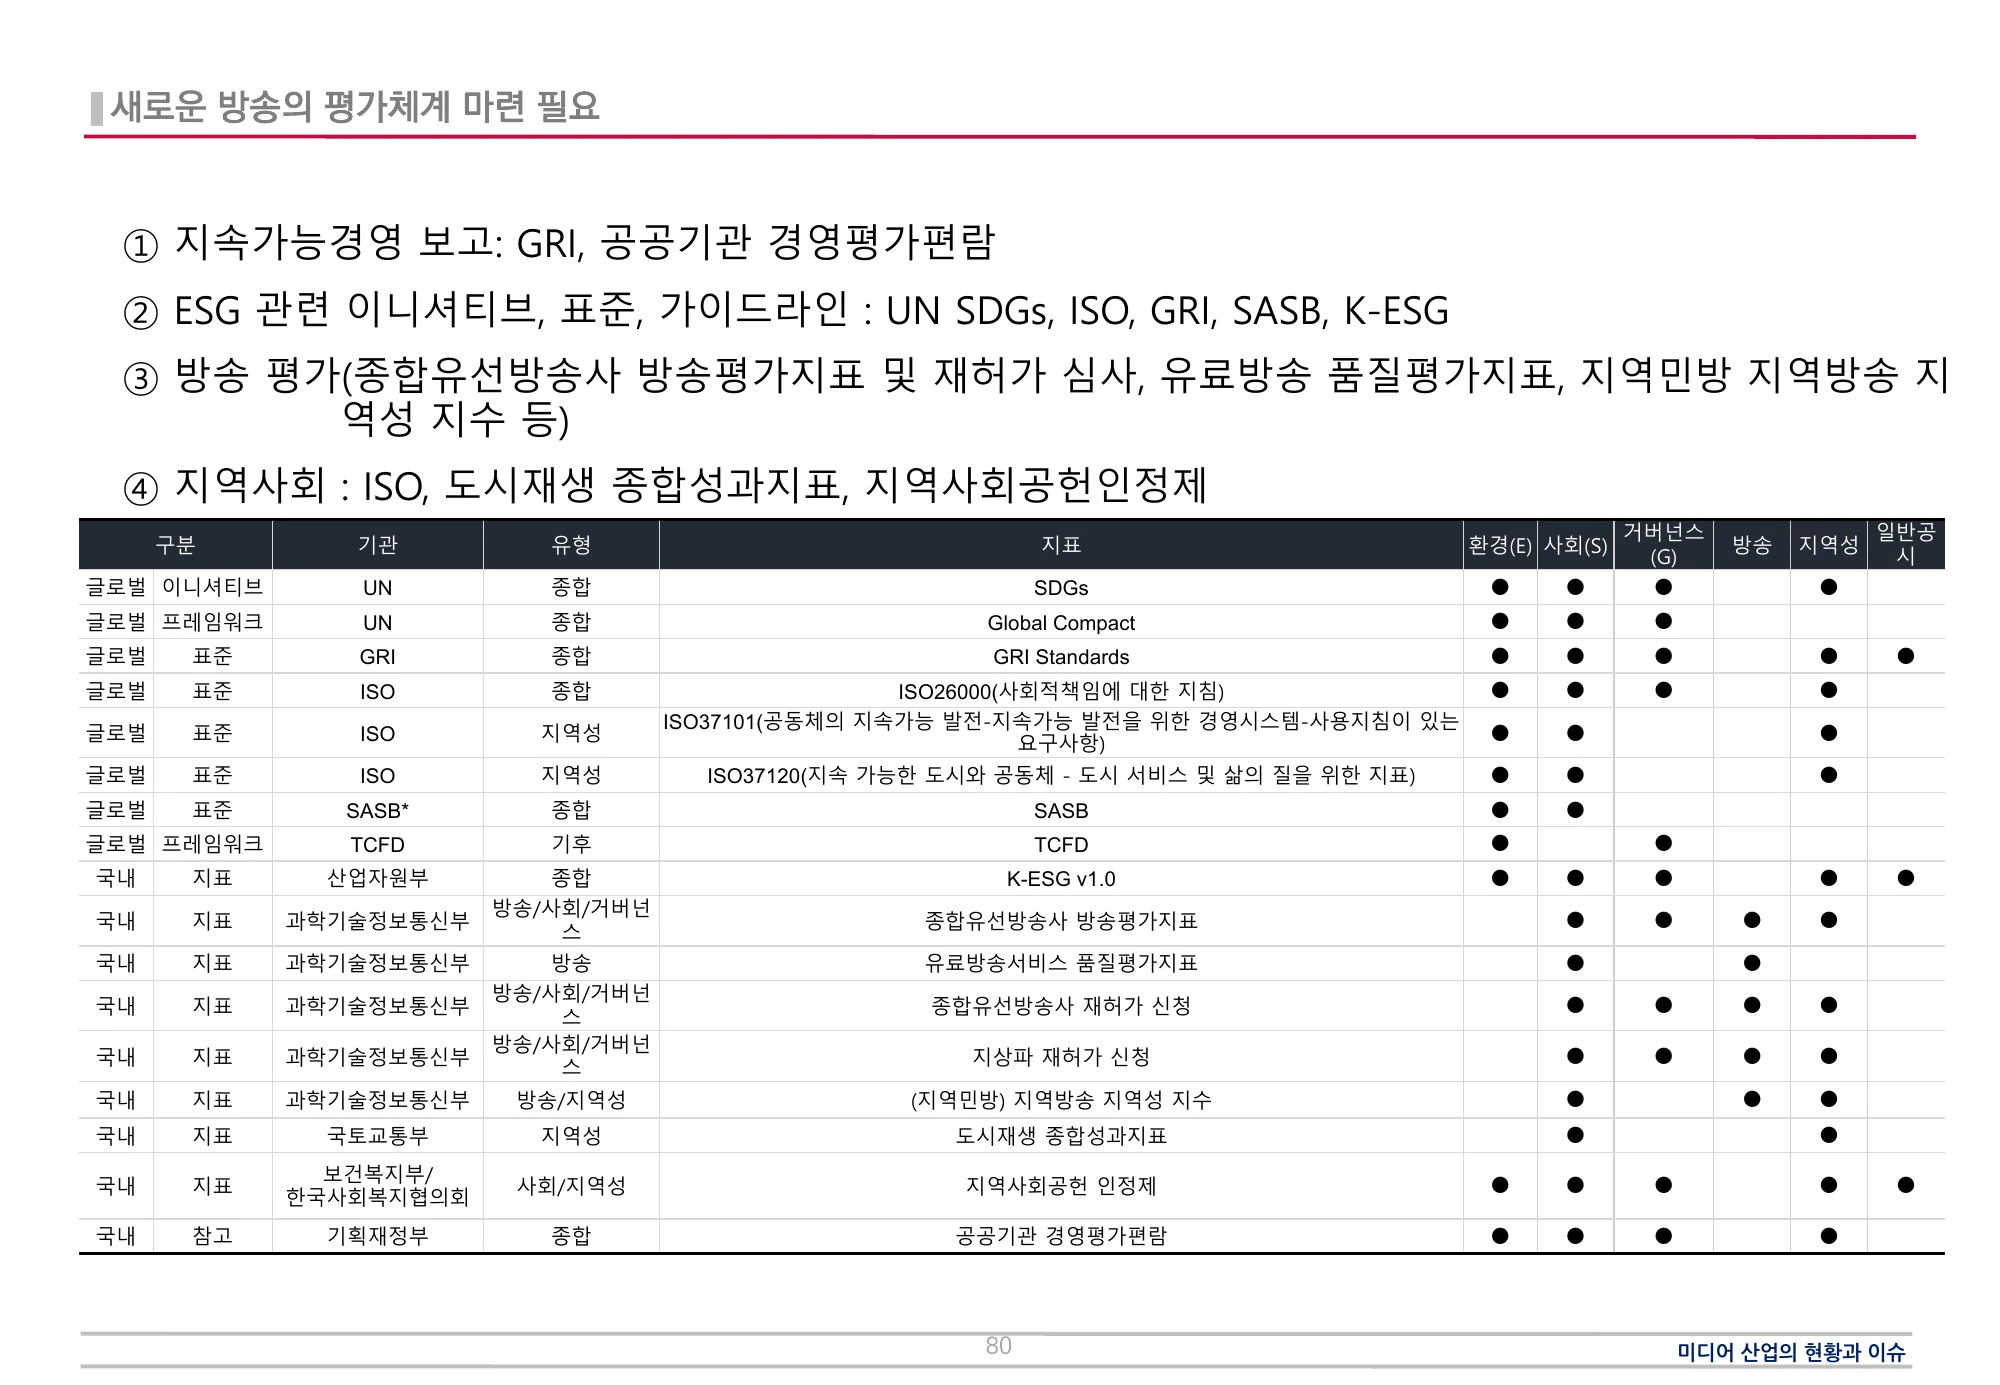
마지막 장은 방송 평가·지역성 지표와 GRI·ISO·K-ESG 등 지속가능성 기준을 연결하는 평가체계를 검토한다. ESG를 다룬 프로그램을 제작하는 활동뿐 아니라 제작 과정의 환경부담, 표준계약서, 공급망 전반의 탄소 측정과 관리까지 범위를 넓힌다. 지역성 등 공적책무에 대한 분담금 감면, 세액공제, 민관협의체와 중앙부처 후원을 제안한다. 제시된 평가체계는 설계 예시이므로 실제 인증이나 검증된 탄소 감축실적으로 해석하면 안 된다.
The final section connects broadcasting and local-service assessment with sustainability frameworks such as GRI, ISO, and K-ESG. It extends ESG beyond the themes of programs to environmental impacts during production, standard contracts, and carbon measurement across the content-network-device supply chain. Suggested mechanisms include contribution reductions for public duties, tax incentives, and sustained public-private coordination. The assessment framework is a design proposal, not evidence that an operator has obtained certification or achieved verified emissions reductions.
PDF 파일 75, 80, 81, 85, 86, 87쪽PDF pages 75, 80, 81, 85, 86, 87
홈쇼핑과 콘텐츠 대가의 서로 다른 분모Different denominators in shopping and content fees
홈쇼핑 장은 방송 취급고 감소와 온라인 채널 유도, 모바일 매출 귀속이 송출수수료 비율을 어떻게 바꾸는지 문제 삼는다. 32쪽의 약 33%는 자료가 채택한 TV 기반 매출 범위에 따른 값이다. 방송 매출만 쓰는지 TV 유입 모바일 거래를 포함하는지에 따라 비율이 달라지므로 가입자·시청률·매출 귀속을 서로 검증할 수 있게 하자는 거래 투명성 논의가 중요하다.
The shopping chapter questions how declining broadcast sales, online redirection and mobile attribution affect fee ratios. The roughly 33% on page 32 depends on its TV-attributed revenue definition. Transparent, checkable sales attribution, subscriptions and viewing information matter before comparing prices.
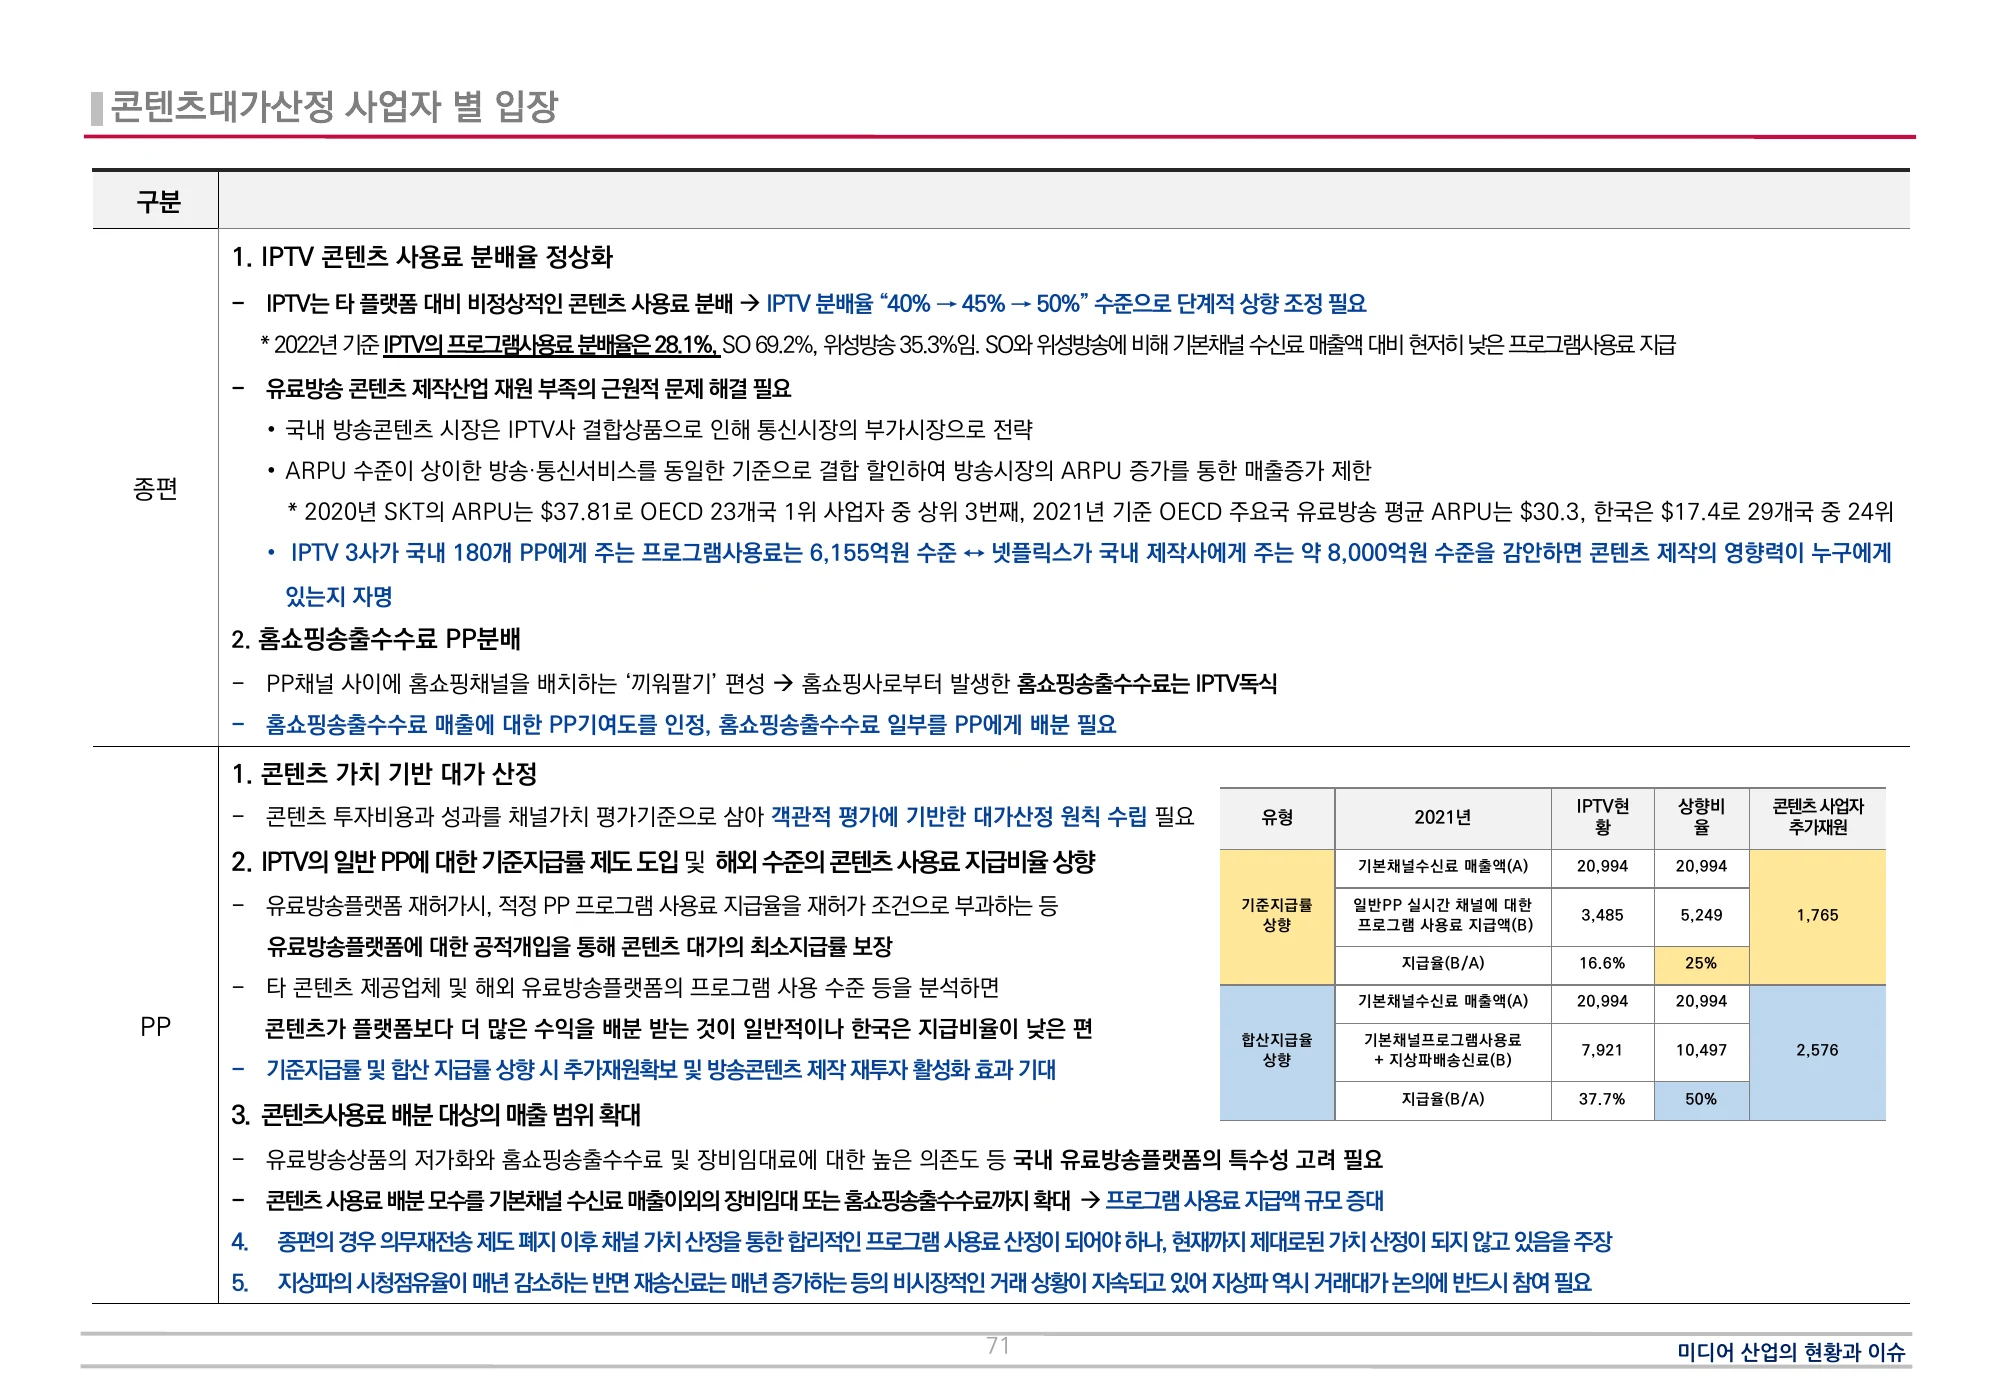
콘텐츠 장의 기준지급률 16.6→25% 안은 일반 PP 실시간 채널 사용료를 기본채널 수신료 매출로 나눈 값이다. 합산지급률 37.7→50% 안은 지상파 재송신료 등을 포함해 분자가 다르다. 둘을 같은 비용의 서로 다른 추정치로 보면 안 되며 추가재원 1,765·2,576억원도 기준을 올렸을 때의 시나리오이지 실제 지급 증가 실적이 아니다.
The 16.6→25% scenario concerns ordinary-PP linear-channel fees over basic-channel subscription revenue. The 37.7→50% scenario includes terrestrial retransmission in its numerator. They are different aggregates, and KRW176.5/257.6 billion of additional resources are scenario amounts, not realized payment increases.
PDF 파일 31, 32, 35, 71쪽PDF pages 31, 32, 35, 71
대가와 규제는 양측의 이행·설명 책임을 포함Payments and regulation involve both sides’ responsibilities
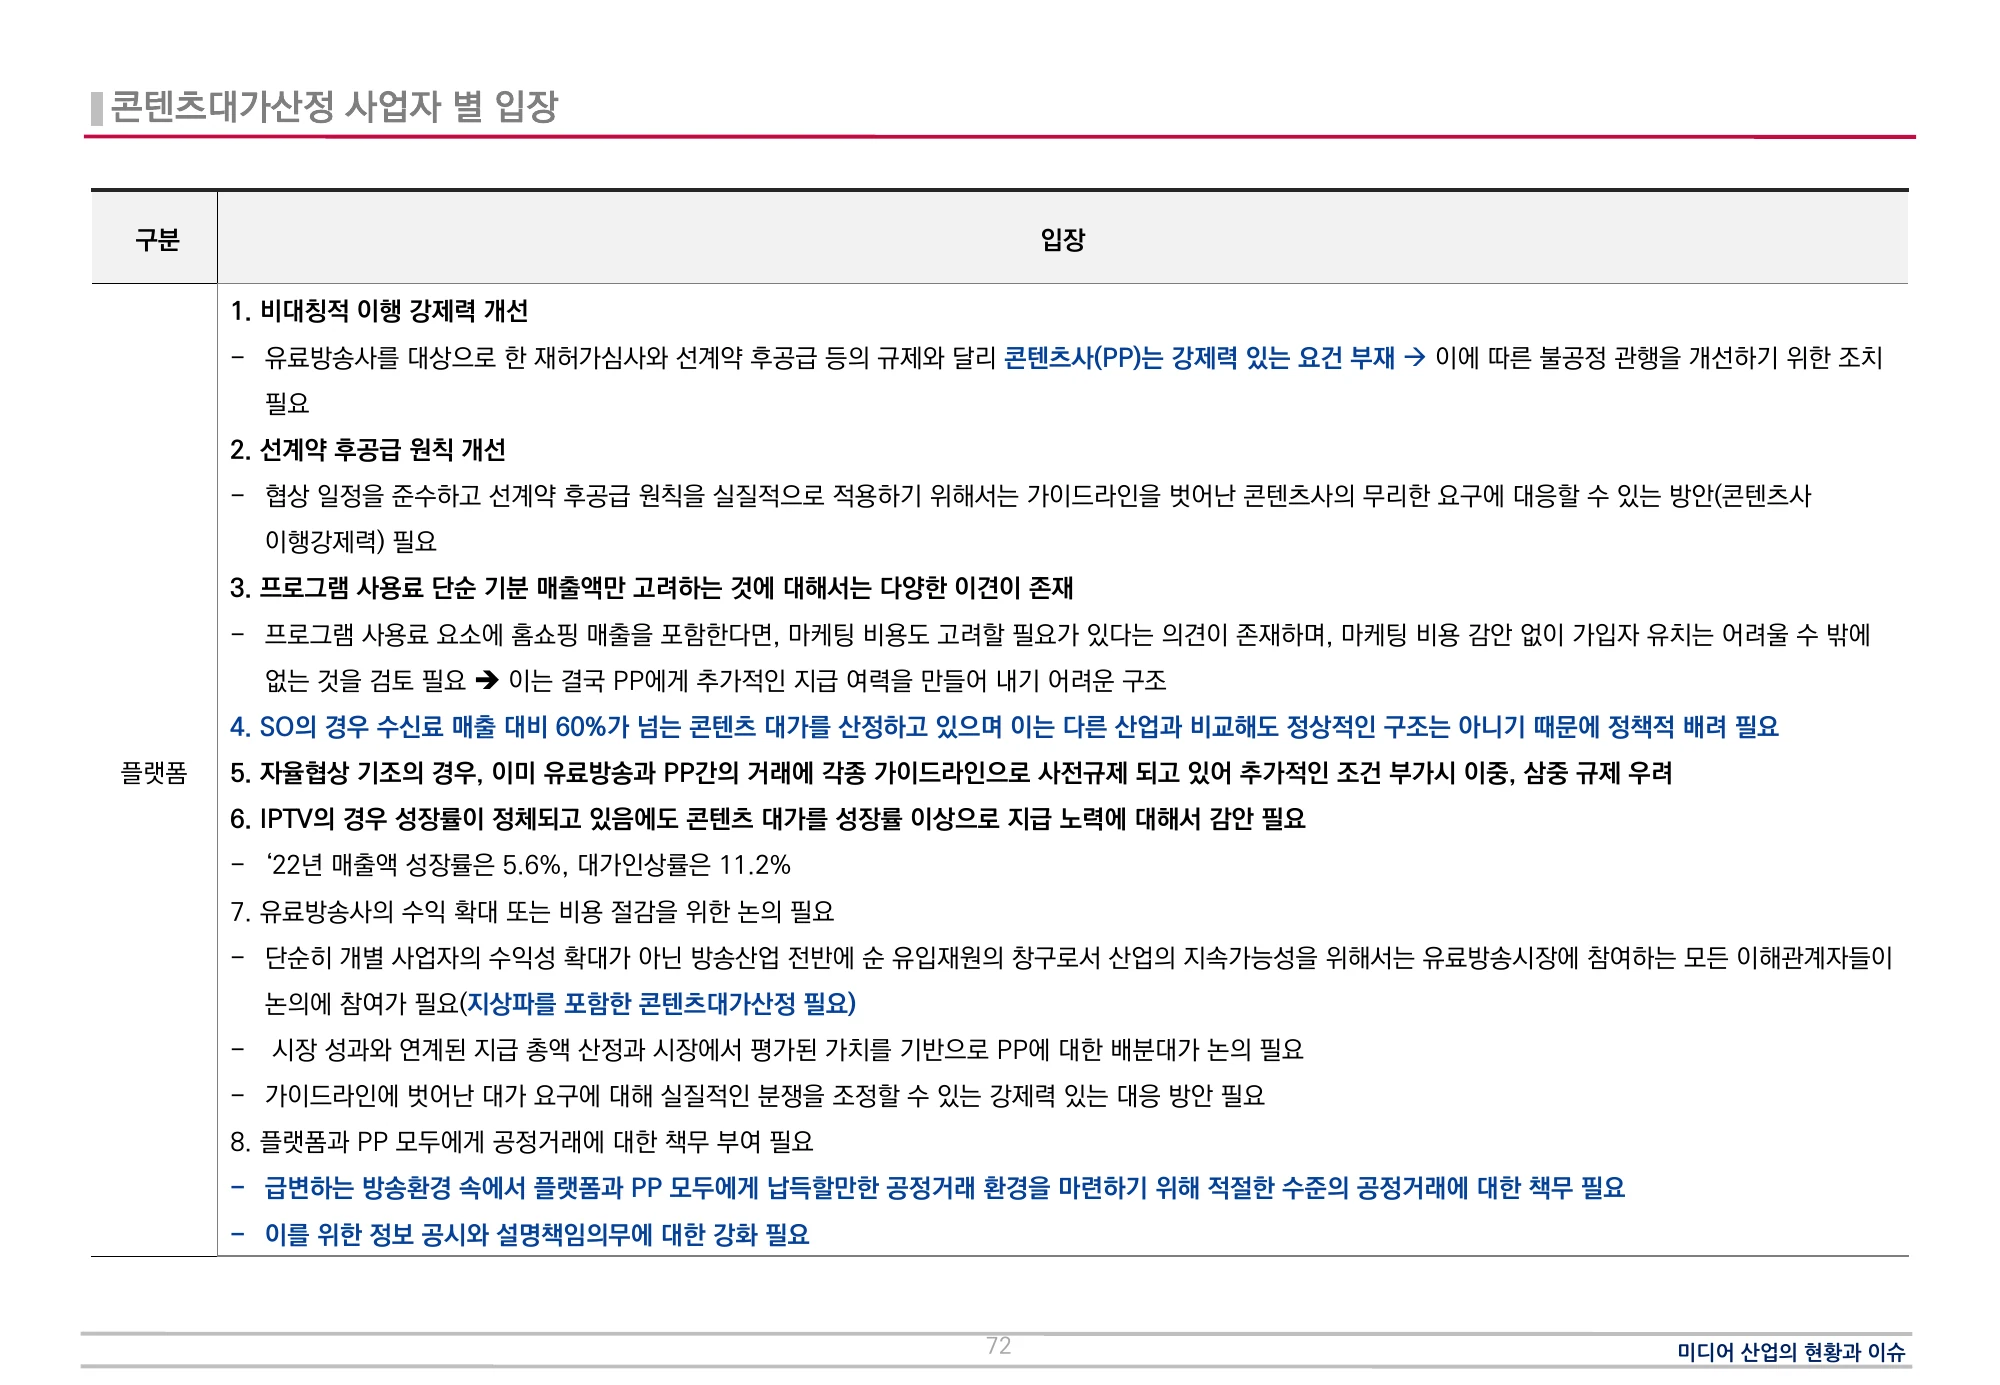
콘텐츠사업자는 투자와 기여에 맞는 배분, 홈쇼핑 수익의 일부 공유와 가치 평가를 주장하고, 플랫폼은 매출 기반·마케팅 비용·협상 일정과 이행 강제력의 비대칭을 제기한다. 발표자료는 양측의 주장과 시나리오를 나누어 싣는다. 한쪽 주장을 연구자가 독립 검증한 적정 가격으로 바꾸지 않고 비교해야 거래조건의 쟁점이 드러난다.
Content providers argue for investment-linked allocation, shopping-revenue sharing and valuation; platforms raise revenue definitions, marketing costs, deadlines and asymmetric enforceability. These remain stakeholder positions, not independently verified fair prices.
새 플랫폼 장은 메타버스 안의 영상 서비스와 QR 기반 쇼퍼블 TV처럼 기기·콘텐츠·거래가 결합하는 사례를 든다. 동일 서비스의 소비 방식에 맞춘 정의와 공정거래 책임·정보공시를 함께 검토하자는 방향이다. 모든 서비스를 곧바로 방송으로 분류하자는 현행법 결론이 아니며, 서비스의 위험·공적 책무와 규제 비용을 구분해야 하는 정책 제안이다.
Hybrid examples include video inside a metaverse and QR-based shoppable TV. The proposal calls for service-centered definitions alongside fair-trading and disclosure duties. It is not a current-law determination that every service is broadcasting; different risks, duties and compliance costs remain relevant.
PDF 파일 59, 71, 72, 85, 86쪽PDF pages 59, 71, 72, 85, 86
핵심 결과를 표로 읽기Read the key results in tables
| 주제Topic | 핵심 진단Core diagnosis | 제안·검토 방향Proposed direction |
|---|---|---|
| 방송시장Broadcasting | 포화·저가 ARPU와 플랫폼별 수익 분화Saturation, low ARPU, diverging financial trajectories | 가입자 수와 수익·거래관계를 함께 평가Assess revenue and transactions alongside subscriptions |
| 홈쇼핑Home shopping | 매출 귀속과 협상 정보의 비대칭Channel attribution and unequal bargaining information | 대가 검증·분쟁 중재·상설 협의체Price checks, mediation, standing coordination |
| OTT | 투자와 가입자당 가치의 간극Gap between investment and subscriber value | 제휴·글로벌화·전문 서비스Partnerships, international reach, specialty services |
| 새 플랫폼Emerging platforms | 기기·서비스 결합으로 법적 경계 변화Hybrid devices and services cross regulatory categories | 소비되는 서비스 중심의 정의 검토Consider service-based definitions |
| 기금Development fund | 모수·감경·용처의 정합성 문제Assessment, reductions, and spending alignment | 공적책무·시장 차이를 반영한 기준Reflect public duties and market differences |
| 콘텐츠 대가Content payments | 가치 평가와 상호 이행의 충돌Valuation disputes and reciprocal compliance | 분모를 맞춘 배분 논의·투명한 협상Comparable ratios and transparent negotiation |
| ESG | 제작·지역성·공급망 평가의 연결 필요Link production, local duties, and supply-chain assessment | 측정체계·인센티브·민관협력Measurement, incentives, public-private coordination |
각 장의 논점을 웹용으로 다시 정리한 비교표다. 확정 정책·기업 공식 입장·실현된 성과를 나열한 표가 아니다.An editorial map of the chapters, rather than a list of adopted policies, official company positions, or achieved outcomes.
이 표를 읽는 방법How to read this table
일곱 행은 같은 방법으로 수집한 통계표가 아니라 장별 쟁점을 묶은 독서 지도다. 방송시장의 관측 추이, OTT 개념도, 이해관계자의 배분 주장, ESG 제안은 증거 성격이 다르다. 같은 표에 있다는 이유로 모두 실행된 정책이나 기업 공식 입장으로 읽지 않는다.The seven rows map chapters rather than one uniformly measured dataset. Observed trends, conceptual diagrams, stakeholder claims and ESG proposals have different evidentiary status and are not all adopted policies or official company positions.
콘텐츠 대가 행의 투명한 협상은 지급률 상향만 뜻하지 않는다. 모수와 비용 범위, 지상파 포함 여부, 선계약·후공급의 양측 이행과 분쟁 절차를 함께 다룬다. ESG 행의 측정과 인센티브 역시 콘텐츠 주제와 생산 과정의 성과를 구분하는 조건부 제안이다.Transparent negotiation involves bases, costs, terrestrial inclusion, reciprocal contractual compliance and dispute procedures, not just a higher payment ratio. ESG measurement/incentives likewise distinguish themes from production-process outcomes.
PDF 파일 32, 35, 59, 65, 71, 72, 80, 85, 86, 87쪽PDF pages 32, 35, 59, 65, 71, 72, 80, 85, 86, 87
발표자료의 장별 진단과 정책 제안Chapter diagnoses and policy proposals · PDF 파일 3, 35, 49, 59, 65, 71, 80, 85, 86, 87쪽PDF pages 3, 35, 49, 59, 65, 71, 80, 85, 86, 87
| 범위Scope | 당시 지급률Historical ratio | 제안 지급률Proposed ratio | 추가재원: 억원Additional resources: KRW100m |
|---|---|---|---|
| 일반 PP 실시간 채널Ordinary-PP linear channels | 16.6% | 25% | 1,765 |
| 기본채널 사용료+지상파 재송신료Basic-channel fees + terrestrial retransmission | 37.7% | 50% | 2,576 |
원문 71쪽의 사업자 측 안이다. 두 행은 분자가 다르고 기본채널 수신료 매출 20,994억원을 공통 분모로 쓴다. 추가재원은 원문 반올림 값을 보존한 시나리오이며 실제 지급 증가가 아니다.Stakeholder scenarios from p.71. Numerators differ; both use KRW2,099.4 billion of basic-channel revenue. Additional resources retain the source’s rounded figures and are not realized increases.
원문 콘텐츠 대가산정 사업자별 입장Original stakeholder positions on content payments · PDF 파일 71쪽PDF page 71
원문의 핵심 표·그래프Key tables & figures in the source
표·그림이 수록된 원문 페이지입니다. 이미지를 누르면 확대할 수 있습니다.Original pages containing the selected tables or figures. Select an image to enlarge it.
홈쇼핑 송출수수료와 매출 귀속Shopping carriage fees and sales attribution
국내 SVOD 월간 이용자 수 합계 추이Domestic SVOD monthly-user totals
OTT 가입자당 가치와 투자 간극 개념도Conceptual OTT value–investment gap
콘텐츠사업자 측의 대가 배분 주장과 시나리오Content-provider positions and payment scenarios
콘텐츠 거래에 대한 플랫폼 측 입장Platform-side content-transaction arguments
ESG·방송·지역성 평가기준 비교ESG, broadcasting, and local-service assessment frameworks
자료의 시점·집계범위와 참여 확인의 한계Limits of dates, definitions, and attribution
이 자료의 강점은 서로 따로 논의되던 시장·대가·기금·ESG를 연결하는 데 있지만, 정책 대안의 순편익이나 인과효과를 새로 추정한 연구는 아니다. 일부 장표의 기준연도·성장률 서술과 도표 범위가 달라 현재 수치로 재사용하려면 원 통계를 다시 대조해야 한다. 해외 전망은 작성 당시 전망으로 남긴다. 인용된 김용희의 기존 발표가 있다는 사실만으로 이 자료 전체의 집필·수행 역할을 확정하지 않으며, 현재 참여 확인 대기 기록으로 유지한다.
Its contribution is to connect debates that are often separated, rather than to estimate a new causal effect or the net benefits of each reform. Some slide headings, growth-rate descriptions, and chart ranges differ, so figures require reconciliation with their underlying statistics before reuse. Forecasts remain forecasts made at the time. References to Yonghee Kim’s earlier presentations do not establish authorship of this entire document; personal participation remains unconfirmed.
PDF 파일 1, 8, 24, 42, 71, 87쪽PDF pages 1, 8, 24, 42, 71, 87
근거 쪽: Evidence pages: 1, 3, 4, 5, 8, 9, 11, 12, 13, 14, 15, 16, 17, 18, 24, 28, 30, 31, 32, 33, 34, 35, 36, 37, 38, 39, 42, 45, 49, 52, 56, 57, 58, 59, 60, 61, 64, 65, 66, 67, 68, 69, 70, 71, 72, 73, 74, 75, 80, 81, 85, 86, 87 · PDF 파일 기준, 인쇄 쪽수와 다를 수 있습니다. · PDF file pagination may differ from printed page numbers.
근거와 검토 범위Source and review scope
88쪽의 제공된 원문 자료를 기준으로 본문·표·선정 이미지를 확인했습니다. 해설은 연구 내용을 새 문장으로 정리했으며, 실제 원문 페이지를 함께 실었습니다. 분석 결과의 독립 재현이나 기관의 공식 입장 확인을 뜻하지 않습니다.
The text, tables and selected images were checked against the 88-page source document supplied for this site. This guide is an editorial summary accompanied by original source pages. This does not imply independent replication or institutional endorsement.
확인한 PDF 쪽: Source PDF pages: 1, 3, 4, 5, 8, 9, 11, 12, 13, 14, 15, 16, 17, 18, 24, 28, 30, 31, 32, 33, 34, 35, 36, 37, 38, 39, 42, 45, 49, 52, 56, 57, 58, 59, 60, 61, 64, 65, 66, 67, 68, 69, 70, 71, 72, 73, 74, 75, 80, 81, 84, 85, 86, 87