정책·산업 자료 · 원문 해설Policy & industry material · Source-based guide
합리적인 방송통신발전기금 운영 및 제도개선 방안Reforming the Operation of the Broadcasting and Telecommunications Development Fund
김용희의 원문 역할: 발표자 표기Yonghee Kim’s documented role: Named presenter
연구 내용Overview
기금 제도의 개요와 사업자 부담 구조를 설명하고 케이블 SO를 중심으로 제도개선 방향을 제시한 발표자료다. 원문 표지에 김용희가 발표자로 기재되어 있다.
A presentation describing the fund’s structure and contribution burdens and discussing reform options focused on cable operators. Its cover names Yonghee Kim.
원보고서의 문제의식·분석·제안을 정리한 해설입니다. 수치는 표시한 표와 쪽을 기준으로 읽습니다. 아래 표는 핵심 항목을 웹에서 읽도록 재구성했고, 원문 표·그림이 있는 페이지를 함께 제공합니다.This reading guide explains the report’s questions, analyses, and proposals in new wording. Tables below re-present selected source results for web reading, alongside images of the relevant original pages.
핵심부터 읽기Start with the main findings
- 발표의 핵심은 같은 매출 요율이 같은 부담을 뜻하지 않는다는 문제입니다. 이익과 현금이 줄어도 매출 기준 기금은 남을 수 있으므로, 매출 대비 명목 징수율과 영업이익 대비 실질부담률을 구분합니다. 지역채널 운영이라는 공적 비용을 감경에 반영하는 방식과 경영 여력에 상한을 두는 방식도 서로 다른 설계입니다.The presentation’s central issue is that equal revenue rates do not imply equal burdens. A revenue-based contribution can remain high when earnings and cash decline. It distinguishes nominal collection rates from contributions relative to operating profit, and separates recognition of local-channel public-service costs from profit-based caps.PDF 파일 28, 35, 39, 48, 50쪽PDF pages 28, 35, 39, 48, 50
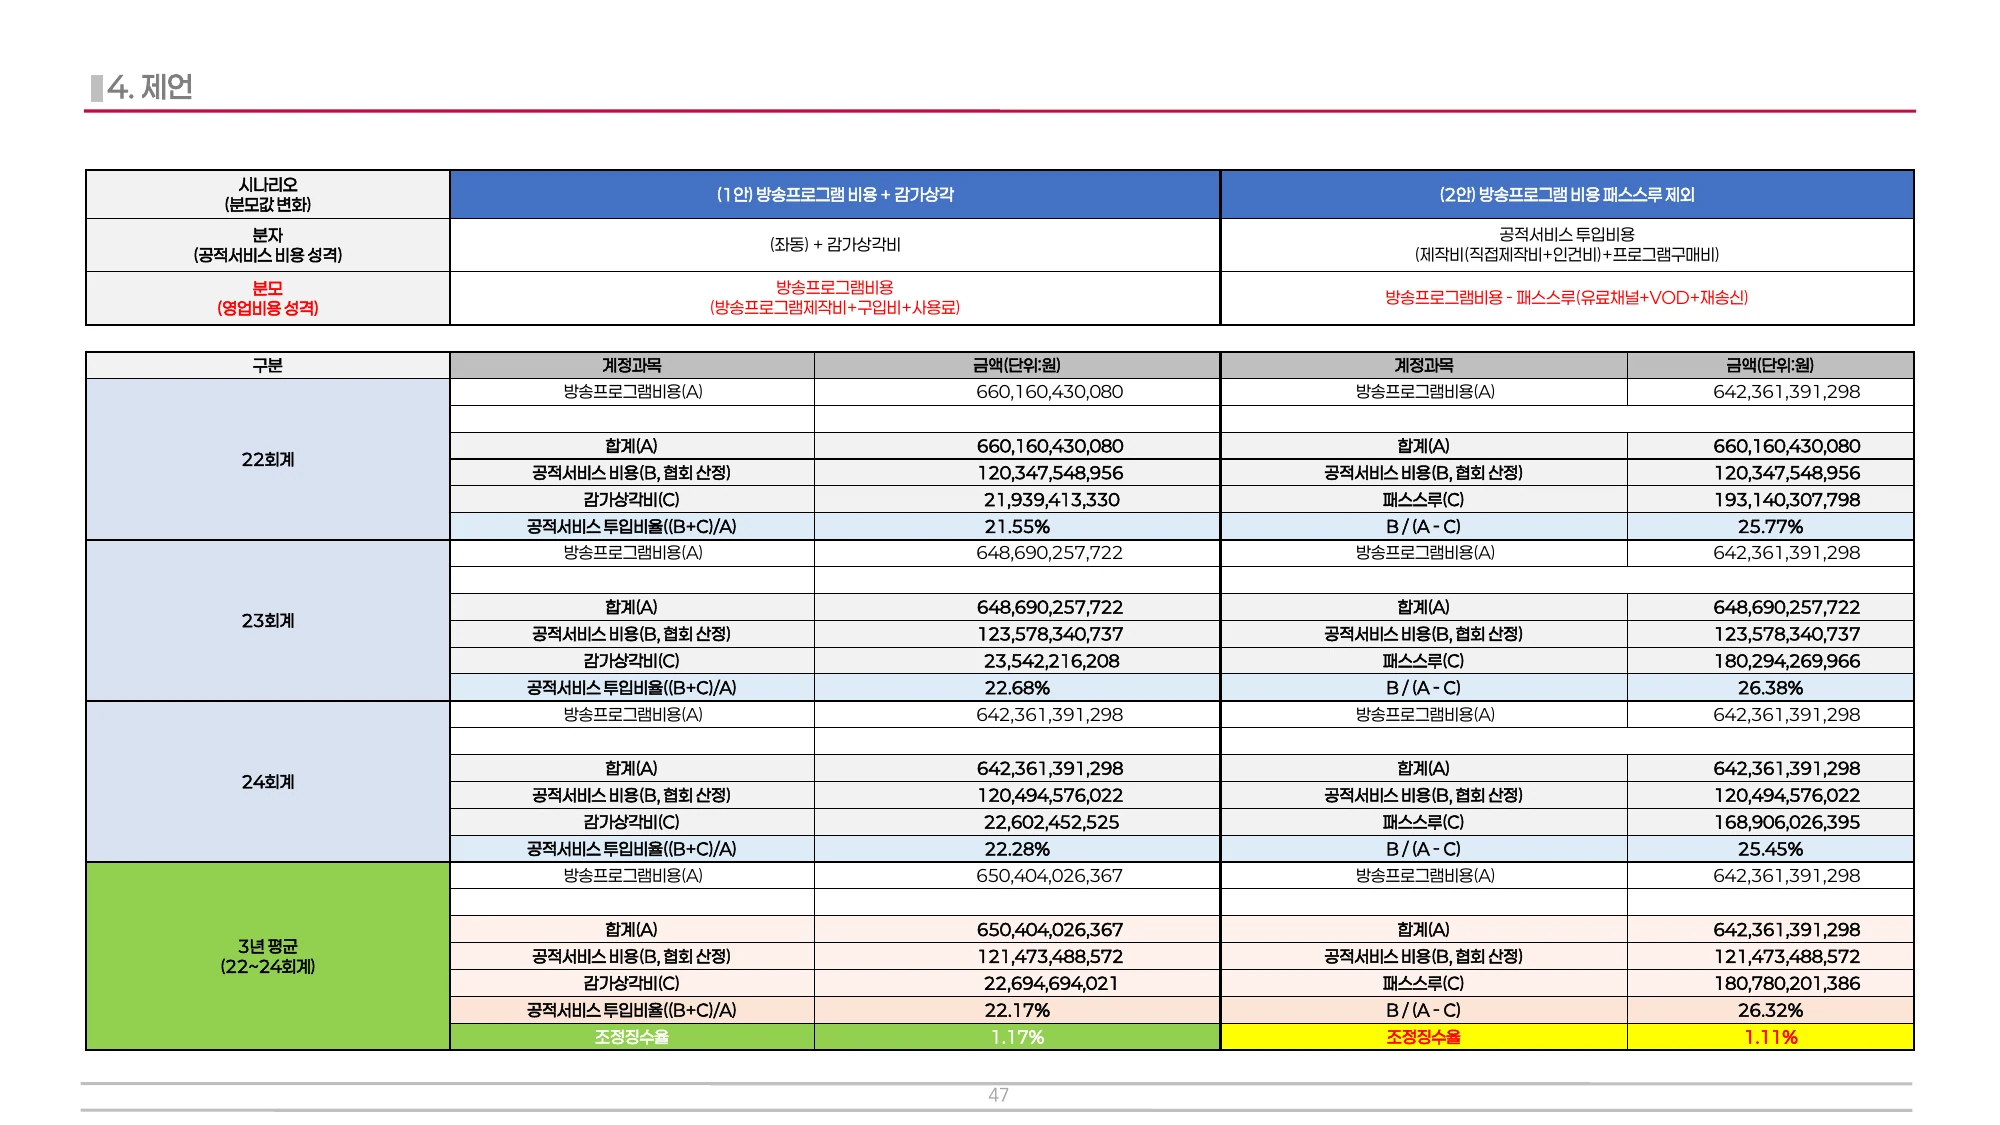
- 제3안의 구체 문안은 흑자·손익분기 SO에 매출 0.8%와 영업이익 50% 중 작은 금액, 적자 SO에는 매출 0.3%를 적용하는 구상입니다. 따라서 ‘50% 상한’이라는 제목만으로 적자 사업자의 기금이 0원이 된다고 해석하면 안 됩니다. 이는 당시 발표의 개정 제안이며 시행된 고시를 설명하는 것이 아닙니다.Option 3’s draft wording applies the smaller of 0.8% of revenue or 50% of operating profit to non-loss-making SOs, and 0.3% of revenue to loss-making SOs. The “50% cap” heading therefore does not imply zero contributions for loss-making firms. This is proposed wording, not an enacted collection notice.PDF 파일 54쪽PDF page 54
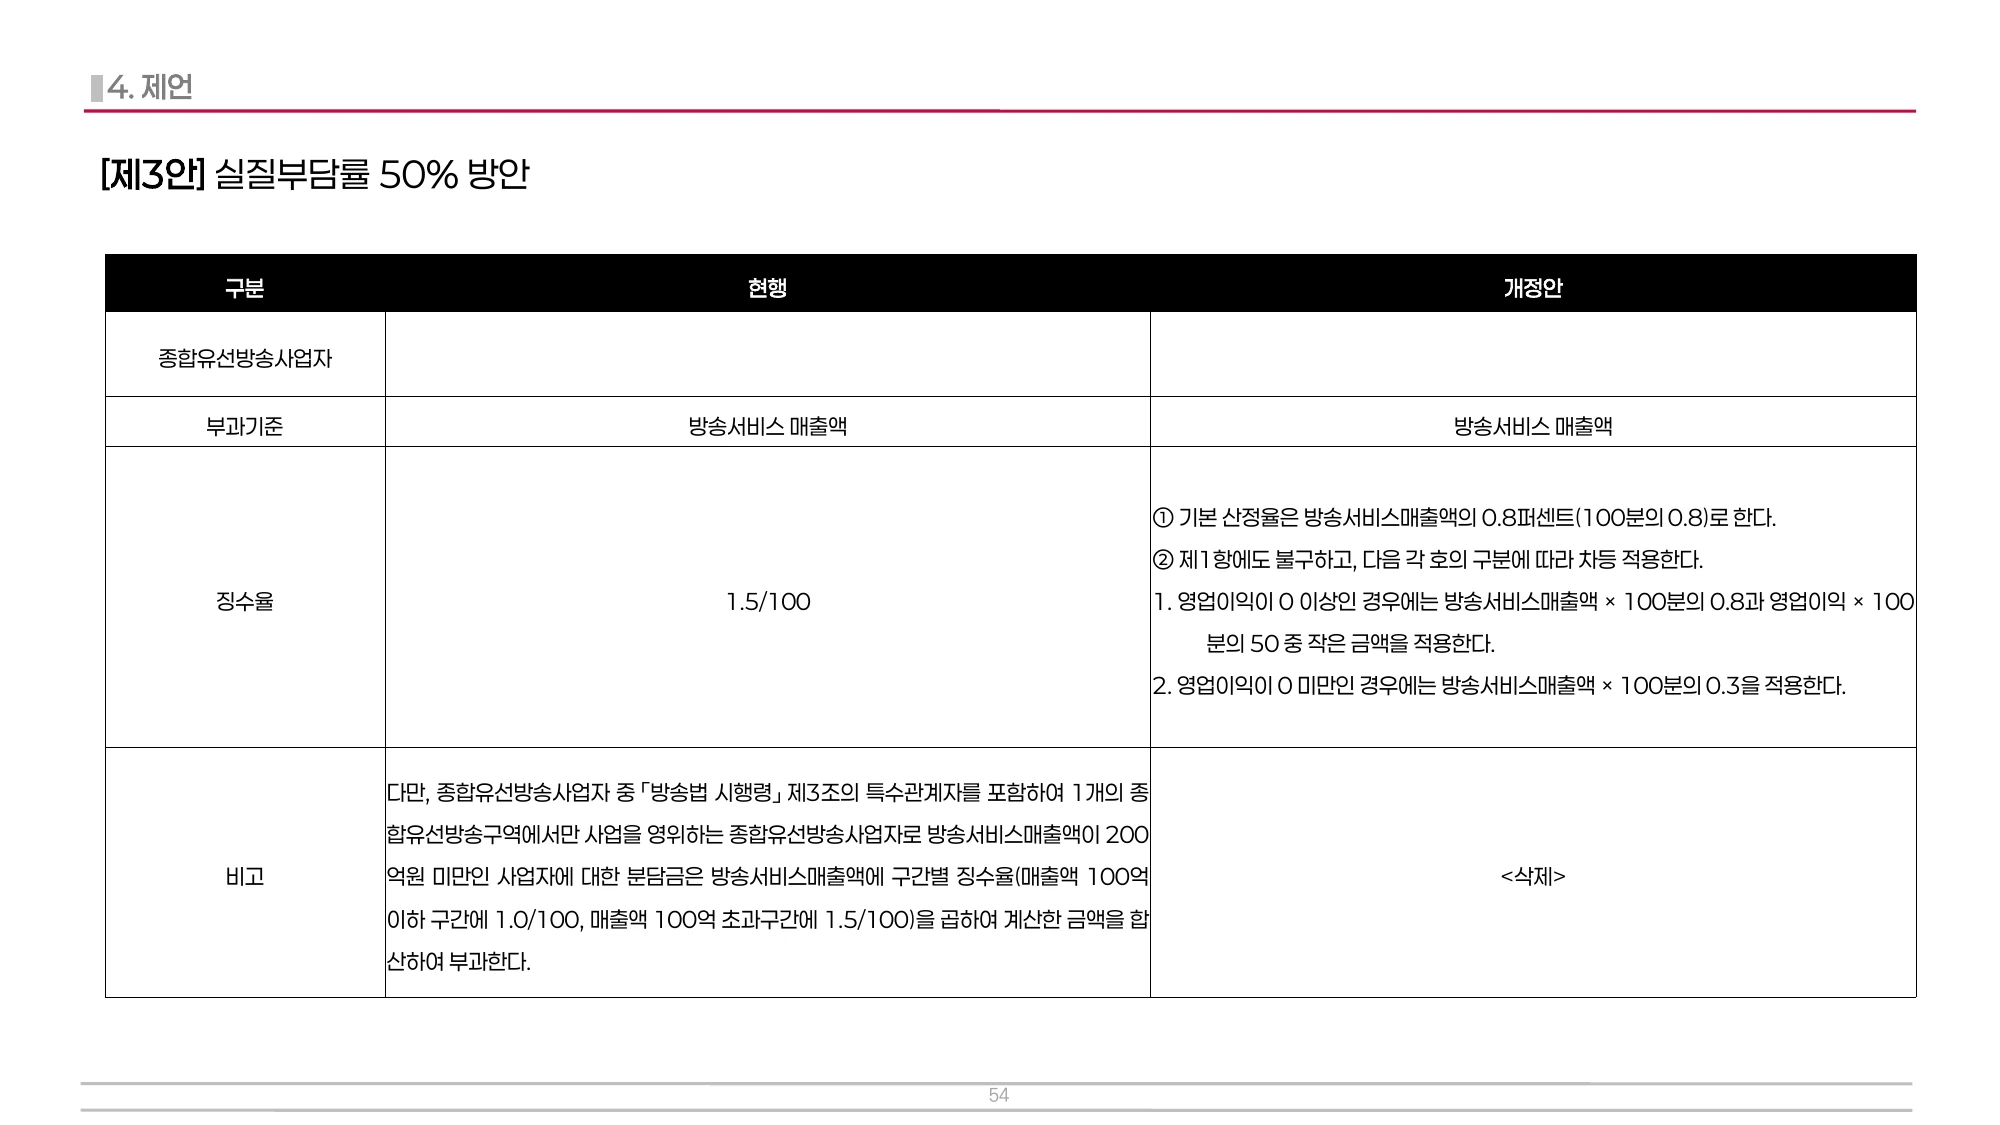
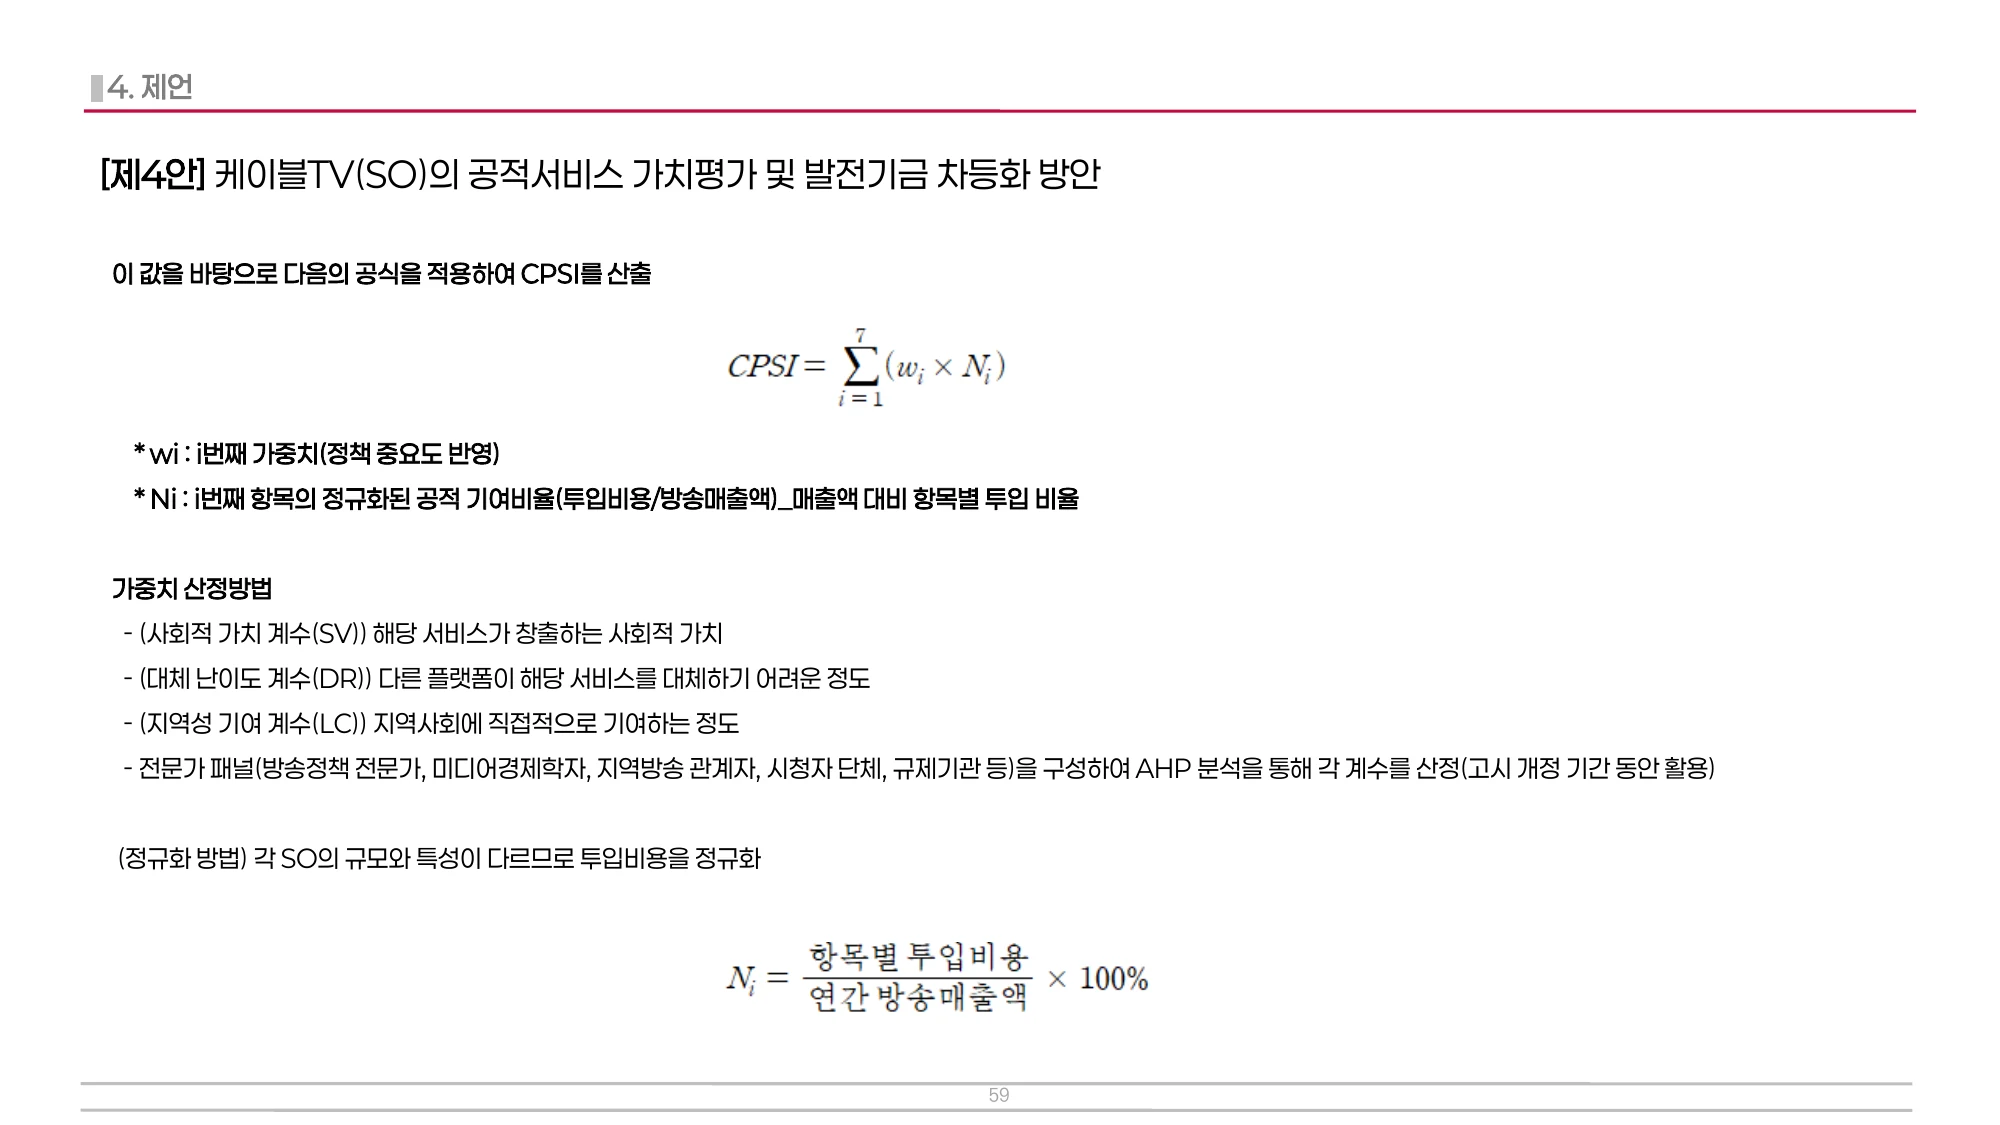
- 공적서비스 지수 CPSI는 비용을 투입했다는 사실과 사회적 성과를 구분할 필요가 있습니다. 원문은 사회적 가치·대체 난이도·지역성에 대한 전문가 AHP 가중치를 제안하지만 제시한 계산 가중치는 가정입니다. 비용이 높을수록 자동으로 우수한 공적 성과라고 판정하는 평가 체계가 확정된 것은 아닙니다.The proposed CPSI needs to distinguish expenditure from public outcomes. The source proposes expert AHP weights for social value, substitutability and local contribution, but its illustrative calculation uses assumed weights. It does not establish a validated system in which higher expenditure automatically means better public performance.PDF 파일 58, 59, 60, 61쪽PDF pages 58, 59, 60, 61
기금 운영을 산업 상황과 공적 역할에 맞추기Align fund design with industry conditions and public roles
이 발표자료는 방송통신발전기금의 개요·현황·쟁점·제언을 네 부분으로 정리하고 특히 케이블 SO의 경영상태와 지역 공적 역할을 함께 보자고 제안합니다. 같은 매출 기준 징수율이 적용되어도 이익과 지역채널 투자가 다른 사업자의 실질 부담은 다를 수 있다는 문제의식입니다. 표지에는 선문대학교 김용희가 명시되어 발표 기명은 확인되지만 표지 자체에 연도는 없어 2025년 분류는 파일·보관 맥락에 근거합니다.
The presentation reviews the fund’s principles, finances, issues and reforms, focusing on cable operators’ financial conditions and local public-service roles. Identical revenue-based rates can imply different burdens relative to profit. The cover names Yonghee Kim, but does not print a year; its 2025 dating comes from the file context.
PDF 파일 1, 2, 24, 45, 46쪽PDF pages 1, 2, 24, 45, 46
기금·부담금과 징수의 원칙Fund and contribution principles
첫 부분은 기금과 부담금의 구분, 기금의 조성과 용도, 사업자별 징수기준의 변화를 설명합니다. 공정성·투명성·목적에 필요한 범위라는 원칙과 방송·정보통신·문화 분야 여러 기금을 나란히 살펴봅니다. 기금 수입 전체와 방송사업자 분담금은 같은 분모가 아니며, 주파수 관련 수입·정부 출연·운용수익을 분리해야 합니다. 여기의 법령 설명은 발표 당시 자료의 논리이며 현재 납부 의무나 요율을 안내하는 법률 검토로 사용하지 않습니다.
The first part distinguishes funds and contributions, their sources and uses, and historical rate changes. Fairness, transparency and purpose limitation are central. Total fund income is not the same denominator as broadcaster contributions; spectrum-related receipts, transfers and investment income must be separated. The legal descriptions are historical context rather than current compliance advice.
PDF 파일 3, 4, 5, 6, 7, 10쪽PDF pages 3, 4, 5, 6, 7, 10
계획 수입과 실제 지출을 구분Distinguish planned receipts and expenditure
현황 부분은 연도별 법정부담금 수입과 분야별 지출을 비교합니다. 2025년 수입 그래프는 '계획'으로 표시되어 이전 연도의 실제값과 같은 성격으로 읽을 수 없습니다. 지출 표는 세부 사업과 소관의 구성을 보여주지만 서로 다른 표의 합계·평균·단위가 일치하는지 원자료로 재확인할 필요가 있습니다. 지원사업의 수혜가 부담을 내는 사업자에게 얼마나 돌아가는지는 단순 예산 항목의 존재만으로 판단할 수 없다는 점도 유지합니다.
The finance section compares annual receipts and spending. The 2025 receipt figure is explicitly a plan, unlike historical actual values. Expenditure tables describe programs, but totals, averages and units require source reconciliation. A program’s appearance in the budget alone does not establish how much benefit returns to the firms paying contributions.
PDF 파일 16, 20쪽PDF pages 16, 20
매출 기반 부담과 수익성 악화의 문제Revenue-based burdens under declining profitability
쟁점 부분은 SO와 IPTV의 시장 변화, 광고·수신료·콘텐츠 비용·투자여력의 관계를 논의합니다. 자료에 제시된 산업 위기 도식은 여러 외부 수치와 해석을 묶은 것이므로 모든 화살표를 검증된 인과관계로 읽지 않습니다. SO가 지역채널과 재난·공익 콘텐츠에 비용을 투입한다는 점을 감경 설계의 근거로 검토하지만, 지출액과 실제 공익 성과가 일대일로 같다는 주장은 아닙니다. 비용을 인정하려면 정의와 중복계상·성과 확인이 필요합니다.
The diagnosis connects market shifts, revenue pressure, costs and investment capacity. The crisis diagram combines data and interpretation; its arrows are not all identified causal relationships. Public-service spending can inform relief design, but spending is not identical to achieved public value. Definitions, additionality, duplication and outcomes need verification.
PDF 파일 24, 30, 31, 46쪽PDF pages 24, 30, 31, 46
제1·2안: 공적 서비스 비용의 인정 범위Options 1–2: define eligible public-service costs
첫째 안은 공적서비스 비용과 감가상각을 방송프로그램비용으로 나눈 비율을 기본 징수율에서 감경하는 방식입니다. 둘째는 패스스루 비용을 제외한 분모를 사용하려는 대안입니다. 어떤 비용을 분자와 분모에 포함하느냐에 따라 감경률이 달라집니다. 원문 p47은 연도별·합계 항목 일부에서 같은 금액을 반복해 표기하므로 이 해설은 모든 계산값의 정합성을 확정하지 않고 산식 차이를 중심으로 비교합니다. 제안 요율은 시행된 요율이 아닙니다.
Option 1 offsets the basic rate by the share of public-service spending and depreciation in program costs. Option 2 changes the denominator to exclude pass-through costs. Eligibility and denominators materially affect relief. Some p47 entries appear repeated or inconsistent, so this explanation compares formulas rather than certifying every calculation or presenting proposals as enacted rates.
PDF 파일 47, 48, 49쪽PDF pages 47, 48, 49
제3안: 이익 대비 부담을 고려하는 상한Option 3: consider burdens relative to profit
세 번째 안은 매출 기준 요율과 영업이익 대비 상한을 결합하고 적자 사업자의 부담을 달리 설계합니다. p51은 이론적 탐색값 0.55%와 실무 제안 0.80%를 구분하며, 산업 부담과 재원 유지 사이의 가중 평가를 설명합니다. 0.80%를 통계적으로 유일한 최적값이나 실제 확정된 징수율로 말하지 않습니다. 영업이익의 변동성과 적자 기업 처리, 기업별 상한과 산업 전체의 비율이 다른 점을 분리해야 제안을 이해할 수 있습니다.
Option 3 combines a revenue rate with a profit-related cap and different treatment of loss-making operators. The slides distinguish a theoretical search result of 0.55% from a practical proposal of 0.80%. This is a weighted design trade-off, not a uniquely proven optimum or enacted rate. Firm caps and aggregate industry ratios differ.
PDF 파일 50, 51, 52쪽PDF pages 50, 51, 52
제4안: 공적서비스 지수와 가중치Option 4: a public-service index and its weights
네 번째 안은 보편적 서비스·공익 콘텐츠·지역 공동체·글로벌 협력·기업 상생 등 일곱 비용 영역을 매출 대비 비율로 정규화한 CPSI를 제안합니다. 중요한 점은 p60의 가중치가 실제 전문가 합의 검증값이 아니라 '전문가 합의 결과로 가정'한 예시라는 것입니다. 2.59라는 산출 예시도 특정 투입값과 가정에 따른 지수이지 공익 성과가 검증됐다는 점수가 아닙니다. 가치평가에 비용·성과·검증을 어떻게 결합할지는 후속 설계 과제입니다.
Option 4 proposes a CPSI using seven spending categories normalized by revenue. On p60, weights are explicitly assumed as if expert-agreed, not validated consensus estimates. The example score of 2.59 is conditional on those inputs and weights. A genuine public-value evaluation still needs to connect spending, outcomes and verification.
PDF 파일 58, 60쪽PDF pages 58, 60
비용 감사와 감경의 실행 체계Audit and implementation arrangements
실행하려면 공적서비스 비용의 회계 범위, 적격 사업, 감가상각 기간과 제3자 검증 기준을 먼저 정해야 합니다. 기업의 개별 실적과 산업 평균을 나누고 이의제기와 자료 공개의 절차도 마련할 수 있습니다. 발표는 유예·감경과 중장기 개편을 구분하지만 특정 시점의 납부 유예가 승인되었다고 확인한 문서는 아닙니다. 실제 제도를 적용하기 전에는 징수기관·사업자·시민 관점에서 재원과 공익 성과의 균형을 별도로 평가해야 합니다.
Implementation would require accounting definitions, eligible activities, depreciation treatment and independent verification, plus appeals and disclosure procedures. Individual firms and industry averages should remain distinct. The presentation separates temporary relief from longer-term redesign, but does not certify an approved suspension. Fiscal and public-interest trade-offs require further assessment before implementation.
PDF 파일 46, 48, 51, 58, 60쪽PDF pages 46, 48, 51, 58, 60
50% 상한은 사업자별 산식과 산업 총계를 구분Distinguish firm-level caps from industry aggregates
51쪽은 2024년 90개 SO 자료에서 0.5~1.5%의 요율을 탐색한 뒤 실용적 절충안으로 0.8%를 제시합니다. 이론적 최적 0.55%와 정책 제안 0.8%가 다르며, 목적함수도 산업 정상화와 과부담 최소화에 7:3 가중치를 둡니다. 그러므로 0.8%는 가치 판단과 재정 보전을 포함한 선택이지 데이터가 유일하게 결정한 자연적 정답은 아닙니다.
Page 51 searches rates from 0.5% to 1.5% using data for 90 SOs, then selects 0.8% as a practical compromise rather than the reported theoretical optimum of 0.55%. Its objective weights normalisation and limiting overburden 7:3. The selected rate incorporates policy preferences and revenue considerations, rather than being uniquely dictated by the data.
발표의 산업 총계 실질부담률 68.4%는 개별 흑자 기업에 적용할 50% 상한과 다른 수준의 지표입니다. 적자·흑자 사업자의 합계 이익, 적자 사업자 별도 요율, 적용 시점과 재무자료 범위를 함께 확인해야 합니다. 55쪽 즉시 경감 계산의 101.8억원과 56쪽 회복 경로 첫해 131.8억원도 서로 다른 시나리오 값이므로 같은 결과로 교체해 쓰지 않습니다.
The reported aggregate burden of 68.4% is not the same measure as a 50% cap applied to individual profitable firms. Netting profits and losses, the separate loss-making-firm rate and scenario timing all matter. The immediate calculation of KRW 10.18 billion and first-year recovery scenario of 13.18 billion also should not be substituted for one another.
PDF 파일 51, 52, 54, 55, 56쪽PDF pages 51, 52, 54, 55, 56
재정 보전과 공적 비용 인정의 조건Conditions for fiscal offsets and public-cost recognition
57쪽은 IPTV 3% 성장, 홈쇼핑 3.5% 성장, 위성 2.5% 감소 등의 가정으로 3년 타부문 자연증가 248.5억원을 산출합니다. 세수 증가 74.8억원을 더한 보전율을 제시하지만 일반 세입이 방송통신발전기금으로 자동 귀속되는 것은 아닙니다. 자연 성장 전망과 실제 기금 회계의 재원 보전은 구분해야 하며, 기금 총규모를 어떤 연도로 잡는지도 확인 대상입니다.
Page 57 assumes 3% IPTV growth, 3.5% home-shopping growth and a 2.5% satellite decline to calculate KRW 24.85 billion in three-year offsets. It adds KRW 7.48 billion in tax revenue, but general tax receipts do not automatically accrue to the fund. Forecast growth and actual fund-account offsets are distinct; the chosen fund-total year also matters.
비용 인정안은 공적서비스비와 감가상각을 분자에 두고 전체 프로그램 비용 또는 패스스루 제외 비용을 분모에 둡니다. 분모가 달라지면 같은 비용의 비율도 커집니다. 48쪽의 1,442억/6,504억과 49쪽의 169억/449억은 규모가 다른 예시이므로 개선 효과 차이를 분모 변경만의 결과로 설명하지 않습니다. 회계 범위·중복 계산·외부 구매비를 먼저 일치시켜야 합니다.
Cost-recognition options divide public-service expenditure plus depreciation by all programme costs or costs excluding pass-through purchases. A smaller denominator raises the share, but pages 48 and 49 also use different-sized examples: 1,442/6,504 versus 169/449 in KRW 100 million. Differences cannot be attributed solely to denominator design without consistent accounting boundaries.
PDF 파일 48, 49, 57, 59쪽PDF pages 48, 49, 57, 59
핵심 결과를 표로 읽기Read the key results in tables
| 안Option | 핵심 기준Core criterion | 확인 과제Verification task |
|---|---|---|
| 1안1 | 프로그램비용 대비 공적서비스+감가상각Public-service plus depreciation share | 회계 범위·중복비용Accounting boundaries and duplication |
| 2안2 | 패스스루 비용을 뺀 분모Denominator excluding pass-through | 분모 정의·수치 정합성Denominator definition and consistency |
| 3안3 | 매출 요율+이익 상한Revenue rate plus profit cap | 적자 처리·변동성Loss-making firms and volatility |
| 4안4 | CPSI 비용지수CPSI spending index | 가정 가중치·성과 검증Assumed weights and outcome validation |
원문 p47~60의 대안 비교를 재구성했습니다. p47 수치 정합성 미확정, p60 가중치는 가정입니다. 어떤 안도 시행 확정으로 표시하지 않습니다.Adapted from pp47–60. Numerical consistency on p47 remains unresolved; p60 weights are assumed. No option is presented as enacted.
이 표를 읽는 방법How to read this table
1·2안은 ‘무엇을 공적 투입으로 인정하는가’, 3안은 ‘감당할 이익이 있는가’, 4안은 ‘공적 기여에 어떤 가중치를 줄 것인가’를 묻습니다. 서로 다른 기준이므로 네 안의 감면액을 단순히 더하거나 모든 사업자에게 중복 적용하는 완성안으로 볼 수 없습니다.Options 1–2 ask which costs qualify, option 3 asks what earnings can sustain, and option 4 asks how to weight public contributions. The alternatives are not an additive package of relief amounts or a final rule applying all reductions simultaneously.
지수안의 S등급 1.0%, A등급 1.2% 같은 수치는 예시 등급표입니다. 실제 전문가 조사·감사·지표 검증으로 확정한 요율은 아닙니다. 비용자료로 계산한 지수와 주민에게 제공한 서비스의 질·접근성·재난 정보 성과를 함께 확인해야 비용 증가 자체에 보상하는 부작용을 줄일 수 있습니다.Rates such as 1.0% for S and 1.2% for A are illustrative index bands, not rates established through completed expert research, audit and validation. Cost-derived scores need service-quality, access and emergency-information evidence to avoid rewarding expenditure alone.
PDF 파일 47, 48, 49, 54, 59, 60, 61쪽PDF pages 47, 48, 49, 54, 59, 60, 61
원문 제언 비교 재구성Editorial comparison of original reform proposals · PDF 파일 47, 48, 49, 51, 58, 60쪽PDF pages 47, 48, 49, 51, 58, 60
원문의 핵심 표·그래프Key tables & figures in the source
표·그림이 수록된 원문 페이지입니다. 이미지를 누르면 확대할 수 있습니다.Original pages containing the selected tables or figures. Select an image to enlarge it.
기금 개편의 입력값과 산정 예시Inputs and calculation examples for fund reform
흑자·적자 사업자를 구분한 개정 문안Proposed wording for profitable and loss-making firms
CPSI 비용 항목과 구성 예CPSI cost items and illustrative composition
CPSI 지수의 산식과 가중치 설계CPSI formula and weighting design
가정 가중치를 적용한 CPSI 예CPSI example with assumed weights
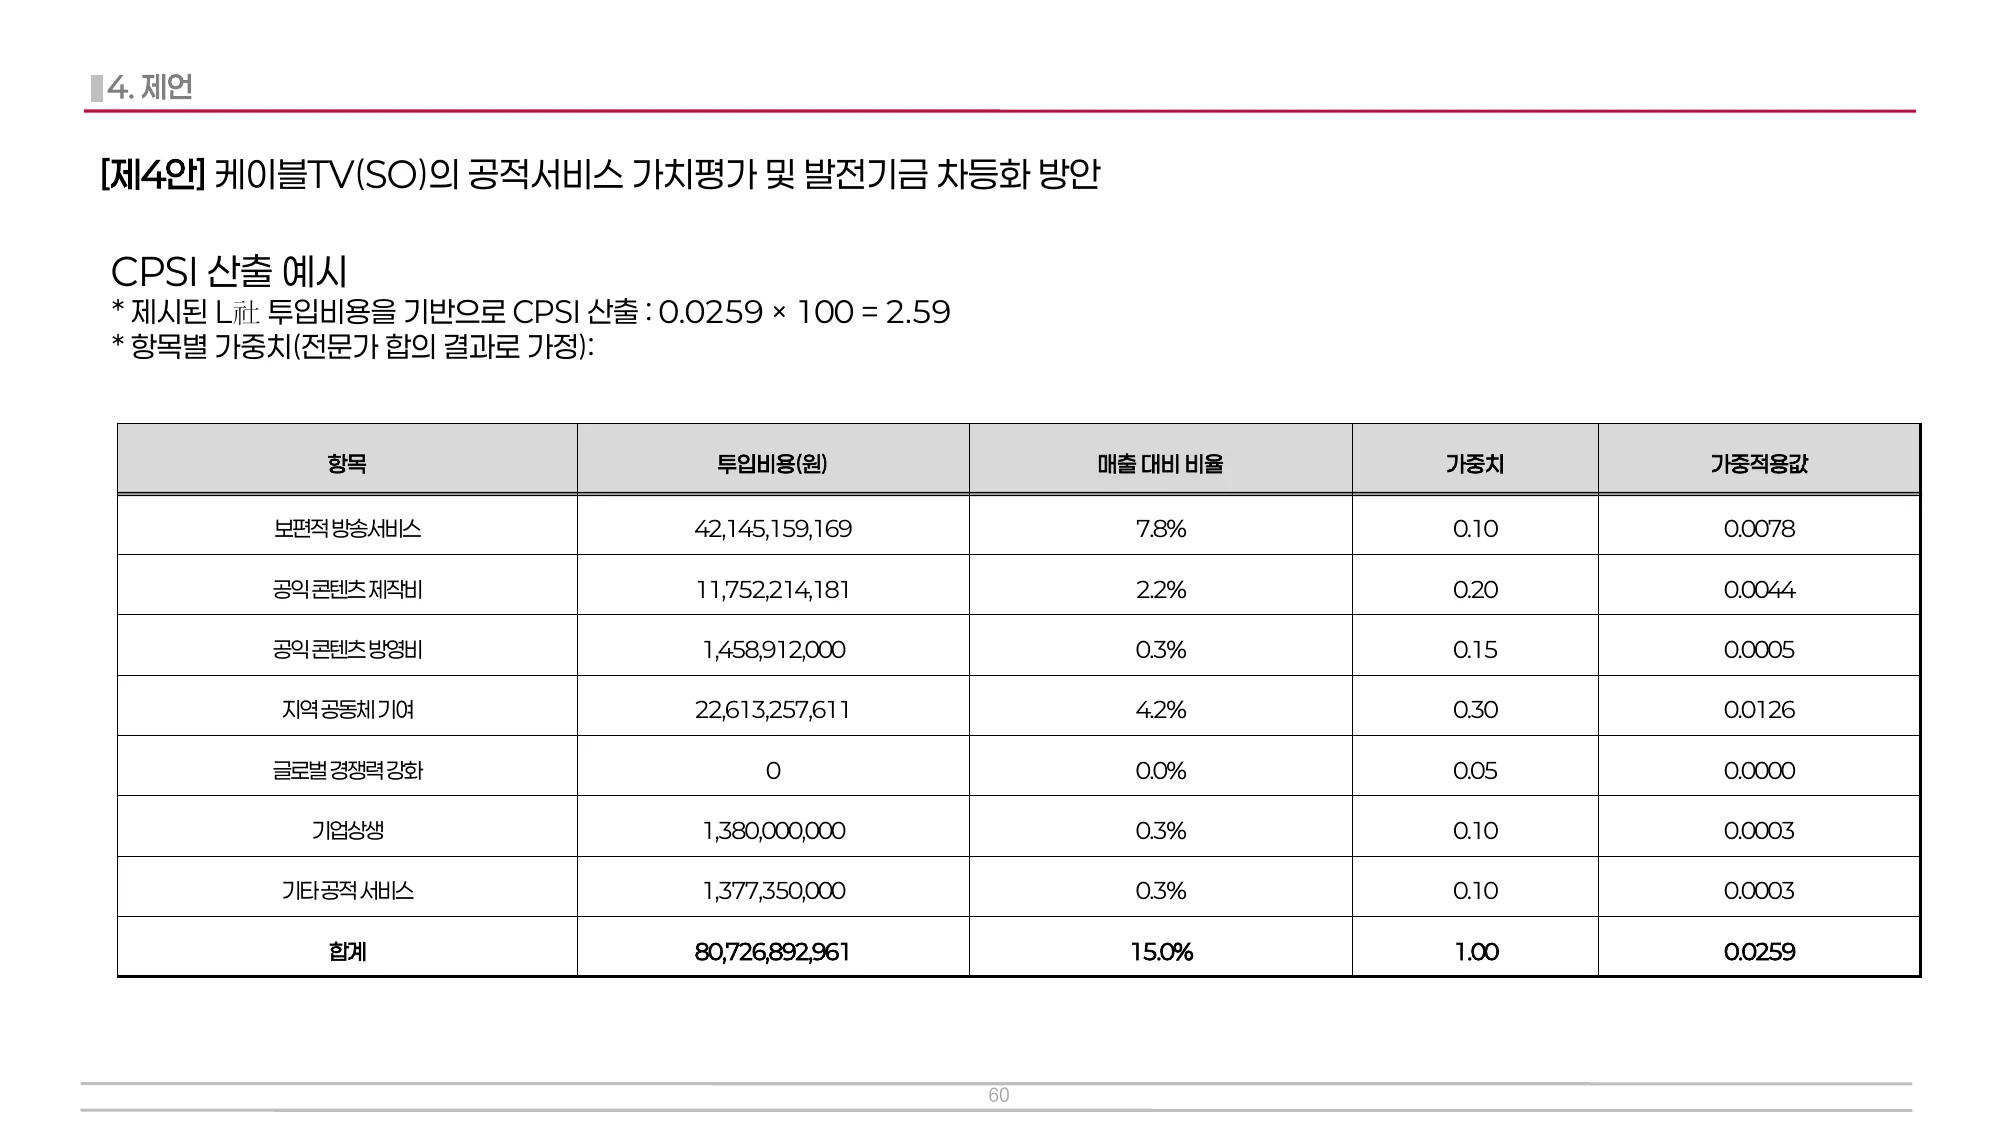
발표용 계산 예시와 검증된 제도를 구분Separate presentation examples from validated regulation
슬라이드는 문제 제기와 산식·시나리오를 압축한 자료이며 전체 분석 코드와 기업별 원자료를 독립 재현하지 않았습니다. 연도·수입 계획/실적·분모 차이, 반복된 표 항목과 가정 가중치를 그대로 확정값처럼 사용하는 일을 피했습니다. 특히 공익 지출을 인정하는 설계와 주민이 경험한 실제 공익 개선은 다릅니다. 자료의 정책 선호를 결과 검증과 구분하고, 제안 요율·CPSI를 현재 시행 제도나 객관적으로 인증된 점수로 표현하지 않습니다.
Slides compress arguments and calculations; underlying firm records and code have not been independently replicated. Dating, planned versus actual receipts, denominators, repeated entries and assumed weights limit interpretation. Recognizing public-service expenses differs from demonstrating benefits experienced by residents. Proposed rates and CPSI values are not current rules or certified performance scores.
PDF 파일 1, 16, 47, 51, 60쪽PDF pages 1, 16, 47, 51, 60
근거 쪽: Evidence pages: 1, 2, 3, 4, 5, 6, 7, 10, 16, 20, 24, 28, 30, 31, 35, 39, 45, 46, 47, 48, 49, 50, 51, 52, 54, 55, 56, 57, 58, 59, 60, 61, 62 · PDF 파일 기준, 인쇄 쪽수와 다를 수 있습니다. · PDF file pagination may differ from printed page numbers.
근거와 검토 범위Source and review scope
62쪽의 제공된 원문 자료를 기준으로 본문·표·선정 이미지를 확인했습니다. 해설은 연구 내용을 새 문장으로 정리했으며, 실제 원문 페이지를 함께 실었습니다. 분석 결과의 독립 재현이나 기관의 공식 입장 확인을 뜻하지 않습니다.
The text, tables and selected images were checked against the 62-page source document supplied for this site. This guide is an editorial summary accompanied by original source pages. This does not imply independent replication or institutional endorsement.
확인한 PDF 쪽: Source PDF pages: 1, 2, 3, 4, 5, 6, 7, 10, 16, 20, 24, 28, 30, 31, 35, 39, 40, 45, 46, 47, 48, 49, 50, 51, 52, 54, 55, 56, 57, 58, 59, 60, 61, 62